
Buying Calls and Puts: A Three-Step Framework
Buying a call and buying a put are the two most basic strategies available to option buyers.
You buy a call when you expect the underlying price to rise, and you buy a put when you expect it to fall. In practice, however, choosing the right direction is only part of the trade. The expiration date, strike price, and exit timing can all affect the final result.
A single-leg option buying strategy can therefore be approached in three steps:
- Decide on a direction.
- Choose a contract.
- Set an exit plan.
Step 1: Decide on a Direction
Before buying a call, you need a reason to expect the underlying price to rise. Before buying a put, you need a reason to expect it to fall.
That view may come from fundamental or technical analysis.
Fundamental analysis helps explain why the underlying may rise or fall. Possible reasons include changes in a company’s operations, shifts in industry conditions, or an important event that may affect the business.
Technical analysis can help identify a specific entry point, price target, and level at which the original trade setup would no longer be valid.
Suppose a stock forms a double bottom:
- The first low is $90.
- The second low is $92.
- The neckline formed by the two rebounds is $100.
After testing the lower area twice, the stock breaks above the $100 neckline on higher volume and closes at $102 that day.
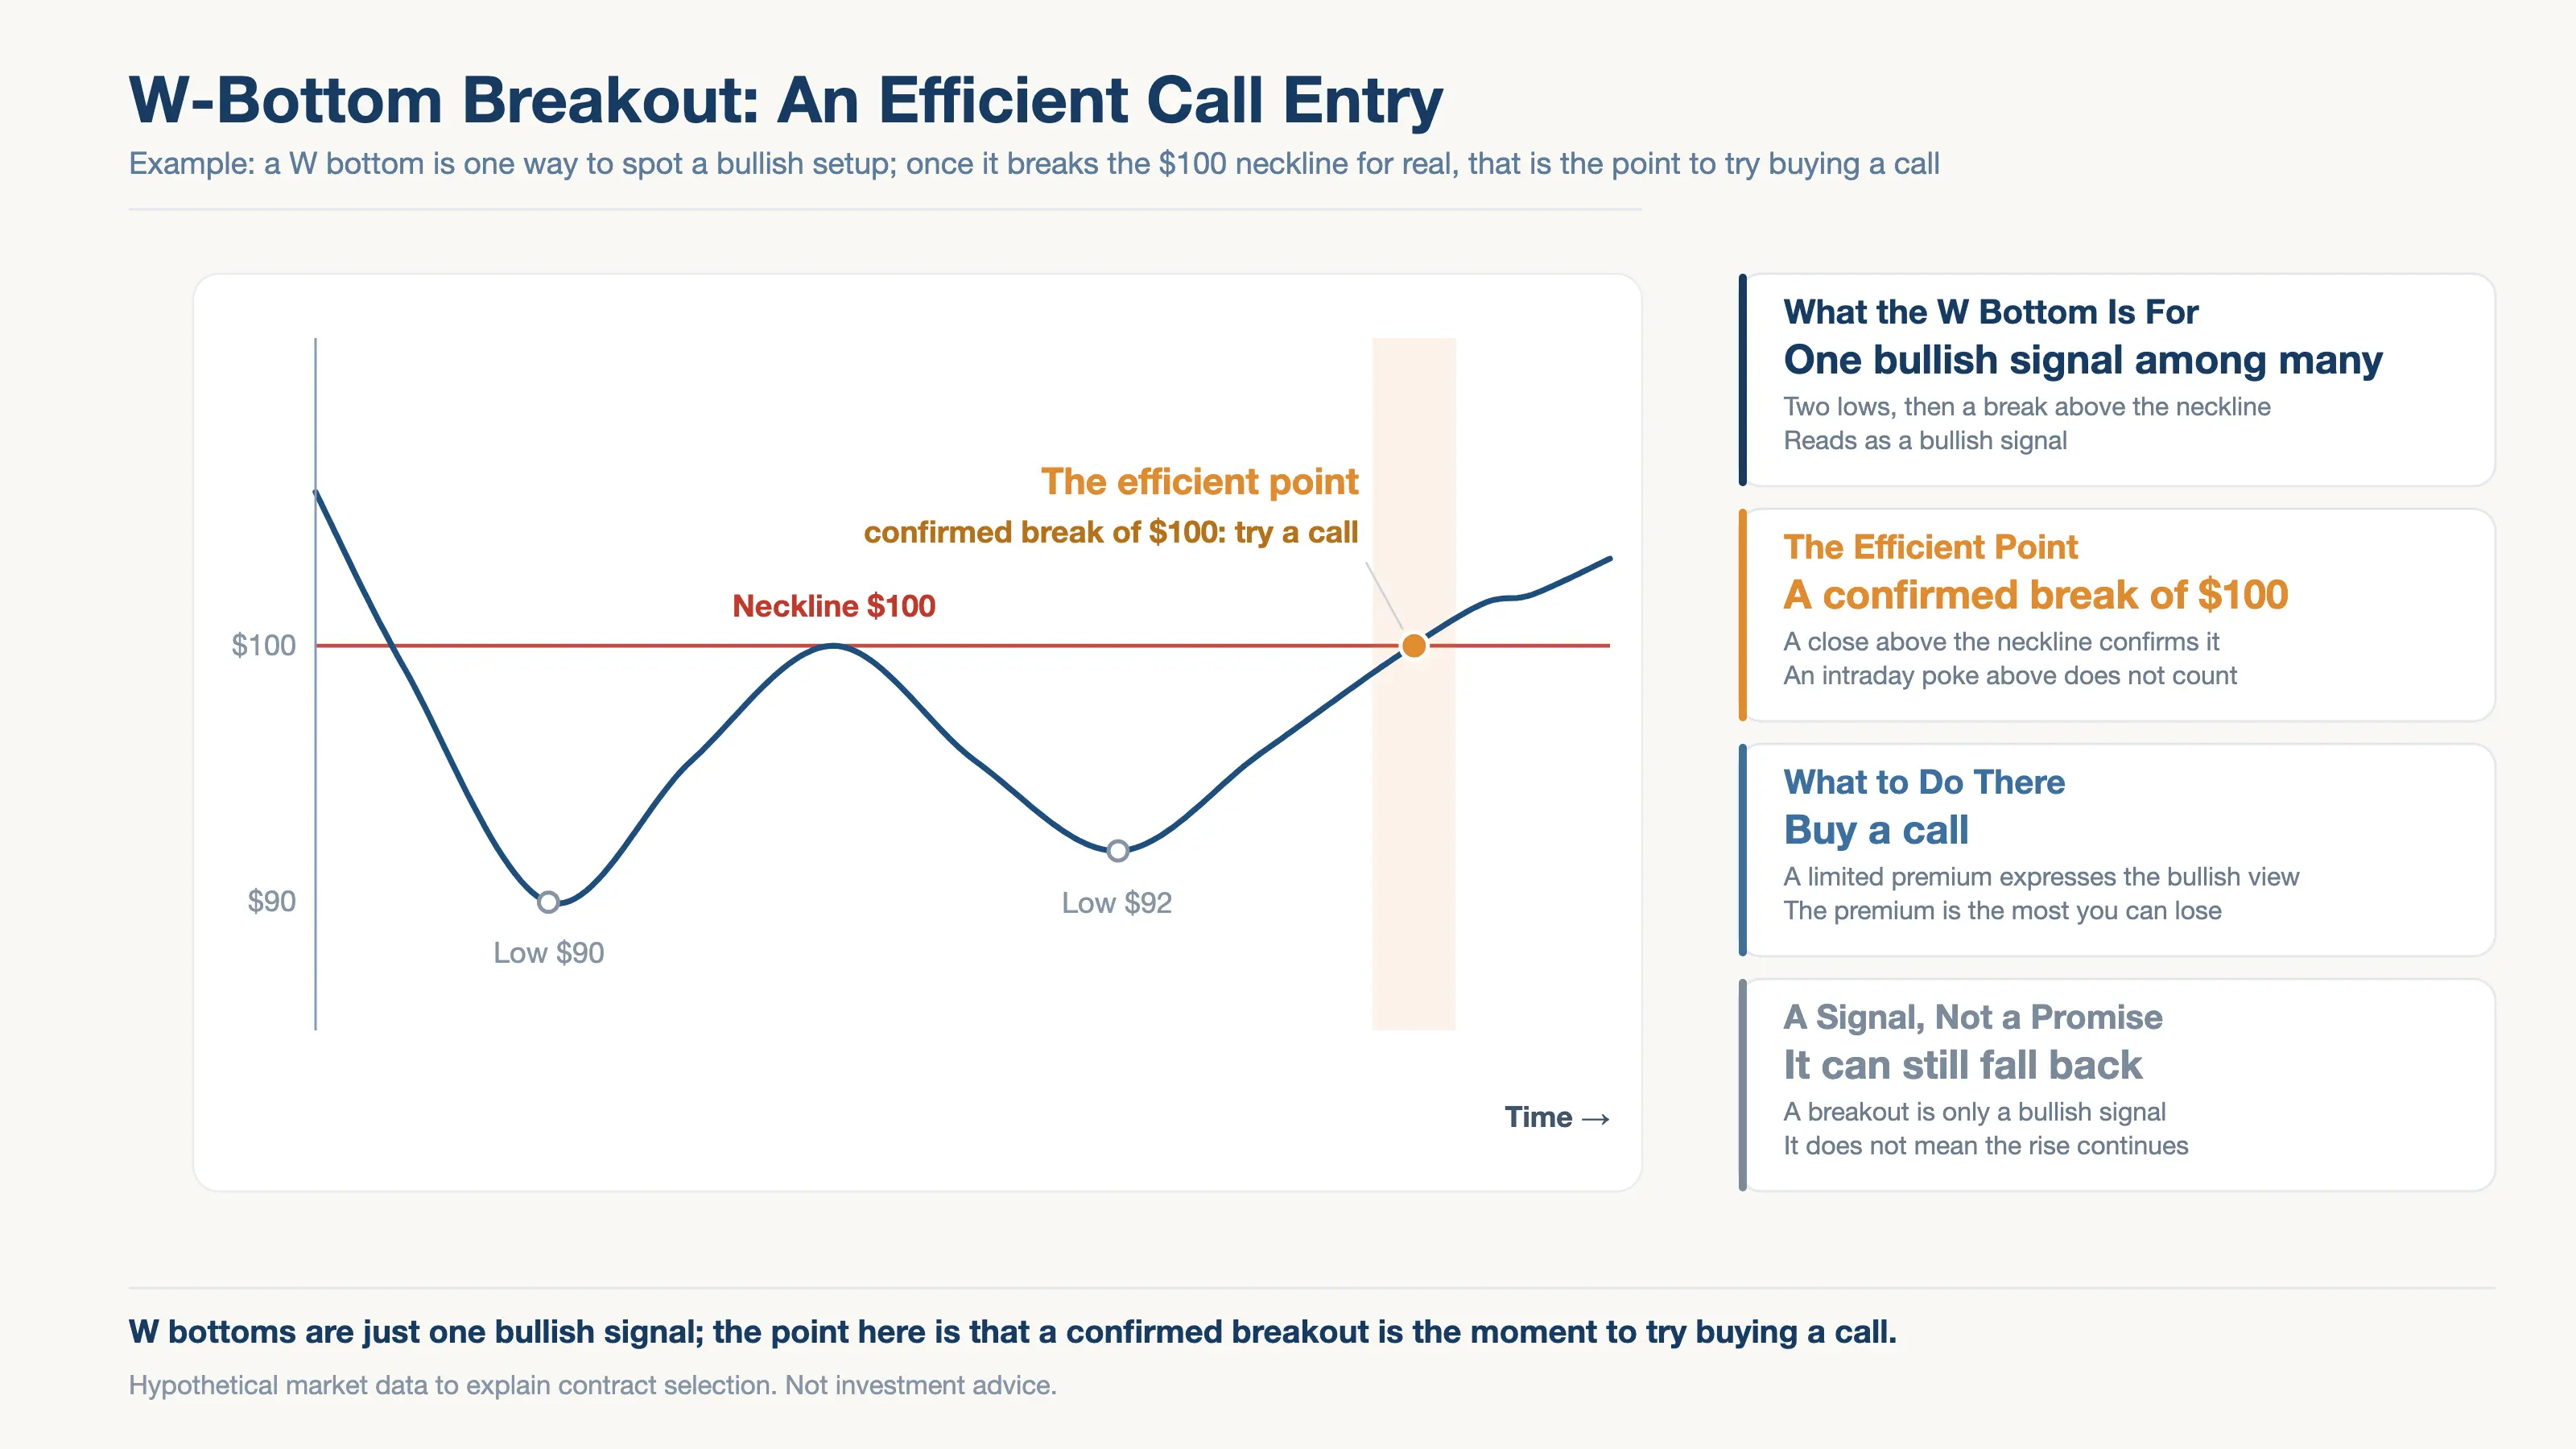
As discussed in the technical analysis course, a confirmed breakout above the neckline of a double bottom can be treated as a bullish signal. The day the breakout is confirmed is the entry point: you can try buying a call and establishing a position.
A brief move above the neckline during the day may not hold, so wait for the stock to close above it before treating the breakout as confirmed.
Step 2: Choose a Contract
Once the direction has been determined, the next step is to choose an expiration date and strike price from the option chain.
Suppose the double-bottom breakout is expected to take two to three weeks to reach its target. The option’s expiration date should cover that period and leave some additional time.
If you choose a contract with only a few days remaining, Theta decay may be rapid and Gamma may also change sharply. Even if the directional view is correct, the option may expire before the underlying reaches the target.
An option with much more time remaining provides a longer window for the trade to develop, but its premium will usually be higher.
The basic principle for choosing an expiration date is therefore: allow enough time for the expected move to develop, with some additional time to spare.
After choosing the expiration date, select a strike price.
For a single-leg buying strategy, at-the-money or slightly out-of-the-money options, such as a contract one strike out of the money, may be considered first. Their premiums are generally lower than those of in-the-money options, while their Delta is not so low that the option fails to respond meaningfully when the underlying moves in the favorable direction.
Return to the double-bottom example. The stock is trading at $102 after breaking above the neckline, and the estimated target is about $109. Suppose the option chain shows the following strikes and quotes:
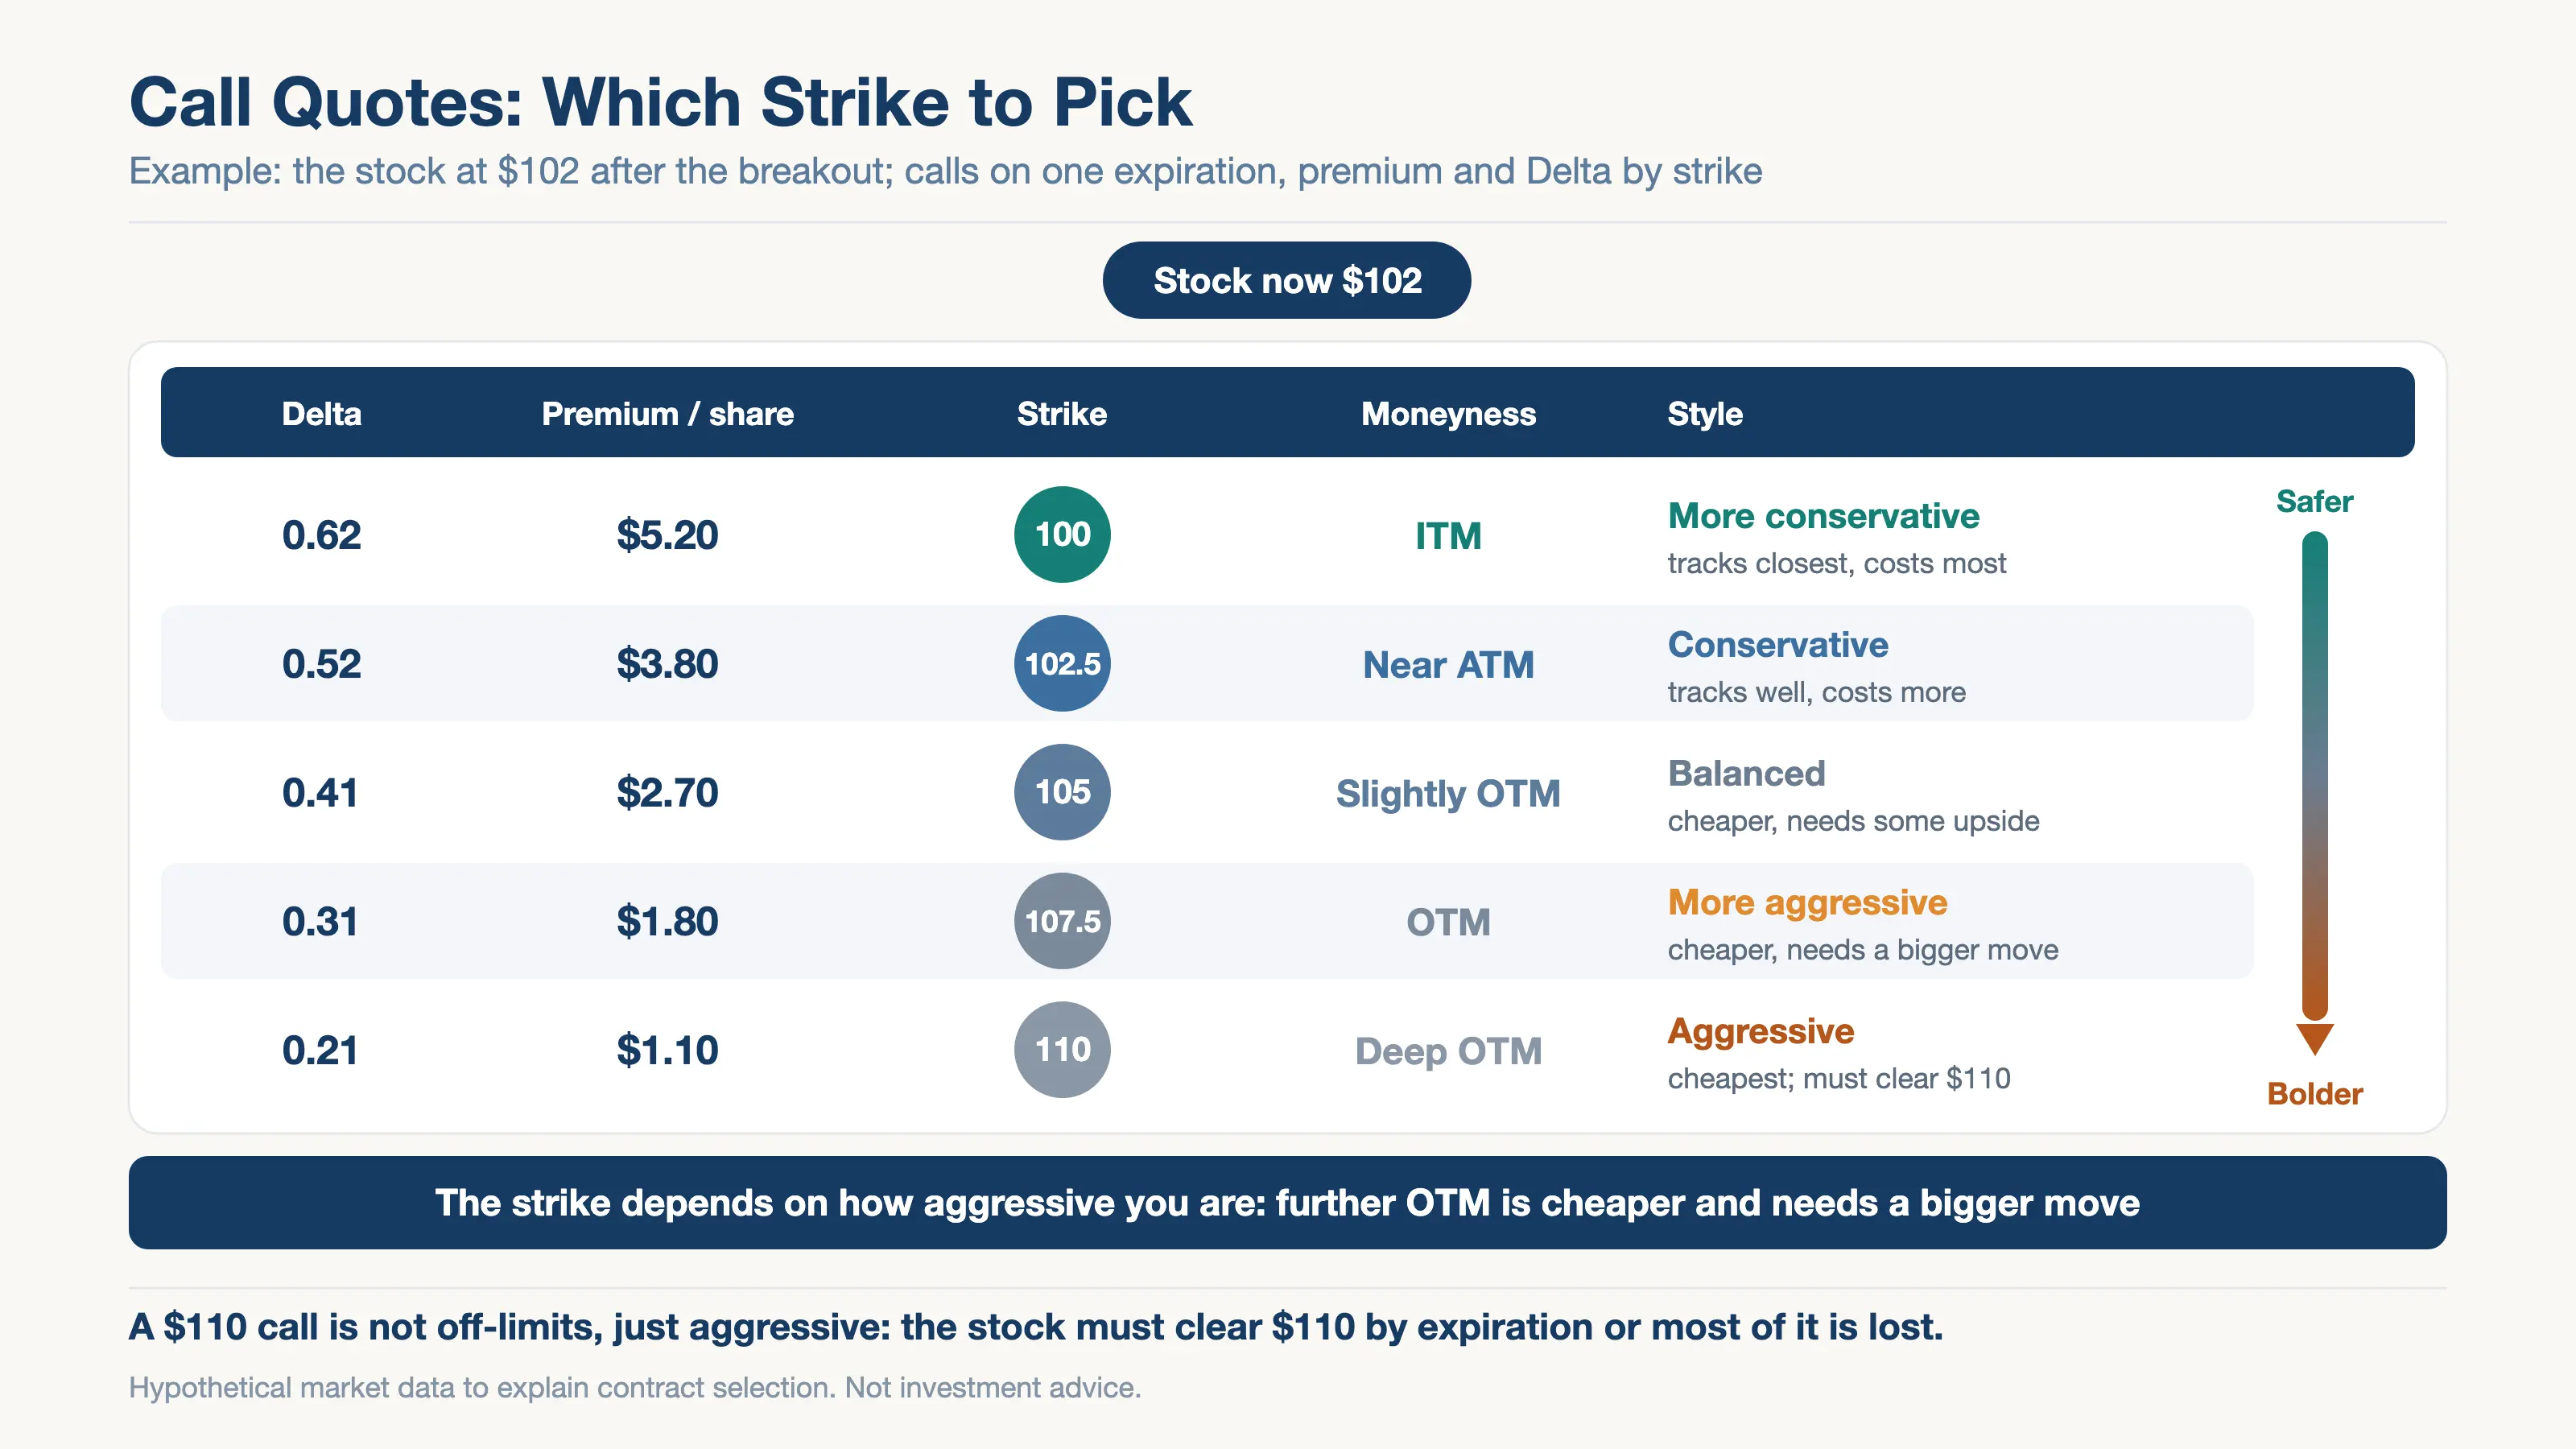
Although the pattern suggests a target of about $109, buying the $110 call is the more aggressive choice. Which strike to pick depends on how much risk you are willing to take.
A price target only indicates where the move may eventually reach. It does not tell us when the stock will get there. If the stock rises slowly, it may not reach the target before the option enters the period of rapid time decay near expiration.
Instead, you could compare the near-the-money $102.50 call with the slightly out-of-the-money $105 call:
- The $102.50 call has a Delta of 0.52. It follows changes in the stock more closely, but its premium is higher.
- The $105 call has a Delta of 0.41. Its premium is lower, but the stock needs to continue rising before the option gradually moves into the money.
The price target is mainly used to estimate where to exit. It does not have to be used as the strike price. When selecting a strike, compare at-the-money and slightly out-of-the-money contracts rather than automatically choosing the cheapest deep out-of-the-money option.
Consider Rolling After the Contract Moves into the Money
If the stock rises as expected but has not yet reached the final target, the original at-the-money or slightly out-of-the-money option may already have moved into the money.
Suppose the stock was trading at $102 when you bought the $102.50 call. The stock later rises to $106, and the option moves from near the money to in the money.
The option chain may now look like this:
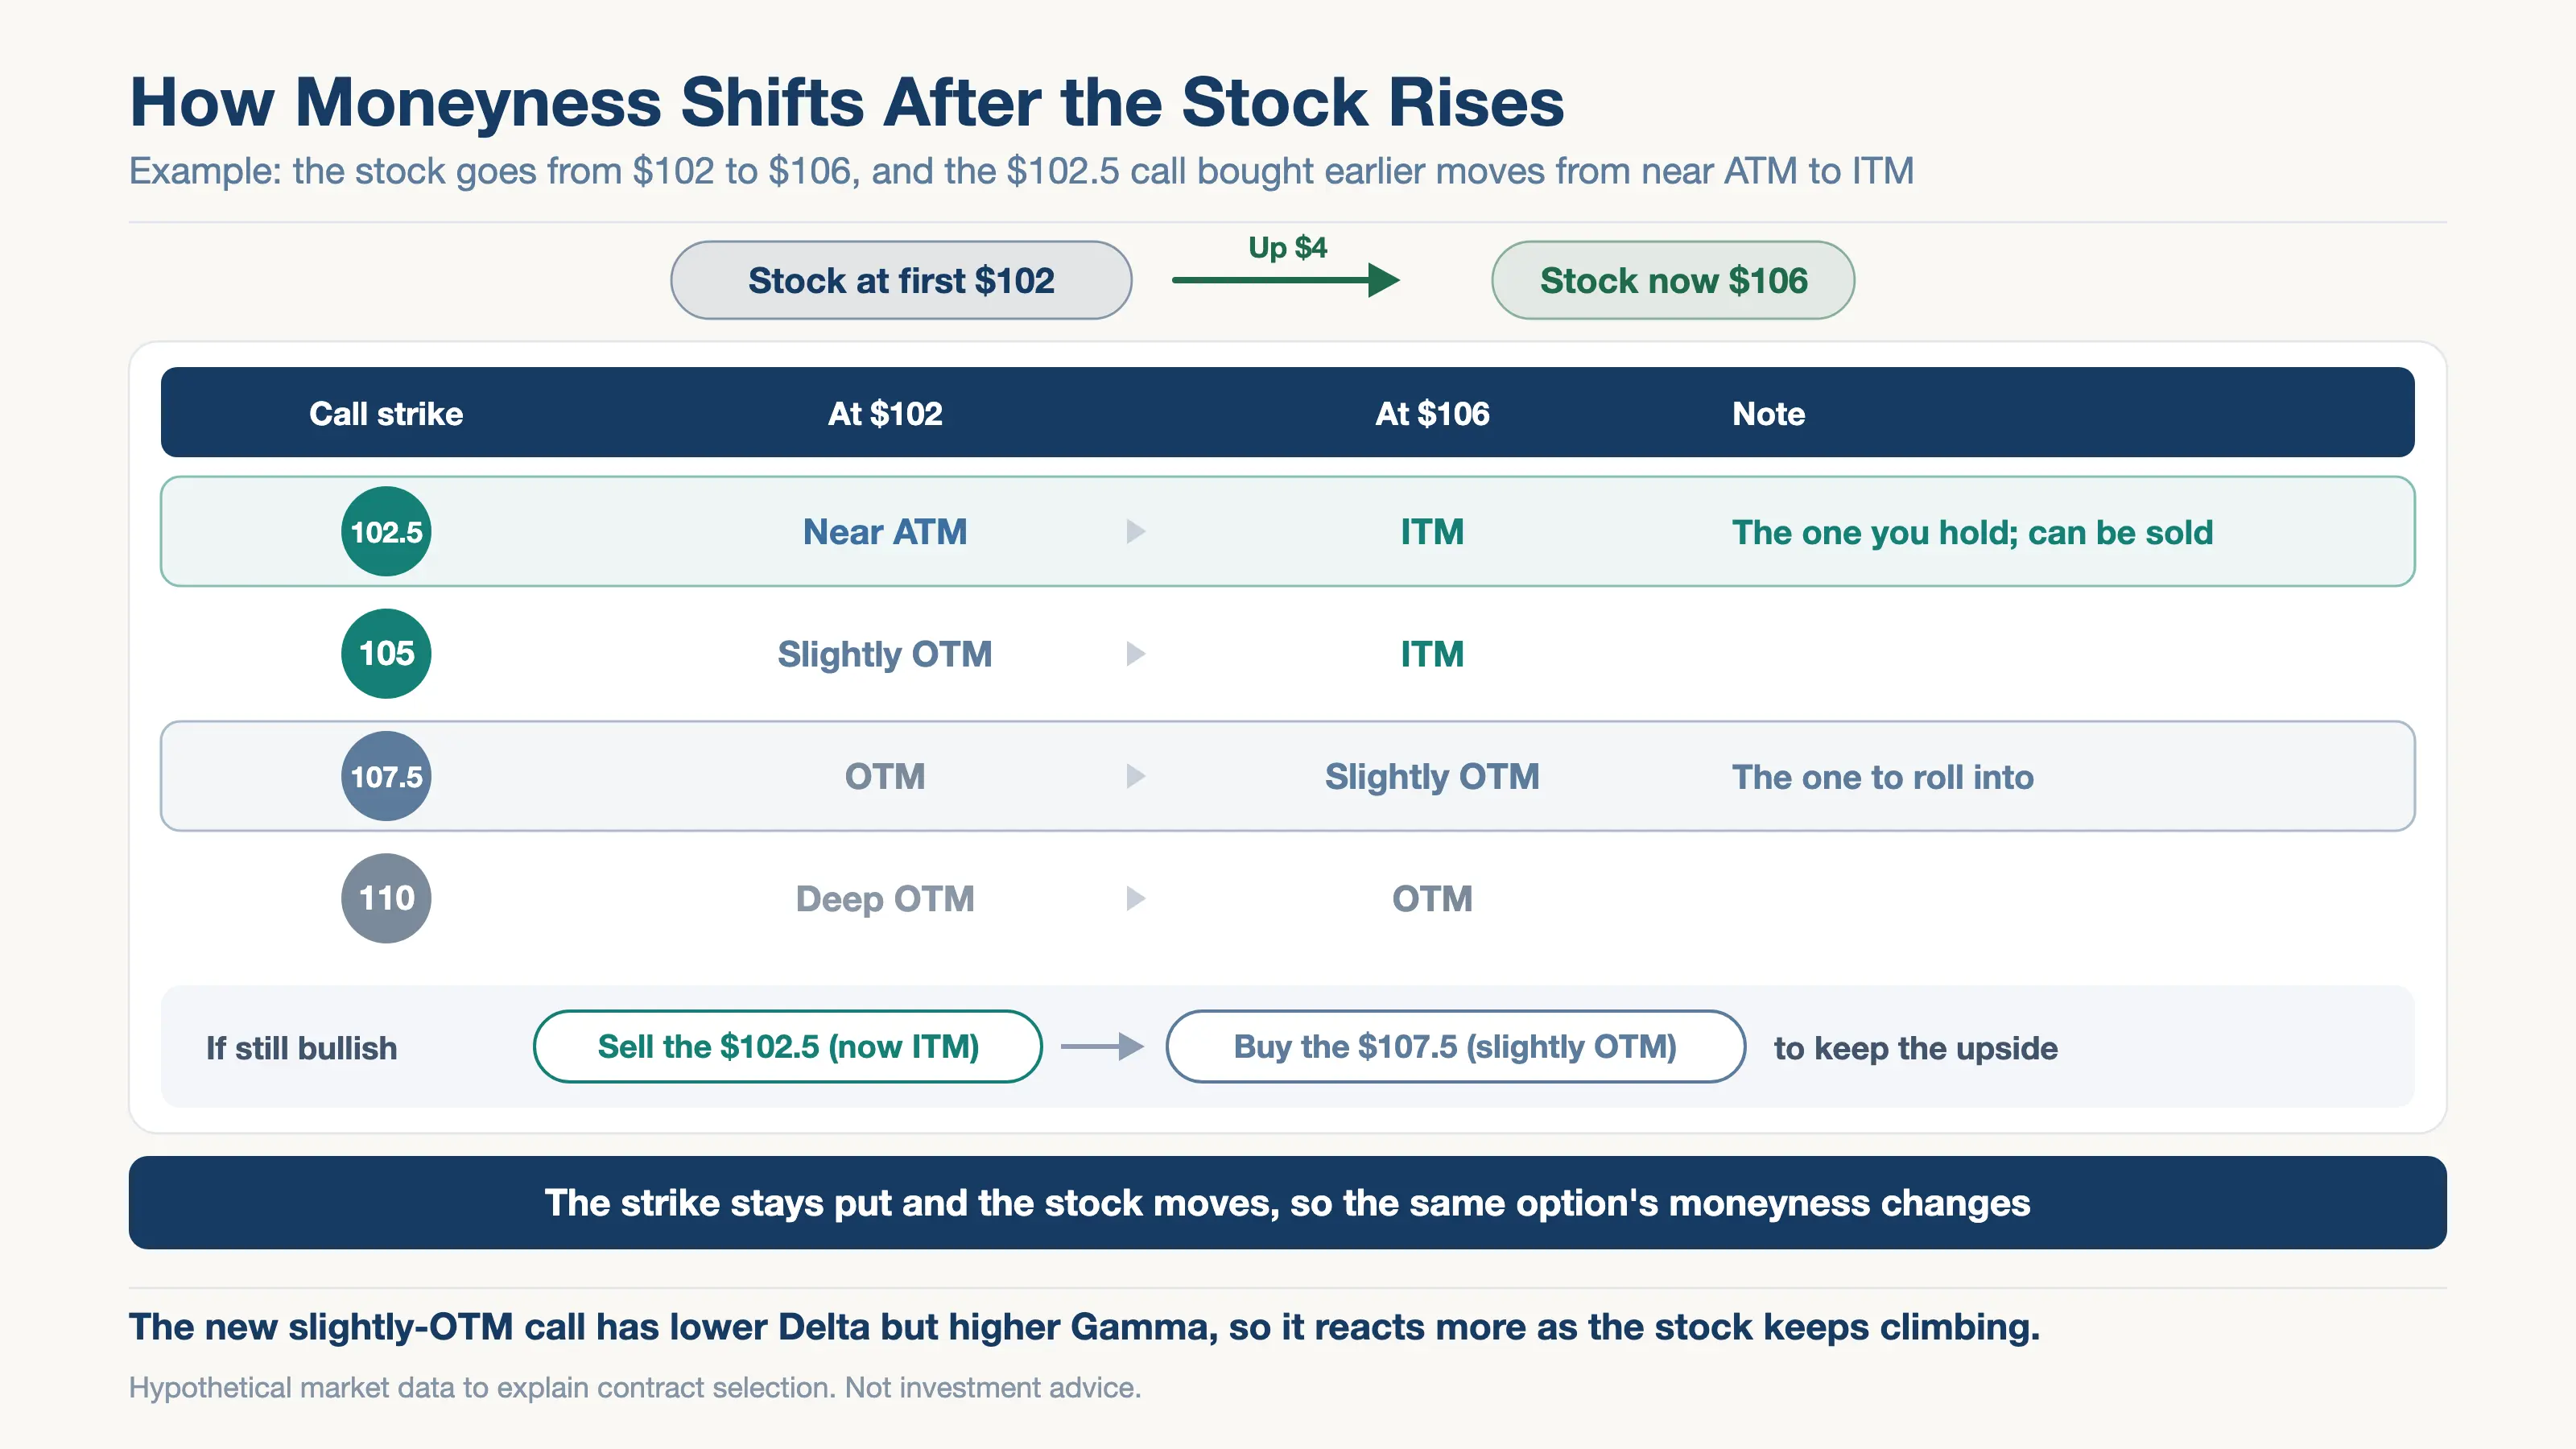
If the bullish view remains valid, you could sell the $102.50 call that has moved into the money and buy a slightly out-of-the-money $107.50 call, maintaining the bullish position. This is known as rolling the strike.
The original in-the-money option has a relatively high Delta, so its price will generally follow small changes in the stock more closely. However, it is already in the money, so its Delta can only approach 1 and has limited room left to rise.
The new slightly out-of-the-money option has a lower Delta but is closer to the at-the-money area, and its Gamma is slightly higher. If the stock continues to rise toward or above $107.50, the new contract’s Delta has plenty of room to increase, making its price increasingly responsive to further gains in the stock.
Because the new contract has a lower premium, the same increase in the option price may also produce a larger percentage return. Rolling therefore realizes the profit already earned on the original contract and uses less capital to seek additional upside exposure.
When rolling, you can keep the number of contracts unchanged: sell the original contracts and buy the same number of new ones. Because the new contracts are cheaper, the same number ties up less capital, which works as a form of partial profit-taking. If you are especially bullish, you can buy more contracts, as long as the new premium stays within your risk limit.
Suppose you originally bought 10 contracts of the $102.50 call at $3.80 per share. Since each contract usually represents 100 shares, the total premium paid was:
$3.80 × 100 × 10 = $3,800
After the stock rises, the option price increases to $6.10. Selling all 10 contracts brings in:
$6.10 × 100 × 10 = $6,100
The realized profit on the original position is:
$6,100 − $3,800 = $2,300
You then buy 10 contracts of the $107.50 call at $3.30 per share, paying:
$3.30 × 100 × 10 = $3,300
The stock then keeps rising and reaches the estimated target of about $109. The price of the new option rises to $4.50. Selling all 10 contracts brings in:
$4.50 × 100 × 10 = $4,500
The profit on the new position is:
$4,500 − $3,300 = $1,200
Ignoring trading costs, the two trades together make:
$2,300 + $1,200 = $3,500 in profit
Rolling does not always end in a profit. Whether the overall trade can retain a profit depends on one comparison:
Is the realized profit from the original contract greater than the premium paid for the new contract?
In this example, the new contracts cost $3,300, more than the $2,300 already realized. If they expire worthless, the loss on the second trade exceeds the profit from the first, and the overall trade loses $1,000.
After the roll, the new contract may not gain more in dollar terms than the original in-the-money option. However, its percentage return relative to the premium paid may respond more strongly.
Suppose the two contracts have the following figures at the time of the roll:
Contract | Option price | Delta | Gamma |
Original $102.50 in-the-money call | $6.10 | 0.69 | 0.038 |
New $107.50 slightly out-of-the-money call | $3.30 | 0.48 | 0.042 |
If the stock rises by $1, the original in-the-money option is expected to increase by approximately $0.69, while the new option is expected to increase by approximately $0.48. In dollar terms, the original option gains more.
Relative to the option prices, however:
- A $0.69 increase in the original contract is approximately 11.3% of its $6.10 price.
- A $0.48 increase in the new contract is approximately 14.5% of its $3.30 price.
If the stock continues to rise and the new contract moves closer to and into the money, its Delta keeps rising, which may increase the percentage return further.
This sensitivity also works in the opposite direction. If the stock stops rising or begins to fall, the new contract has no intrinsic value and its premium is all time value, so it may lose value faster in percentage terms.
Rolling should therefore be considered only when the bullish view remains valid, sufficient time remains before expiration, and the premium paid for the new position stays within an acceptable risk limit.
Step 3: Set an Exit Plan
Before buying an option, decide when to take profit, when to cut the loss, and the latest time at which the position should be closed.
Exit When the Price Target Is Reached
The estimated target for this double bottom is approximately $109. When the stock approaches $109, most of the projected move from the pattern has already occurred. At that point, you can consider selling the call and realizing the profit.
There is no need to hold the option until expiration. Selling it earlier also allows you to recover any remaining time value.
Exit When the Bullish View Is No Longer Valid
This trade is based on the stock breaking above the $100 neckline.
If the stock falls back below $100 after the breakout and cannot move back above the neckline, the original breakout may have failed. In that case, you may need to exit even though the option has not yet expired.
A technical stop is based not on how much the option has lost, but on whether the original reason for entering the trade remains valid.
Set the Latest Time to Hold
Options expire, and a move does not always follow the expected schedule. When buying, set a review date based on the expected timeline (two to three weeks in this example). If that date arrives and the stock has neither reached the target nor triggered the failure level, reassess whether to keep holding instead of waiting until expiration is near, when time value decays fastest.
Use the Maximum Acceptable Loss to Determine Position Size
The maximum loss for an option buyer is the full premium paid. Before placing an order, first decide how much you are willing to lose if the trade fails completely. That amount can then be used to determine how many contracts to buy.
Suppose one contract costs $500 and the most you are willing to lose is $1,000. The maximum number of contracts would be:
$1,000 ÷ $500 = 2 contracts
Even if both contracts expire worthless, the maximum loss remains limited to $1,000. This can be understood as a built-in loss limit for the option buyer: as long as no additional contracts are added, the loss cannot exceed the premium originally paid.
Buying Puts Uses the Same Process
If a topping pattern breaks down, or fundamental analysis supports a bearish view, the same process can be applied when buying puts:
- Confirm the direction after the breakdown.
- Choose an expiration date that covers the expected downward move.
- Select an at-the-money or slightly out-of-the-money put.
- Use the technical pattern to estimate a price target.
- Decide in advance when to take profit, cut the loss, and close the position at the latest.
Buying calls and buying puts express opposite directional views, but the trading process is the same: decide on a direction, choose a contract, and set an exit plan.
Next lesson, we will move on to debit spreads and see how selling another option can reduce the premium required for a single-leg long option position.
Disclaimer
This content is for investor education and information sharing only. It's meant to help readers understand relevant financial concepts and indicators, and it does not constitute investment advice, an offer, or a commitment of any kind. Any views, data, or analysis mentioned are general in nature and should not be taken as a recommendation for any specific investment product or strategy.
Investing carries risk, and market fluctuations can result in loss of principal. Before making any investment decision, readers should exercise independent judgment based on their own financial situation, investment objectives, and risk tolerance, or consult a licensed financial advisor. The author and publisher of this content are not liable for any direct or indirect losses arising from reliance on it.
Related Courses
Getting Started with Options
Contracts, Quotes, and the Four Basic Positions
Option Prices and the Greeks
Why Option Prices Rise and Fall
Common Options Market Indicators
Understanding Volatility and Market Sentiment
Option Selling Strategies
Collecting Premium While Managing Risk
Stock-and-Option Strategies
A Stock Has Two Directions. Options Have More.
Short-Dated Options and 0DTE
Buyers want speed; sellers want time to run out.