D
 +1
HSAI: Soft guidance — is the sector leader stalling?
Prices have stabilized, but volumes haven’t caught up.
Profit recovery is now pushed back to 2027.+1
Prices have stabilized, but volumes haven’t caught up.
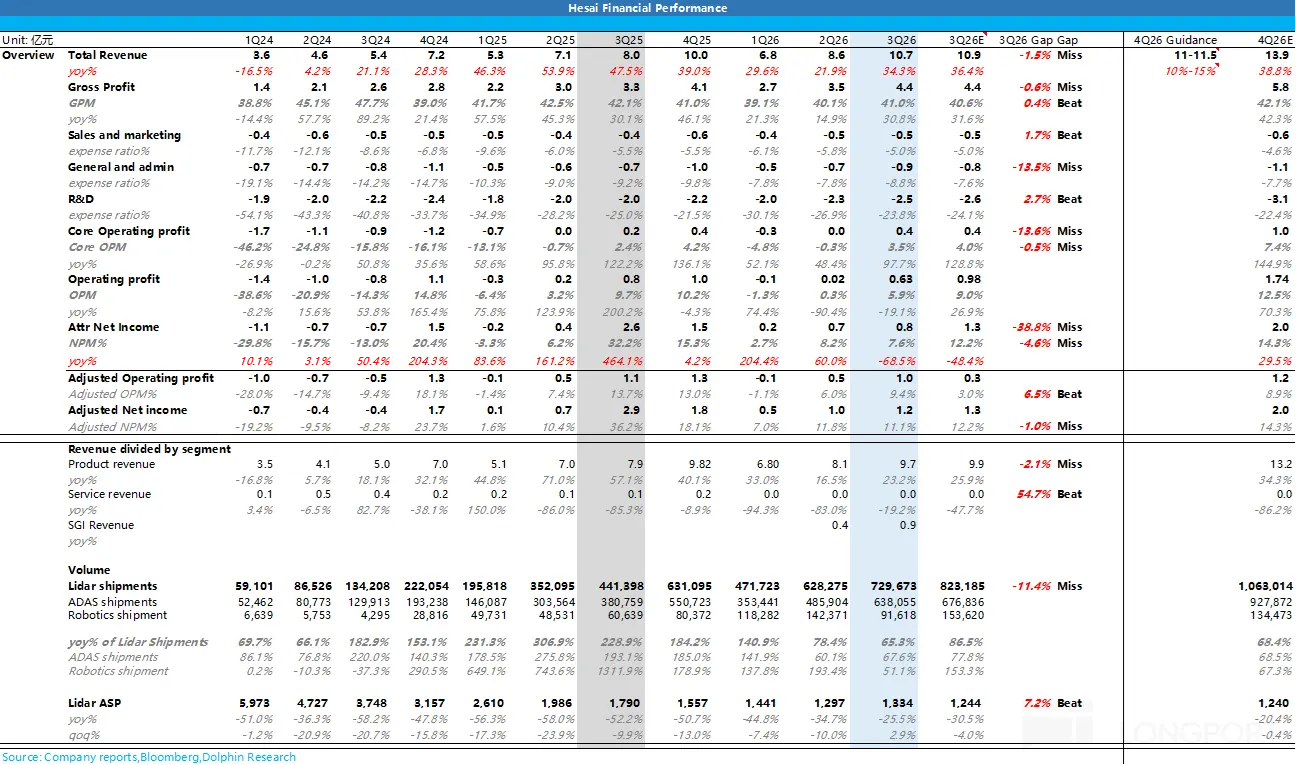
Profit recovery is now pushed back to 2027.+1Robot-related businesses made up over 50% of Q3 revenue. SGI generated RMB 135 mn in revenue in the first nine months, already beating the full-year RMB 100 mn target.
However, softer auto demand led the company to guide Q4 revenue of only RMB 1.1–1.15 bn. It is increasing SGI R&D, aiming for around $100 mn in revenue by 2027 and to reach breakeven.
Sacrifice margin to defend share, ride out deflation until the turn?
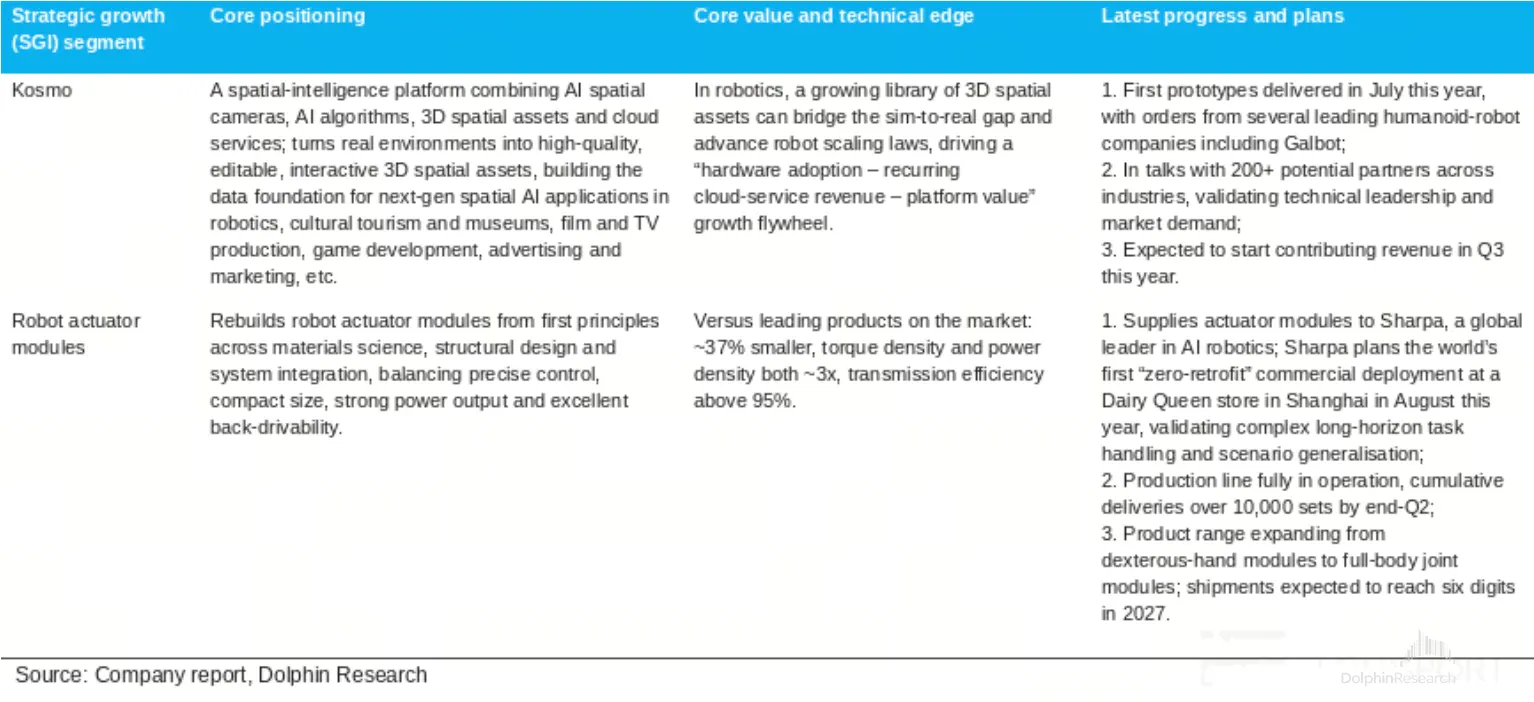
Guidance for 2026 SGI (Strategic Growth Initiatives) revenue was raised from RMB 100 mn to RMB 200–300 mn. Management also guided to around $100 mn revenue in 2027 with breakeven in the same year.
The segment still posted an OP loss of RMB 64 mn this quarter. R&D expense rose in tandem to RMB 231 mn.Meanwhile, beyond lidar, the company is positioning actuator modules and Kosmo as its second growth curve. Q3 non-ADAS revenue is expected to approach, or even exceed, half of total revenue.Q2 total revenue is expected at RMB 850–900 mn.
LiDAR shipments are estimated at ~650k units.2026 will remain a 'price-for-volume' year for Hesai Group amid high-stakes competition.
Overall GPM is expected to remain resilient in 2026. Resilience should hold through the year.
FY26 shipment guidance raised sharply to 3.0-3.5 mn units
The collaboration with BYD currently covers more than ten models, and more new models will gradually achieve mass production from 2025 to 2026.