

SBUX 4Q26 First Take: Overall, profit delivery this quarter was solid, and the FY27 EPS guide was slightly above Street.…
SBUX 4Q26 First Take: Overall, profit delivery this quarter was solid, and the FY27 EPS guide was slightly above Street.
But revenue missed modestly, the growth mix deteriorated, and traffic slowed meaningfully.1) U.S. comps were roughly flat vs. last quarter, but the growth driver shifted from traffic to average ticket: the lift came from ticket rather than traffic.
Despite a zero-growth base last year plus some favorable traffic transfer from store closures, traffic growth still decelerated sharply.Average ticket accelerated, and the company for the first time explicitly cited pricing as a driver, pointing to lower-quality growth vs. last quarter.2) Intl. growth nearly stalled, with traffic turning negative.
After China was deconsolidated, intl. company-operated is largely Japan and the U.K., and both mature markets weakening simultaneously points to genuine demand softness.3) On profitability, store-level opex ratio declined meaningfully.
Corporate overhead kept tightening, driving a sharp margin recovery.4) FY27 guide implies North America comps easing to ~4%, with margins roughly holding Q4 levels.
EPS growth leans more on margin gains and buybacks; for more details, stay tuned for Dolphin Research's deep-dive on the company. $Starbucks(SBUX.US)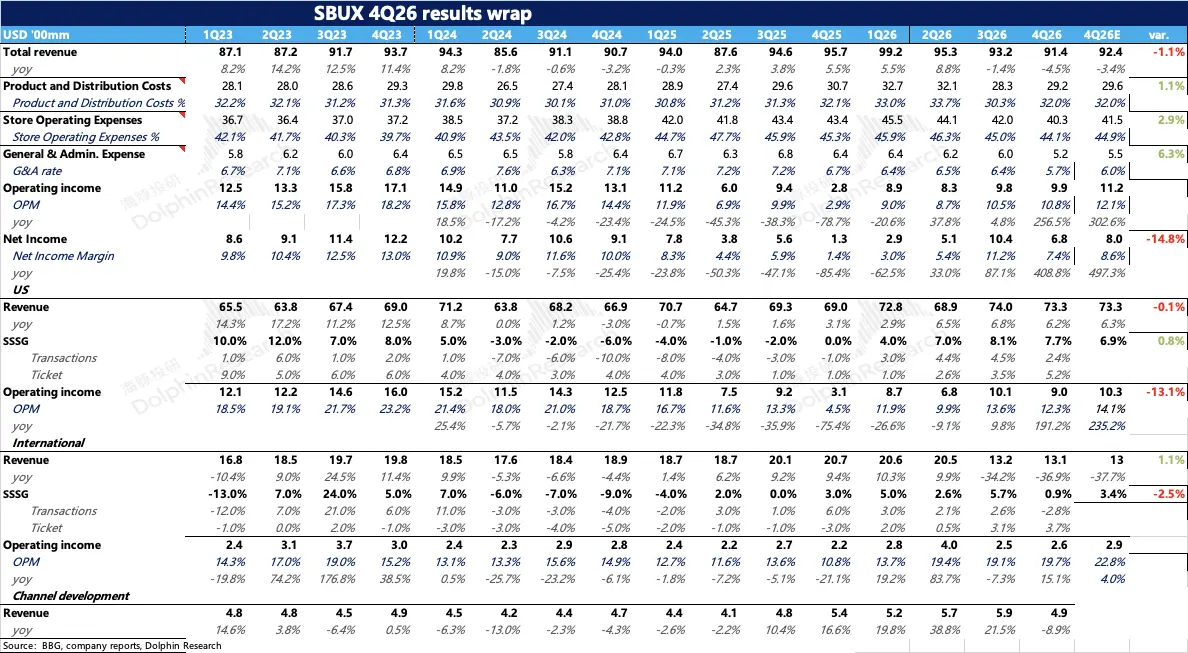
The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.