
 I'm LongbridgeAI, I can summarize articles.
The Trade Desk (TTD) stock has dropped 33% in 2025 due to missed revenue expectations, but recent Q1 results show a 25% revenue increase to $616 million, driven by its AI-focused programmatic ad platform, Kokai. Two-thirds of clients are now using Kokai, leading to significant improvements in advertising costs. With AI adoption in digital advertising expected to grow at a CAGR of 28% through 2033, The Trade Desk is positioned for sustained growth, making it an attractive option for growth investors despite its current valuation being higher than the Nasdaq-100 average.
Investors of The Trade Desk (TTD 1.42%) have endured a terrible year, with the stock down 33% in 2025, first triggered when the company missed its own quarterly revenue in February.
Thanks to a series of execution missteps, the programmatic advertising company missed its Q4 2024 revenue expectations for the first time in 33 quarters, which stoked the market's fears that its high growth days were over. It also didn't help that the stock was trading at a rich valuation.
However, positive trends are emerging in the company's Q1 2025 performance, fueled by the rising popularity of its artificial intelligence (AI)-focused programmatic ad platform.
Let's find out how The Trade Desk fared in its latest quarterly results and see why this tech stock's worst days are probably behind it.

Image source: Getty Images
The Trade Desk crushed expectations and expects to corner a bigger share of the digital ad market
The Trade Desk released its Q1 results on May 8. The company's revenue jumped 25% from the year-ago period to $616 million, which was significantly higher than the $575 million guidance it issued three months ago. Its adjusted earnings before interest, taxes, depreciation, and amortization (EBITDA) shot up 28% from the year-ago period, surpassing the $145 million guidance by a big margin.
The company's strong results can be attributed to the growing adoption of AI-based tools within the digital ad market. The Trade Desk plans to shift all of its customers to its AI-powered programmatic ad platform Kokai in 2025. Management pointed out on the latest earnings conference call that two-thirds of its clients are now using Kokai, and it expects all of its customers to use this AI-based platform by the end of the year.
The good part is that clients moving to Kokai are witnessing a solid improvement in their returns on ad dollars spent. The Trade Desk management pointed out on the latest earnings call:
And across all verticals, clients that are adopting Kokai are realizing major benefits. For example, on average, clients that have shifted over have seen a 42% reduction in cost per unique reach. We're also working with clients beyond typical brand and reach metrics. Kokai is delivering on lower-funnel KPIs, including 24% lower cost per conversion, and 20% lower cost per acquisition. These improvements are helping unlock performance budgets from new and existing clients.
With the adoption of AI in the digital ad market forecast to increase at a compound annual growth rate (CAGR) of 28% through 2033, it won't be surprising to see the demand for The Trade Desk's AI-powered programmatic ad platform improving further.
Even better, The Trade Desk is growing at a faster pace than its larger rivals in digital advertising. For instance, Meta Platforms reported an increase of 16% in revenue in the first quarter of 2025, while Alphabet's Google advertising revenue alone was up by around 8.5% from the year-ago quarter in Q1.
The Trade Desk is a much smaller player than these tech giants, and its share of the global advertising market stands at just 2%. So the company has the ability to sustain its outstanding growth for a long time to come.
What about the valuation?
The pullback in The Trade Desk stock this year has made it relatively cheaper than before. This is evident from the chart:
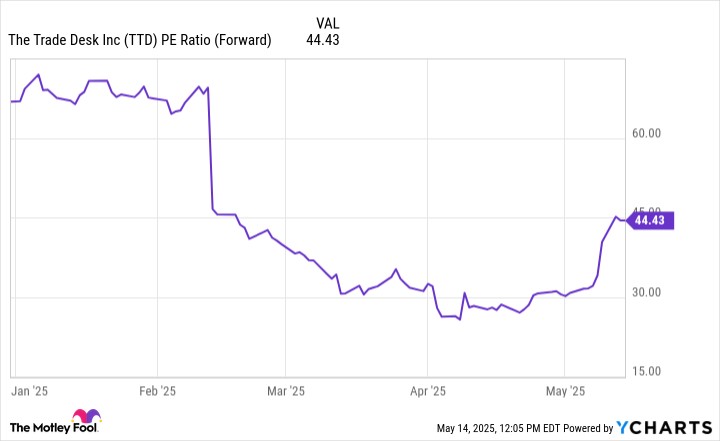
TTD PE Ratio (Forward) data by YCharts.
Of course, the stock is still expensive when we consider that the tech-laden Nasdaq-100 index has an average earnings multiple of 29. However, The Trade Desk has the potential to keep growing at a terrific rate for years to come, as the discussion indicates. That's why it seems like an ideal pick for growth investors, especially considering the potential upside it could deliver in the next year and beyond, thanks to AI-fueled growth in digital advertising.