
 I'm LongbridgeAI, I can summarize articles.
Lumos Diagnostics Holdings Limited (ASX:LDX) shares dropped 27% recently, reversing previous gains, yet the stock has surged 356% over the past year. Despite the decline, the company's price-to-sales (P/S) ratio stands at 9.1x, significantly higher than many peers in the Medical Equipment industry. Analysts forecast a 69% revenue growth for Lumos next year, outpacing the industry average of 53%. While the high P/S reflects investor confidence in future growth, caution is advised as the stock's valuation may be at risk if revenue expectations are not met.
Lumos Diagnostics Holdings Limited (ASX:LDX) shareholders won't be pleased to see that the share price has had a very rough month, dropping 27% and undoing the prior period's positive performance. Regardless, last month's decline is barely a blip on the stock's price chart as it has gained a monstrous 356% in the last year.
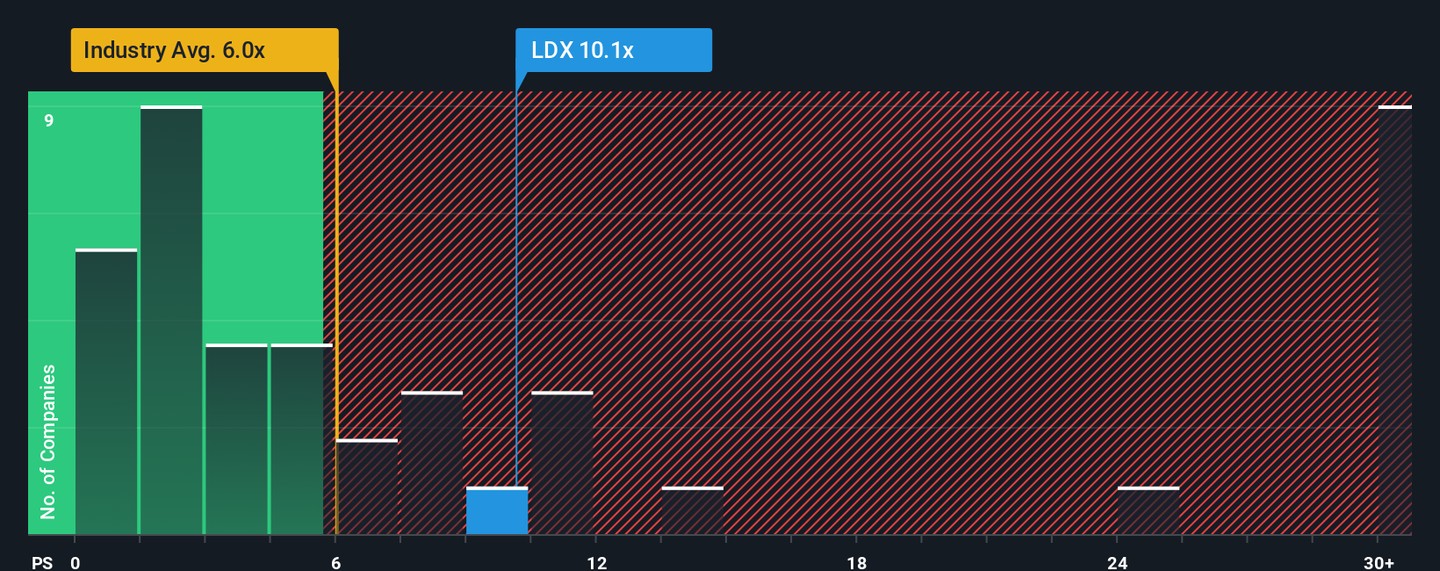
Although its price has dipped substantially, Lumos Diagnostics Holdings may still be sending strong sell signals at present with a price-to-sales (or "P/S") ratio of 9.1x, when you consider almost half of the companies in the Medical Equipment industry in Australia have P/S ratios under 6x and even P/S lower than 2x aren't out of the ordinary. Nonetheless, we'd need to dig a little deeper to determine if there is a rational basis for the highly elevated P/S.
This technology could replace computers: discover the 20 stocks are working to make quantum computing a reality.
Check out our latest analysis for Lumos Diagnostics Holdings
How Lumos Diagnostics Holdings Has Been Performing
Recent times have been advantageous for Lumos Diagnostics Holdings as its revenues have been rising faster than most other companies. The P/S is probably high because investors think this strong revenue performance will continue. However, if this isn't the case, investors might get caught out paying too much for the stock.
Keen to find out how analysts think Lumos Diagnostics Holdings' future stacks up against the industry? In that case, our free report is a great place to start.
Is There Enough Revenue Growth Forecasted For Lumos Diagnostics Holdings?
There's an inherent assumption that a company should far outperform the industry for P/S ratios like Lumos Diagnostics Holdings' to be considered reasonable.
If we review the last year of revenue growth, the company posted a worthy increase of 11%. The latest three year period has also seen a 6.6% overall rise in revenue, aided somewhat by its short-term performance. Accordingly, shareholders would have probably been satisfied with the medium-term rates of revenue growth.
Turning to the outlook, the next year should generate growth of 69% as estimated by the only analyst watching the company. With the industry only predicted to deliver 53%, the company is positioned for a stronger revenue result.
With this in mind, it's not hard to understand why Lumos Diagnostics Holdings' P/S is high relative to its industry peers. It seems most investors are expecting this strong future growth and are willing to pay more for the stock.
The Final Word
Lumos Diagnostics Holdings' shares may have suffered, but its P/S remains high. Using the price-to-sales ratio alone to determine if you should sell your stock isn't sensible, however it can be a practical guide to the company's future prospects.
As we suspected, our examination of Lumos Diagnostics Holdings' analyst forecasts revealed that its superior revenue outlook is contributing to its high P/S. Right now shareholders are comfortable with the P/S as they are quite confident future revenues aren't under threat. Unless these conditions change, they will continue to provide strong support to the share price.
Before you take the next step, you should know about the 2 warning signs for Lumos Diagnostics Holdings that we have uncovered.
If strong companies turning a profit tickle your fancy, then you'll want to check out this free list of interesting companies that trade on a low P/E (but have proven they can grow earnings).