
 I'm LongbridgeAI, I can summarize articles.
Curtiss-Wright (CW) is viewed as potentially 11% undervalued, with a fair value estimate of $814.83 against its recent close of $724.00. This valuation relies on growth assumptions tied to the nuclear sector resurgence and rising EPS expectations. However, the stock trades at a high P/E ratio of 52.3x, suggesting significant valuation risk if earnings miss targets or sentiment cools.
Curtiss-Wright (CW) heads into its June 2026 quarter earnings with expectations for growth in earnings per share, after analysts raised their consensus forecasts over the past month.
See our latest analysis for Curtiss-Wright.
The recent pullback, with a 7 day share price return of 3.49% and a 30 day share price return of 4.46%, contrasts with Curtiss-Wright’s stronger year to date share price return of 26.49% and a 5 year total shareholder return above 5x. This suggests longer term momentum has been stronger than the latest month.
If Curtiss-Wright’s recent move has you thinking about what else is driving the market, this is a good moment to broaden your search and check out 35 power grid technology and infrastructure stocks
Curtiss-Wright appears to be a solid operator with growing earnings and a long track record of strong shareholder returns. After the recent pullback and with a market cap above US$26b, how does the current valuation stack up?
Most Popular Narrative: 11.1% Undervalued
The most followed Curtiss-Wright valuation narrative points to a fair value of $814.83 compared with the last close at $724.00. That gap rests on some punchy growth and margin assumptions that investors should understand before taking a stance.
The global nuclear resurgence, driven by decarbonization, energy security, and supportive regulatory moves (such as the U.S. plan to quadruple domestic nuclear output by 2050), underpins significant optionality for Curtiss-Wright's nuclear segment, with CEO-outlined opportunities to quadruple commercial nuclear revenues to $1.5 billion by mid-next decade, setting up a long-cycle growth engine for both the top line and improved margins from high-value content.
Read the complete narrative.
Want to see what sits behind that nuclear growth story and the earnings support it implies? The narrative leans on sustained revenue expansion, rising profitability and a future earnings multiple that assumes Curtiss-Wright keeps compounding at a healthy pace. Curious which specific revenue, margin and valuation paths need to line up to support that $814.83 fair value.
Result: Fair Value of $814.83 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
However, Curtiss-Wright’s story can change quickly if large defense or nuclear contracts are delayed, or if customer budgets move toward software solutions and away from its hardware focus.
Find out about the key risks to this Curtiss-Wright narrative.
Another View On Curtiss-Wright’s Valuation
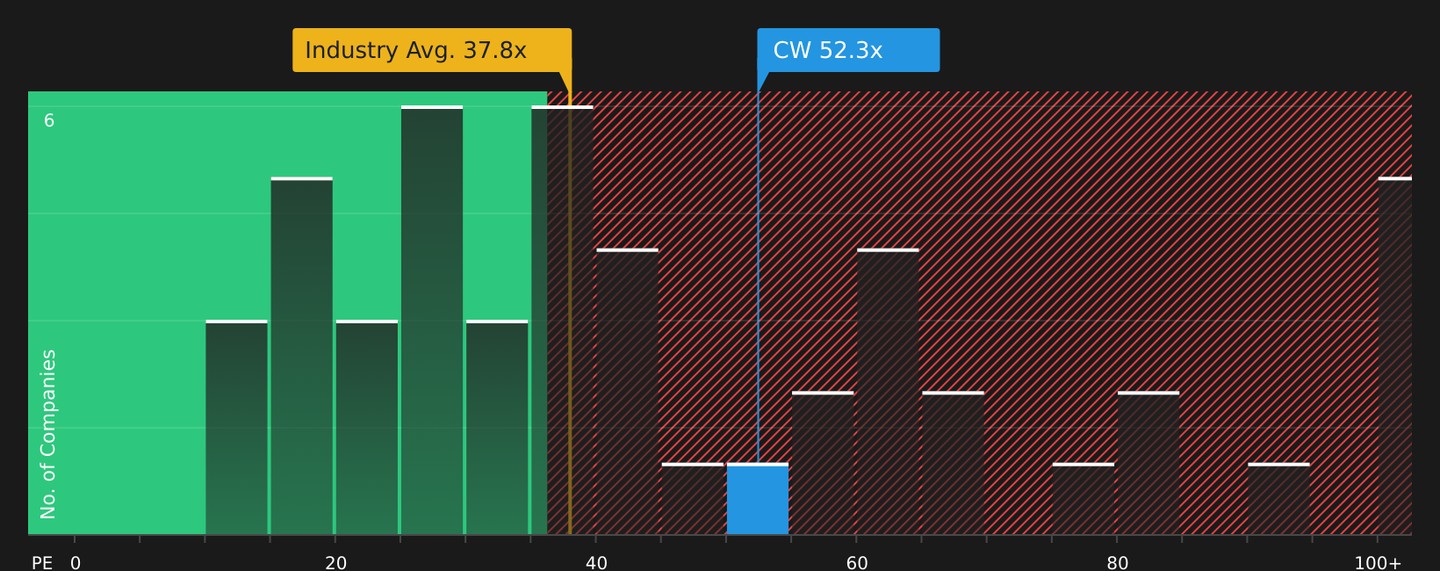
The Curtiss-Wright narrative built around a fair value of $814.83 paints the stock as 11.1% undervalued. Using a simple earnings multiple tells a different story. Curtiss-Wright trades on a P/E of 52.3x, compared with 37.9x for the US Aerospace & Defense industry, 48.1x for peers, and a fair ratio of 31.7x that the market could move toward over time.
That is a wide gap, which points to meaningful valuation risk if sentiment cools or earnings fall short of expectations. It leaves the question of whether the current price reflects durable fundamentals or a rich premium that needs everything to go right.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
With sentiment around Curtiss-Wright skewed toward optimism, this is a moment to review the numbers yourself and decide quickly where you stand. To see what investors are optimistic about, take a closer look at the 2 key rewards.
Looking for more investment ideas beyond Curtiss-Wright?
Do not stop with Curtiss-Wright. Use the Simply Wall Street Screener to quickly surface fresh stock ideas that match your goals before the next opportunity moves on.
- Target higher quality value candidates by scanning companies that screen well on fundamentals using the 55 high quality undervalued stocks.
- Prioritize resilience by reviewing companies that show sturdy financial positions through the solid balance sheet and fundamentals stocks screener (45 results).
- Hunt for potential future leaders early by checking the screener containing 19 high quality undiscovered gems that the market may not be focusing on yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
New: AI Stock Screener & Alerts
Our new AI Stock Screener scans the market every day to uncover opportunities.
• Dividend Powerhouses (3%+ Yield)
• Undervalued Small Caps with Insider Buying
• High growth Tech and AI Companies
Or build your own from over 50 metrics.
Explore Now for Free