
 I'm LongbridgeAI, I can summarize articles.
Ethan Allen Interiors (ETD) stock rose 2.8% to $22.49 following Q4 earnings, despite revenue declining 8.5% to $146.8 million and net margin compressing to 6.9%. While the company remains debt-free with $187.5 million in cash, investors are concerned about softer margins, a stretched dividend, and tariff risks. The rebound reflects resilience rather than strong growth, as bears highlight volume declines and fixed cost pressures.
Ethan Allen Interiors stock shrugged off a choppy month and closed up 2.8% at US$22.49 after earnings, even though the wider trend over the past 30 days has been weaker. The move came as investors weighed a furniture retailer reporting Q4 revenue of about US$147 million with basic earnings per share around US$0.46.
The real fault line in sentiment sits in profitability. Trailing net margin is 6.9%, lower than a year ago, and the dividend is described as not well covered. Today’s relief bid appears to reflect investors responding to resilience rather than viewing the results as a clean bill of health.
Love Ethan Allen Interiors' resilience after earnings but concerned about softer margins and a dividend that looks stretched? Check out our curated list of furniture and home related stocks with sturdier balance sheets and payout profiles in the list of solid balance sheet and fundamentals stocks (53 results).
Q4 2026 Earnings Summary
- Revenue Q4 2026: US$146.8 million vs. Q4 2025 US$160.4 million (declined 8.5%)
- Net Income Q4 2026: US$11.8 million vs. Q4 2025 US$12.3 million (declined 4.2%)
- Basic EPS Q4 2026: US$0.46 vs. Q4 2025 US$0.48 (declined 3.5%)
- Trailing Net Margin: 6.9% vs. prior year 8.4% (margin compressed by 1.5 percentage points)
Prefer clean charts instead of a dense wall of earnings tables and margin figures? Get a full visual view of Ethan Allen Interiors, with a focus on its dividend track record and sustainability, in our company report for Ethan Allen Interiors.
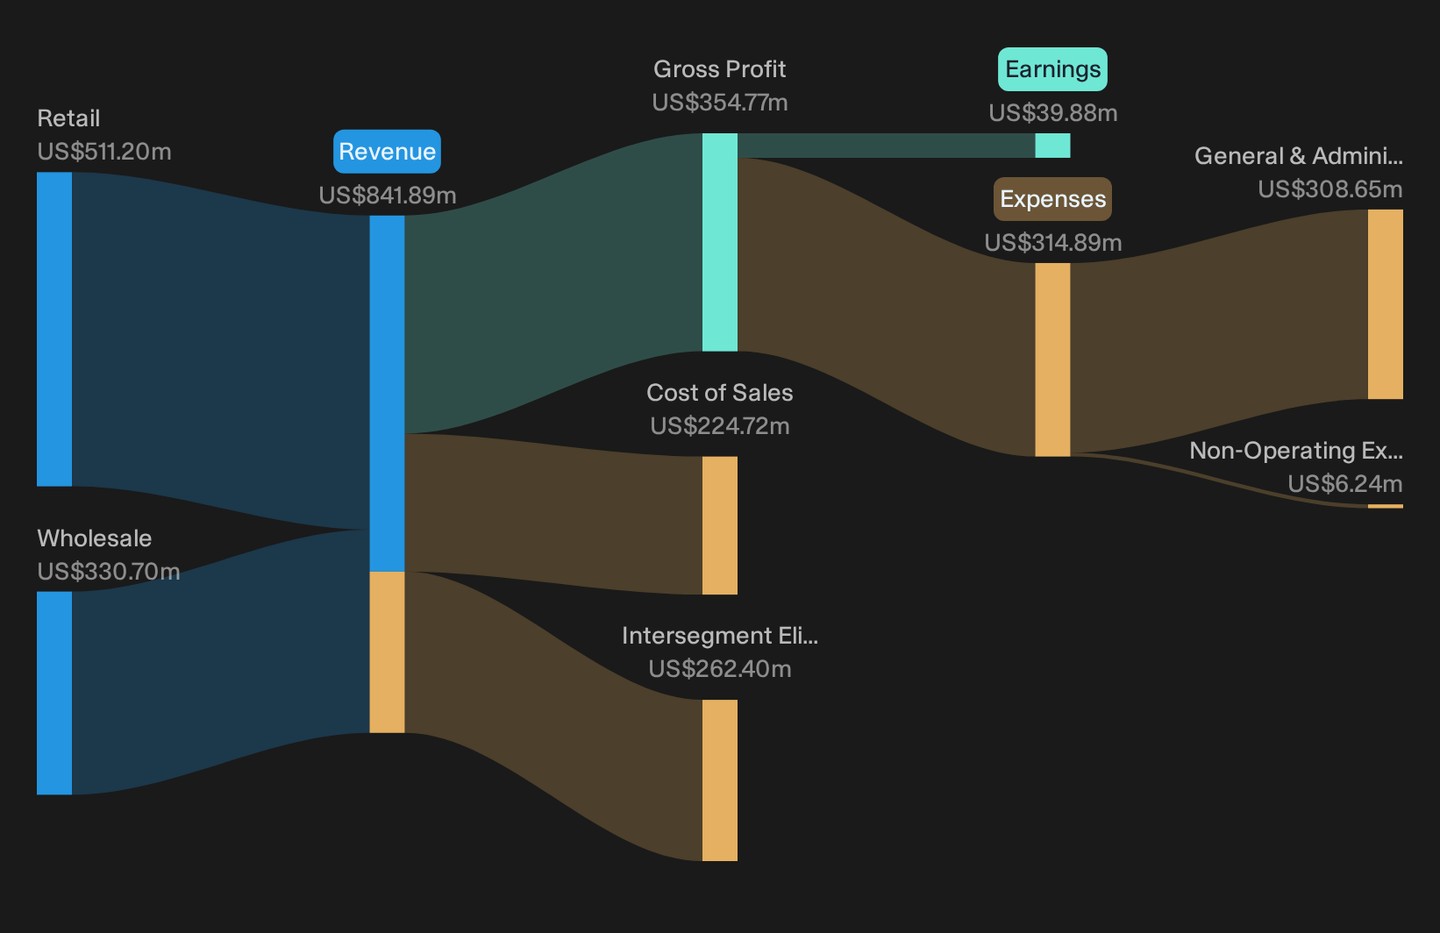
Ethan Allen bull case leans on margins and cash
Bulls argue Ethan Allen Interiors can use vertical integration and customization to keep margins and cash flow healthy even when demand softens. The latest year does support parts of that story. FY gross margin of 61.2% and Q4 adjusted gross margin of 59.7% look resilient for a furniture retailer, helped by cost discipline and headcount reduced by about 5%. The company finished FY2026 debt free with US$187.5m of cash and investments and generated US$52m of operating cash flow. Regular dividends plus a US$0.25 special payout and US$5m of buybacks show that cash is reaching shareholders. At the same time, Q4 adjusted operating margin of 7.4%, down from 9.7%, shows that fixed cost leverage is not fully offsetting weaker volume. The bull narrative on resilience is holding, but with some strain.
Bear case focuses on volume, tariffs and fixed costs
The bearish view is that Ethan Allen’s showroom heavy model and tariff exposure leave it vulnerable when volumes soften. Q4 written orders declined about 11% in both wholesale and retail, and wholesale backlog ended the year at US$44m, down 9%. That lines up with concerns about slower traffic and an aging customer base for large ticket furniture. Margin compression at the operating line from 9.7% to 7.4% reflects fixed cost deleveraging as sales eased. Tariff risk also remains real. Management estimates roughly US$15m of annual exposure across Section 232 and new Section 301 regimes. Q4 margins were supported by about US$5m of tariff refunds, which lifted gross margin by roughly 340 basis points and are unlikely to repeat at the same scale. Bears worried about structurally pressured profitability and reliance on one off items find support here.
Reveal where the surface looks calm but the multi year models start to disagree and see what the street is quietly building into revenue, margin and dividend assumptions in the analyst estimates for Ethan Allen Interiors.
Stay Ahead With Ethan Allen Interiors Insights
If Ethan Allen Interiors has your attention after its solid cash position but softer margins and dividend coverage questions, register for free with Simply Wall St and add it to your Watchlist to track price against fair value and watch for a more attractive entry point. Once you are invested, use the Portfolio Command Center to cut through noise and focus on essential updates that matter for your holdings. For a longer term view, tap into the Community to see how other investors are thinking about risks, tariffs and cash returns. By spotting hidden catalysts and potential pressure points early, you can make faster, more informed decisions and stay ahead of the market.
Seeking Fresh Alternatives Beyond Ethan Allen Interiors
New themes can break out fast while others lose momentum. Use fresh screeners to spot stocks still flying under the radar for now. Act now and get in early.
- Spot strong balance sheets before momentum is fully caught by the crowd with the curated list of solid balance sheet and fundamentals stocks (53 results) that filters for quality fundamentals and financial resilience.
- Ride potential income trends by scanning the hand picked 11 dividend fortresses that focuses on companies with high yields and solid underlying support for ongoing payouts.
- Get ahead of the next automation wave by reviewing the curated 36 robotics and automation stocks that highlights businesses tied to long term robotics and efficiency themes.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Valuation is complex, but we're here to simplify it.
Discover if Ethan Allen Interiors might be undervalued or overvalued with our detailed analysis, featuring fair value estimates, potential risks, dividends, insider trades, and its financial condition.
Access Free Analysis