
 I'm LongbridgeAI, I can summarize articles.
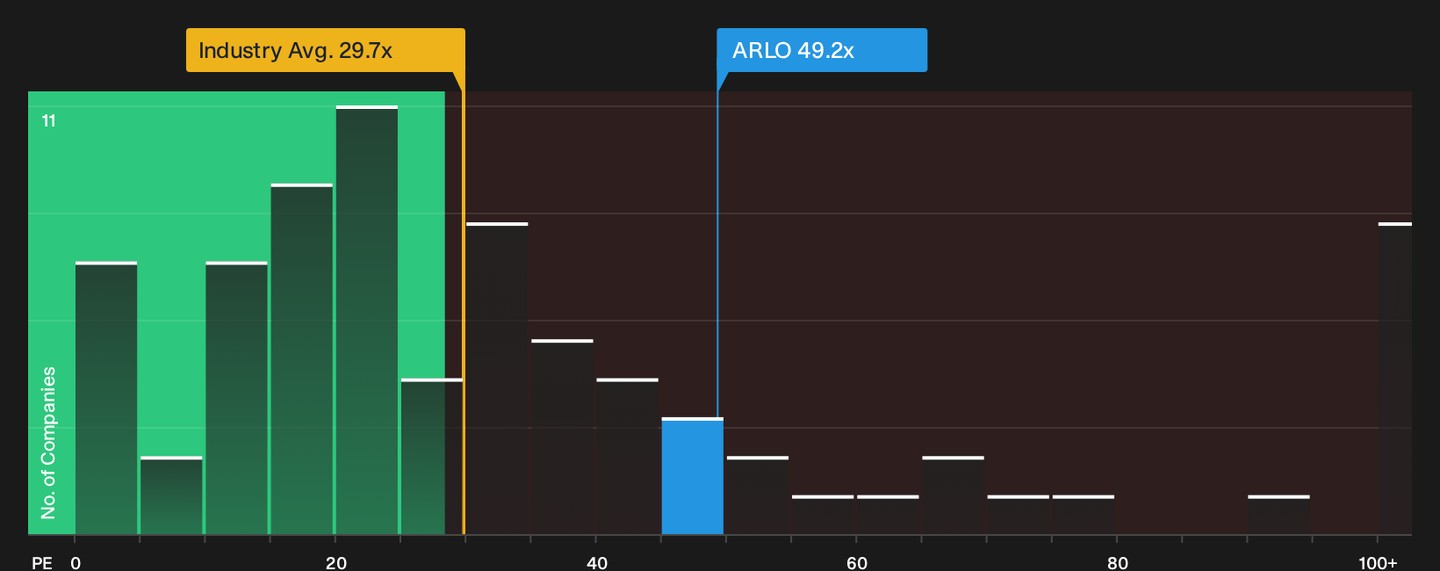
Arlo Technologies (ARLO) is viewed as potentially 35% undervalued, with a fair value estimate of $21.40 against its recent close of $13.97. This valuation hinges on improving free cash flow margins and a strategic partnership with ADT expected to boost services revenue from 2026. Despite strong long-term returns, the stock faces short-term volatility and a high P/E ratio of 49.2x compared to industry averages, presenting both growth opportunities and valuation risks.
Why Arlo Technologies Stock Is Back On Investors’ Radar
Arlo Technologies (ARLO) has drawn fresh attention after a period of revenue and earnings growth above sector averages, paired with a marked improvement in free cash flow margin that gives the business more room to fund its priorities.
Arlo Technologies’ share price has moved around in recent months, with a 9.1% 90 day share price return and a 1 year total shareholder return that is down 23%. However, over five years the total shareholder return of 121% points to meaningful longer term gains. The latest 8.4% 7 day share price return and 1 day move of 3.6% suggest renewed momentum around its improving fundamentals.
Scan Arlo Technologies alongside a curated 47 high quality undervalued stocks that also pairs improving cash generation with what our models view as attractive pricing.
Bulls see Arlo Technologies’ cash generation and growth profile supporting the recent share price move. Bears point to the weak 1 year return and volatility. The valuation numbers next show which side current evidence supports.
Most Popular Narrative: 35% Undervalued
Arlo Technologies last closed at $13.97, while the most followed narrative anchors fair value at $21.40. That gap is built on a very specific services led thesis.
The recently signed strategic partnership with ADT, North America's largest security company, with anticipated impact beginning in 2026, represents a major new channel for unlocking additional services revenue and ARR, contributing to future revenue growth and margin expansion.
Read the complete narrative. Read the complete narrative.
Want to see what sits behind that confidence in Arlo Technologies' subscription engine? The narrative leans heavily on recurring revenue, margin expansion and future earnings power. Curious which growth and profitability assumptions are doing the heavy lifting in that $21.40 fair value?
Result: Fair Value of $21.40 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
However, Arlo Technologies still faces pressure if lower hardware pricing squeezes margins or if subscription fatigue slows the shift toward higher tier recurring plans.
Find out about the key risks to this Arlo Technologies narrative.
Another View On Arlo Technologies’ Valuation
The fair value narrative for Arlo Technologies leans on future earnings power, yet the current P/E of 49.2x looks rich next to a fair ratio of 20.8x, the US Electronic industry at 29.7x, and peers at 22.9x. That premium hints at valuation risk if expectations cool. Where do you land on that trade off?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
With mixed signals across Arlo Technologies’ returns and valuation, sentiment is finely balanced, so move quickly and test the data for yourself. To see the bigger picture around both the upside potential and the issues investors are cautious about, review the 3 key rewards and 1 important warning sign
Looking For More Investment Ideas Beyond Arlo Technologies?
If you want a broader view than Arlo Technologies alone, use the Simply Wall St Screener to spot other opportunities and keep your watchlist ahead of the crowd.
- Target higher potential growth by scanning a focused 22 elite penny stocks with strong financials that filters for quality over hype.
- Sharpen your value hunt with a curated 19 high quality undiscovered gems that highlights strong fundamentals the market may be overlooking.
- Protect your downside by reviewing a 82 resilient stocks with low risk scores tailored to companies with resilient financial profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
New: Manage All Your Stock Portfolios in One Place
We've created the ultimate portfolio companion for stock investors, and it's free.
• Connect an unlimited number of Portfolios and see your total in one currency
• Be alerted to new Warning Signs or Risks via email or mobile
• Track the Fair Value of your stocks
Try a Demo Portfolio for Free