
 I'm LongbridgeAI, I can summarize articles.
A nine-year data review reveals Bitcoin's relationship with the Federal Reserve has evolved rather than decoupled. Contrary to traditional logic, a year of quantitative easing and rate cuts (Oct 2025-Sep 2026) saw BTC drop 38%, while equities rose. Correlation between M2 growth and BTC returns shifted from positive to negative (-0.766) in recent high-rate phases, indicating that liquidity expansion no longer guarantees price increases for crypto assets.
Author: Fugui
Staring at one switch for too long can make you think it's connected to all the lights. We've been watching the Federal Reserve for nine years, almost forgetting that BTC's connection has long since expanded beyond just that one line. It wasn't until I re-run the data from those nine years—2438 trading days, 62 FOMC meetings—that I discovered: it hasn't broken away from the Federal Reserve, it's just changed its connection.
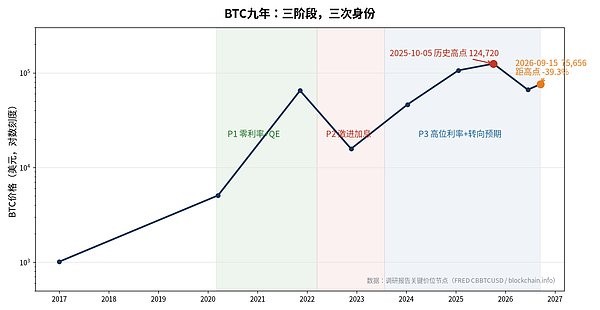
Rate hikes didn't cause a major BTC crash; a year of quantitative easing actually saw BTC drop by 38%
On September 16, 2026, the Federal Reserve held a meeting that made many people nervous.
The federal funds rate was raised by 25 basis points to 3.75% to 4.00%. This is the first rate hike in three years since July 2023. It passed unanimously, 12 to 0. This was the first policy meeting held by new Chairman Warsh, and the dot plot suggests that most officials expect another one later this year. Crypto Twitter immediately echoed with familiar slogans: "Rate hike, tightening liquidity, risk assets will fall, BTC is doomed." However, a quick look at the market revealed that BTC did not experience a typical "policy shock crash" immediately after the announcement. But this is not the most interesting part of this article. What truly deserves study is: how exactly does the Fed's policy impact on BTC price over a longer timeframe of days, weeks, or even years? If a formula works fine for nine years, but the button seems unresponsive when pressed, either the button is broken or the wiring has been altered. To clarify this, I re-run the data from January 2017 to September 15, 2026. This included 2438 trading days, 62 FOMC meetings, and used the daily closing price of BTC/USD on Coinbase via FRED for the BTC price. All macroeconomic variables came from FRED's official series, and DefiLlama data was used for stablecoins. It should be noted that the data ends on September 15, 2026; the market details for September 16 are not part of this sample and are not within the scope of this verification. The result is not "BTC is unaffected by the Fed," nor is it "BTC has completely decoupled," but rather a set of facts that are more complicated than either of these. Before elaborating on these facts, let's present a larger paradox. Before the September 16th rate hike, for a full year—from October 2025 to September 2026—the Federal Reserve did things that had absolutely nothing to do with "tightening." The formula "rate cuts and quantitative easing lead to BTC price increases" no longer applies. Consider these figures. In the 237 trading days from October 6, 2025 to September 15, 2026, the effective federal funds rate fell from 4.09% to 3.63%, a reduction of 46 basis points. The Federal Reserve's balance sheet expanded from $6.59 trillion to $6.74 trillion, an increase of $150 billion. M2 growth rose from 4.19% to 4.59% year-on-year, and net liquidity growth turned positive from -6.74% to 2.02% year-on-year. During the same period, the Nasdaq 100 rose 16.8%, and the S&P 500 rose 13.0%. Following the old script, this is called "massive quantitative easing." Quantitative easing should lead to price increases, and the more liquidity, the more dramatic the increase. BTC fell from $124,000 to $75,000 during this period, a drop of 38.2%. The money was released, the stock market rose, and ultimately, the asset that absorbed the most liquidity over the past decade actually fell by nearly 40%. This cannot be explained simply by "short-term fluctuations." In the fourth quarter of 2025, BTC fell by 26.09%, while the S&P 500 rose by 2.35%, the Nasdaq rose by 2.31%, M2 increased from 4.48% to 3.96%, the Federal Reserve's assets expanded from $6.59 trillion to $6.64 trillion, and the federal funds rate fell from 4.09% to 3.64%—a 45 basis point cut. Despite both rate cuts and balance sheet expansion, BTC simply didn't rise. More importantly, there's a reversal in the frequency of these changes. Aligning the year-on-year return of BTC with the year-on-year growth rate of M2, in phase P1 (March 2020 to March 2022, the period of zero interest rates and QE), the correlation coefficient was 0.716, a strong positive correlation. In phase P2, the period of aggressive interest rate hikes, the coefficient was 0.520, still positive. However, in phase P3, the period of high interest rates (July 2023 to the present), this number turned negative to 0.766. While M2 was expanding rapidly, BTC was actually falling. I must apply the brakes. This is not to say that liquidity is unimportant. While M2 and BTC appear highly correlated at the horizontal level, the Engle-Granger cointegration test tells us that ln(BTC) and ln(M2) have no cointegration relationship in any of the three phases, with a p-value of 0.729—two sequences with different trends happen to move together, indicating a lack of long-term equilibrium. The high R-squared value obtained from horizontal regression is a spurious regression. In terms of the year-on-year dimension that truly matches the frequency, the "quantitative easing inevitably leads to price increases" pattern is no longer a cross-cycle rule in P3. Does this mean the Fed can't control BTC anymore? It's not that they can't, it's that they're using the wrong observation window. Looking at daily yields, the relationship between interest rate changes and BTC is ridiculously weak. In the full-sample daily frequency regression, the correlation coefficient between M2 month-on-month and BTC daily yields is -0.036, with a maximum of only +0.031 across the three periods; the correlation coefficient between the Fed's balance sheet year-on-year and BTC daily yields is -0.029, not significant in any period. The correlation coefficient between the daily change in the federal funds rate and BTC daily yields is -0.001. It really looks like a decoupling. But there's the issue of observation frequency here. Looking at daily yields alone is like mixing signals from all directions into a porridge—expected rate hikes, unexpected hawkishness, unexpected dovishness, and ordinary days with no news—all added together and calculated as a correlation coefficient. Positive and negative signals dilute each other, so in the end, they appear unrelated. I isolated FOMC meeting days for event analysis. The average daily change in the 2-year Treasury yield on FOMC days was 6.34 basis points, while on non-FOMC days it was 3.89 basis points, a significant difference (p=0.0015). Instead of directly using high-frequency target/path surprise, I used the change in the 2-year Treasury yield on FOMC days as a daily proxy variable for monetary policy shocks. It's important to note that the 2-year yield, besides reflecting changes in monetary policy expectations, also includes inflation expectations, growth expectations, term premiums, press conference information, and other macroeconomic news of the day. It's a proxy variable, not a clean policy surprise. The "shock" referred to later refers to the tighter monetary policy shock characterized by this proxy variable. Then, using Jordà's (2005) local projection method, we estimate the cumulative return from the close of trading the day before the FOMC meeting to h days later for each horizon h – the monetary policy shock characterized by the 2-year interest rate. In other words, instead of asking "How much did BTC drop today after the rate hike?", we ask "What happened to BTC in the next 1, 3, 10, 20, and 30 days after a tighter monetary policy shock occurred today?" The results are completely different. According to the daily frequency definition used in this article, the cumulative BTC response on the trading day in which the FOMC occurs is close to zero. At h=0, β is -0.11%, and the t value is -0.29, statistically indistinguishable from zero. It's important to clarify a methodological limitation: the FOMC statement is released at 2:00 PM Eastern Time, while BTC trades 24/7. This article uses the daily closing price of FRED, which cannot strictly identify the high-frequency immediate reaction after the announcement—meaning that "almost no reaction at h=0" refers to no significant response within the daily event window, not a high-frequency "no market reaction at the moment of the announcement." The "Bitcoin-Macro Disconnect" mentioned by Benigno and Rosa of the New York Fed in their staff report SR1052 is based on an intraday event study, concluding that BTC does not significantly respond to macro news within the sample period. The results for h=0 under the daily frequency definition in this article are consistent with their direction, but not directly equivalent. But h is pulled back. At h=1, BTC remains almost unchanged, at -0.03%. At h=5, it's -1.43%. By h=10, the cumulative negative response reaches -2.60%, with a t-value of -1.88, showing significant marginal change. This magnitude is 3.7 times that of the Nasdaq's -0.70% and 5.8 times that of the S&P 500's -0.45%. Then at h=20, it returns to -1.22%, and at h=30, it further returns to -0.54%. It's not that there's no reaction, but rather that the reaction is slow and large. Let's look at the sub-sample after the ETFs are listed. Since the approval of spot ETFs on January 11, 2024, there have only been 21 FOMC meetings. Given the small sample size, I must clarify that these coefficients are directional evidence, not precise estimates, and the exact figures to follow cannot be overstated. However, the direction is very clear: Before the ETFs, BTC's response to the impact of tightening policies was positive but insignificant across all horizon coefficients, with h=30 even showing a positive value of 0.683, essentially immune. After the ETFs, the negative impact monotonically amplifies with maturity: h=1 is -0.182, h=3 is -0.403, h=7 is -0.687, h=14 is -0.857 (t=-2.53), and h=30 is -1.063 (t=-2.07). The 30-day effect is 5.8 times the 1-day effect. This isn't a liquidity liquidation event that caused a flash crash and immediate recovery on the announcement day; it's more like a valuation repricing—the market needs several weeks to slowly digest a tightening policy signal. The Fed isn't issuing a "price order" to BTC. It's more like throwing a stone into the financial system, with ripples spreading outwards. Bonds hear it first, then stocks, and finally BTC, but it falls the hardest. Let's rank the response times of different assets to the same tightening monetary policy shock. On the first trading day, the 10-year US Treasury yield rose significantly by 1.71 basis points, with a t-value of 2.46. It was the only asset in the entire sample to reach significance with h=1. The bond market priced in the gains first; this is the first layer in textbooks. Around the 20th trading day, roughly a month later, the Nasdaq 100 and S&P 500 reached statistical significance—the Nasdaq fell by 0.82% cumulatively (t=-2.16), and the S&P fell by 0.55% (t=-2.26). This is the second layer in the stock market. BTC reached its peak response at h=10, with a magnitude of -2.60%. Its response time fell between the bond and stock markets, but the magnitude was magnified several times. What about the US Dollar Index? The absolute value of the t-value for all eight horizons from h=0 to h=30 was less than 1, with a maximum of only 0.97, never showing significant values. To illustrate, imagine a shopping mall suddenly losing power. The first to know is the electrical room; the power is cut off, and the monitoring system immediately alarms. Then it's the shops on each floor; as soon as the lights go out, people start to panic. Finally, it's the people in the parking lot preparing to leave—the news travels slowly, but the stampede is most severe when they crowd at the exit. BTC is somewhat like that parking lot. It wasn't the first to receive the news, but the final stampede is the most severe. An exploratory Baron-Kenny mediation analysis also provides clues in the same direction. At h=0, the Nasdaq is the only significant candidate mediator, with a t-value of 2.35 and a p-value of 0.022. After controlling for the Nasdaq, the direct effect of the policy shock proxies on BTC decreased from -0.107 to -0.071, a decrease of 34%. The US dollar as a mediator is not significant, with a t-value of -1.63 and a p-value of 0.109, even in the opposite direction to expectations. This only indicates that the statistical relationship in the same period is compatible with the "equity market channel," and cannot prove a causal transmission chain on its own. Mediation analysis here is affected by issues such as contemporaneous correlation, omitted variables, and measurement errors, and can only serve as a directional reference. The US dollar and BTC often move in opposite directions, but the Federal Reserve doesn't rely on the dollar to communicate. A widely circulated chart in the crypto community shows that when the Fed raises interest rates, the US dollar index (DXY) rises, and BTC falls. The chain is simple and looks straightforward. However, two different questions need to be clarified here. The first question is, "Do the US dollar and BTC often move in opposite directions?" The answer is yes, and it's one of the most stable and simple macroeconomic relationships across cycles. The daily correlation coefficient for the full sample is -0.197, with three phases showing -0.236, -0.281, and -0.097 respectively, all significant. Regardless of the QE period, the interest rate hike period, or the current high level, a strong dollar has been suppressing BTC; only the magnitude of the pressure varies. The second question is whether the Federal Reserve transmitted policy shocks to BTC through the dollar. This cannot be supported within the event study framework. As mentioned earlier, the DXY's response to tighter monetary policy shocks was insignificant across all horizons within 30 days after the FOMC – the Fed threw a tighter stone, but the dollar index barely rippled. There's a more subtle reversal in the intermediary analysis, worth discussing separately. Before the ETF listing, the Fed's influence on BTC mainly relied on the dollar. Tighter policy shocks pushed up the DXY (a=+4.29, t=4.87), while a strong dollar suppressed BTC (b=-0.035, t=-3.60), resulting in an indirect effect of -0.152. During the same period, the US stock market channel was completely cut off – Fed shocks did not affect the Nasdaq within the event window, and the Nasdaq did not predict BTC. After the ETF was listed, this leg broke. The shock of tighter policies still pushed up the DXY (a=+3.73, t=2.46) and the real interest rate (a=+0.296, t=2.70), and the Fed's influence on traditional macroeconomic variables remained unchanged. However, the marginal effect of DXY on BTC dropped from -0.035 to -0.002, almost to zero, and the indirect effect shrank to -0.007. At the same time, the direct channel from the Fed to BTC opened, with a total effect of -0.182 and a p-value of 0.054—there is a direct channel that does not go through the dollar, the Nasdaq, or the real interest rate. "The dollar and BTC often move in opposite directions" is a fact. "The Fed transmits shocks to BTC through the dollar" no longer holds true after the ETF. These two statements are not contradictory. What really changed after the ETF? Everyone thought the ETF would send BTC to Wall Street, turning it into a more standard tech stock. The data tells a more complex story. First, let's be honest about something. If we regress the daily return of BTC against the daily return of the S&P 500, and perform a Chow structure test with January 11, 2024 (the ETF's listing date) as the breakpoint, the F-value is 1.51, and the p-value is 0.221—strictly speaking, it fails to reject the null hypothesis of "structural stability." Both β estimates are noisy: β before ETF = -0.130 (t = -1.41), β after ETF = +0.178 (t = 1.45), neither of which is significant. The statement "β decreased from 0.789 to 0.417, a 47% decrease, which is statistically significant" cannot be directly applied to the S&P 500. Applying the same test to the Nasdaq 100, the interaction term regression shows that β decreased from 0.789 to 0.417, with an interaction term t-value of -2.70 and a p-value of 0.0071; the Chow F-value is 3.944, and the p-value is 0.0195, which is statistically significant. However, it's important to note that the Nasdaq 100's sample starting point is different, and its beta is highly non-monotonic year by year—the beta was -0.371 in 2019, peaked at 1.176 during the aggressive interest rate hike period in 2022, fell back to 0.481 in 2023, briefly dropped to almost zero at 0.005 in 2025, and then returned to 0.805 in 2026. This isn't a step-like change where beta "jumps down as soon as the ETF goes up." The truly statistically stable structural changes are the following three: First, a systematic reduction in volatility. BTC's annualized volatility dropped from 75.1% before the ETF to 48.5% after, a decrease of approximately 35%. This is the most solid figure, with no controversy regarding its direction and magnitude. With less retail investor noise, pricing is becoming more normalized. Second, the one-day leading effect of US stocks on BTC has strengthened. Cross-correlation functions show that the predictive power of the previous trading day's S&P 500 return on the current day's BTC return increased from 0.255 before the ETF to 0.379 after the ETF, with a stable peak of lag=+1. This corroborates Mohamad's (2025) finding at a 5-minute frequency that "ETFs dominate BTC price discovery approximately 85% of the time"—the US stock market has higher price discovery efficiency, with macroeconomic information first priced in US stocks and then transmitted to BTC through the ETF funding channel. Third, the 90-day rolling mean correlation between BTC and S&P 500 systematically increased from 0.002 before the ETF to 0.062 after the ETF, with a Welch t-value of -11.14 and a p-value less than 0.001. While the correlation has indeed increased statistically, the increase is far from enough to make "BTC become like the Nasdaq." Looking at these three changes together, the direction is consistent: after institutional entry, information flow between BTC and US stocks has accelerated, price discovery is more synchronized, and purely speculative noise has decreased. However, this does not mean that BTC has become a high-beta tech stock, nor does it mean that the Nasdaq can explain most of BTC's volatility—the R² of the Nasdaq 100 single-factor regression after ETFs is only 0.035, and the Nasdaq can explain less than 4% of BTC volatility. There is also something contrary to the intuition that "BTC is becoming more like a stock." As mentioned earlier, after the introduction of ETFs, BTC's negative response to the shocks of tighter monetary policy began to accumulate over a 2- to 4-week timeframe, with a 30-day beta of -1.063—its sensitivity to macroeconomic policy signals shifted from "basic immunity" to "delayed but continuous repricing." These two things can happen simultaneously. BTC can be more sensitive to shocks from the Federal Reserve, but unlike the Nasdaq, it doesn't instantly price in the impact of the FOMC announcement. This is because macroeconomic sensitivity and stock beta are fundamentally different. The former concerns whether "policy shocks will ultimately be reflected in prices," while the latter concerns how synchronized BTC's daily price movements are with the Nasdaq. After the introduction of ETFs, the former is accumulating, while the latter is decreasing. It's not that the Federal Reserve is leading BTC; often, BTC is the one that first senses the danger. When conducting Granger causality tests, I encountered the most unexpected set of figures in the entire study. Using Granger causality analysis with a 5-period lag for daily yields, in period P1 (March 2020 to March 2022, the period of zero interest rates and QE), the statistically significant trend is that BTC leads macroeconomic variables, not the other way around. BTC leads the S&P 500 by 0.0015; BTC leads the VIX by 0.0001; BTC leads the US Dollar Index by 0.018; and BTC leads the 10-year real interest rate by less than 0.0001. The Nasdaq shows a bidirectional trend in P1, with a p-value of 0.012 from BTC to the Nasdaq and 0.042 from the Nasdaq to BTC. In period P3 (July 2023 to the present), this trend has once again overwhelmingly emerged. BTC outperforms the S&P 500 by a p-value less than 0.0001; BTC outperforms the Nasdaq 100 by a p-value less than 0.0001; BTC outperforms the VIX by a p-value less than 0.0001. The direction of macroeconomic variables towards BTC is insignificant throughout this period. Only in P2, during the period of aggressive interest rate hikes from March 2022 to July 2023, did a true "macroeconomic variable leading BTC" occur—the p-value for 10-year US Treasury yield towards BTC was 0.0089; the p-value for 10-year real interest rate towards BTC was 0.049. This is the only time in the entire sample that BTC was led by interest rates. Granger causality isn't economic causality; it refers to the predictive lead time—whether the historical value of X can help predict the future value of Y, providing more information than just looking at Y's own history. Moreover, some of this lead may stem from BTC's 24/7 trading, while US stock and bond markets are only open during weekdays. Events in Asia and over the weekend are priced into BTC first, followed by the US stock market. This mechanical lead due to the trading time difference exists, and co-shocks (two markets simultaneously reacting to an unobserved third factor) cannot be ruled out by the Granger test. However, even with these points clarified, the results still overturn a popular narrative. Most analysts rely on the Federal Reserve and liquidity data to predict BTC. Data shows that, except for the period of aggressive interest rate hikes in 2022, the statistical basis for this "macroeconomic prediction of BTC" is weak. Conversely, BTC price changes often statistically precede changes in macroeconomic sentiment indicators such as the VIX, S&P 500, and Nasdaq. It's more like a canary that might sing ahead of time—if the gas concentration in the mining pit rises slightly, it might veer off course first. However, this "ahead of time" refers to statistical prediction, not that BTC actually "sees" the future, nor can it rule out the leading effect caused by joint shocks and the 24/7 trading structure. By the time traditional indicators sound the alarm, sometimes it's already too late, and sometimes it's just BTC's own noise. This does not contradict the earlier statement that "BTC is the last layer of the transmission chain." These two points address different dimensions: In the FOMC event window, identifying causal shocks, BTC did indeed complete its repricing after the bond and stock markets; however, in everyday timelines without significant policy events, BTC, due to its 24/7 trading and emotional sensitivity, actually priced in implicit risks before traditional markets. One is "how policy shocks are transmitted," and the other is "who perceives risk appetite first." A portion of the money in BTC is already in cryptocurrencies. Earlier, it was mentioned that no cointegration relationship was found between M2 and BTC in any of the three phases, with a p-value of 0.729. Applying the same test to stablecoins yields completely different statistical results. The Engle-Granger cointegration test statistic for ln(BTC) and ln(total stablecoin market capitalization) is -4.160, with a p-value of 0.0042—a statistically long-term equilibrium relationship exists between the two. This means that there may be a more stable long-term co-movement between stablecoins and BTC than M2, but it is still not proof of causation. Cointegration may stem from shared market size growth, Crypto ecosystem expansion, and adoption trends, but it cannot be used to conclude that "stablecoins drive BTC." The year-on-year changes are steeper. The year-on-year correlation between stablecoins and BTC: -0.007 in 2024, almost zero correlation; rose to 0.312 in 2025; 0.743 in 2026; and reached 0.891 in the most recent year-on-year rolling correlation. Meanwhile, the year-on-year correlation between M2 and BTC at P3 during the same period was -0.766—two liquidity indicators, one traditional M2, and one Crypto's own stablecoin, gave completely opposite signals. Cointegration tests the stablecoin aspect. I must also clarify the other side, and not just focus on the attractive numbers. On a weekly basis, the relationship between stablecoins and BTC is weak and unstable. The correlation coefficient between weekly stablecoin changes and weekly BTC returns is only -0.093. Granger causality at the weekly level shows a p-value of 0.0569 for stablecoins to BTC, which is not significant. Lead-lag scans show a correlation of 0.201 when leading by -5 weeks, indicating that BTC actually leads stablecoins. The correlation coefficient between 30-day stablecoin growth and daily BTC returns is only -0.033—Oefele (2025)'s research also found that ETF fund flows are a result of price rather than a cause; funds only enter after prices rise, showing a clear reverse causality. This means that stablecoins are not a short-term trading signal. One cannot judge whether BTC will rise or fall tomorrow simply by looking at how much stablecoins have been issued today. It is more like a slow variable, determining the valuation center rather than intraday fluctuations. What truly provides information is state-dependent regression. I grouped the samples according to the growth rate of stablecoins. When stablecoins are in a state of high expansion, the beta of BTC and the S&P 500 is -0.220, and the t-value is -2.10, showing a significant negative correlation—BTC in this state will move inversely to the US stock market, exhibiting its own independent trend. When stablecoin growth stagnates, BTC weakly and positively follows the US stock market (β=+0.082, not significant). This is the core concept of the entire text. BTC currently faces two liquidity systems simultaneously. One is the liquidity of traditional finance—Federal Reserve interest rates, M2, the US dollar, and US stock market risk appetite. This system influences BTC through ETF funding channels and institutional cross-asset allocation. The other is Crypto's own liquidity—the expansion and contraction of stablecoins, the inflow and outflow of on-chain funds, and the risk appetite within Crypto itself. This system circulates independently outside the traditional system. The paradox from October 2025 to September 2026 finally found a resolution. Money was released, but it was the Federal Reserve's money; when BTC fell, the total market capitalization of stablecoins did not shrink in tandem, but instead continued to expand—from over 300 billion to over 310 billion, setting a new historical high. This at least shows that the decline in BTC price did not accompany the simultaneous disappearance of Crypto-USD liquidity, and the rhythm of traditional liquidity and internal Crypto liquidity may have diverged. However, this cannot be simply interpreted as "money not leaving Crypto"—stablecoins can remain in on-chain wallets, on exchanges, in DeFi, in RWA bonds, idle, held by arbitrage institutions, or transferred internally within institutions. The expansion of the total market capitalization of stablecoins only indicates that the supply of stablecoins did not shrink in tandem, not that all funds are waiting to buy BTC. BIS working paper WP1219 found that stablecoin market capitalization decreases and money market fund AUM increases after tightening, moving in the opposite direction to traditional liquidity. This suggests that stablecoins' response to monetary policy is inherently slow and cumulative, not something that can be seen within the 30-day event window following the FOMC. So what exactly is BTC? It's not digital gold. During the 5% of trading days with the most dramatic VIX jumps, BTC's average return was negative across all three phases, with a more than two-thirds probability of falling. During the P2 aggressive rate hike period, it had an 88.9% probability of falling along with the VIX, averaging a 5.67% drop. When panic hits, it doesn't act as a safe haven; it falls along with the VIX, and often more sharply. It's not another Nasdaq either. After the ETF, the Nasdaq 100 single factor can only explain 3.5% of BTC volatility, and in the first quarter of 2025, BTC and the Nasdaq even showed a significant negative correlation (β = -0.377, t = -2.47). More accurately, it has four faces, and which face is revealed depends on the current situation. When faced with a tightening policy shock from the FOMC, it acts as a macro risk asset. After the ETF, the tightening policy signals will continue to cumulatively suppress its price over the next few weeks, with a 30-day cumulative effect of about 1%. However, unlike the Nasdaq, it doesn't complete pricing within half an hour; instead, it takes several weeks for a slow revaluation. When faced with extreme market panic and a surge in the VIX, it acts as a high-beta amplifier. During the worst 5% of the S&P 500's decline in Phase 2, BTC's drop was 2.69 times that of the S&P 500 itself; its left-tail quantile reversion beta was 2.391, 2.2 times that of the median beta. It followed the decline most closely and experienced the most significant drop. When on-chain stablecoins experienced rapid expansion, it was an intrinsic asset of Crypto, decoupled from US stocks, with a negative beta of 0.220, and moved in its own direction. At this time, traditional macroeconomic analysis frameworks became largely ineffective. In normal times without significant policy shocks, it occasionally acted as a canary in the coal mine of global risk appetite—its 24/7 pricing allowed it to react to implicit risks ahead of US stocks and VIX in many situations, especially during QE and Phase 3, where Granger's leading performance was significant. The four faces (of interest rates) are not mutually exclusive; they coexist. Which one is lit up at any given moment depends on volatility, trend, stablecoin status, and whether it's FOMC week—a host of state variables determine this. Therefore, when you see statements like "The Fed cut rates, BTC will rise," it's best to ask yourself three questions first. First, has this rate cut already been priced in by the market, and what direction will the unexpected part take? Second, what is the current state of traditional assets—has the bond market moved? Has the stock market moved? Where is the VIX? Third, what is happening in Crypto's own liquidity pool—is the stablecoin expanding or contracting, and is on-chain sentiment hot or cold? Building a four-layered observation framework is far more useful than staring at a single interest rate button: a tighter monetary policy signal first affects bonds and real interest rates, then stock risk appetite, then the direction of internal Crypto liquidity, and finally, it impacts BTC. Each layer has the potential to block, delay, or even reverse the trend. The question is wrong. For the past few years, everyone has been asking: Is BTC a macro asset? The question itself is flawed. The real question should be: Under what circumstances is BTC an asset? During the QE in 2020, it could act as a liquidity-driven risk asset, positively correlated with M2 growth by 0.716, rising along with the monetary easing. During the aggressive interest rate hikes in 2022, it became a high-beta risk asset, correlated with the Nasdaq by 0.506, driven by interest rates, with the 10-year yield and real interest rate Granger outperforming it. After the ETF was listed in 2024, its pricing microstructure changed, information flow became faster, and volatility decreased. However, it did not become like the Nasdaq; instead, it was significantly negatively correlated with the Nasdaq in 2025. By 2026, Crypto's internal stablecoin liquidity had established a cointegration relationship with it, with a year-on-year correlation of 0.743, and external macro Beta and internal funding Beta began to move in parallel. The reason why the interest rate hike on September 16th did not result in a typical policy-shock-driven flash crash was not because BTC was detached from macroeconomics—according to the data in this article, BTC's typical reaction pattern is not "a drop on the day of the FOMC meeting." If a real response occurs, it will gradually emerge over the following two weeks to a month (current sample data suggests this is the case). More importantly, a full year before the rate hike, the market had just taught everyone a lesson with a 38% drop: the simple formula of "quantitative easing inevitably leads to a rise" no longer works. The script on September 16th didn't follow the old version; in fact, the old version had already become obsolete a year ago. BTC's Beta is a variable. It's not a constant, not a fixed label, and not a one-way trend that "increasingly resembles the US stock market." It's a function of VIX, a function of its own trend, a function of the stablecoin's state, and a function of institutional breakpoints. Methodologically, I didn't just calculate simple correlations. Event research, local projection, Chow structural breakpoints, Baron-Kenny mediation analysis, Granger causality, cointegration tests, state-dependent grouping, quantile regression, cross-correlation functions—I did everything I was supposed to. The policy shock analysis uses the daily change in the 2-year US Treasury yield on FOMC day as a daily proxy variable, not the target/path factor of high-frequency USMPD. Therefore, it may contain non-pure policy components such as inflation expectations, term premiums, and press conference information. The FOMC statement is released at 2:00 PM Eastern Time, while BTC trades 24/7, making it impossible to strictly identify high-frequency immediate reactions after the announcement using daily data. There have only been 21 FOMC meetings since ETFs, resulting in low subsample freedom. Daily ETF flows and derivative leverage data are unavailable. Intermediation analysis can only indicate the direction of statistical relationships during the same period, not identify causal transmission chains independently. Cointegration does not represent causation. Granger leading does not equate to "seeing the future." These limitations must be stated upfront. Therefore, this article is not about "proving what BTC has become," but rather about how nine years of data tells us one thing: the old, single-threaded macroeconomic formula for BTC can no longer explain current realities. The real difficulty has never been predicting whether the Fed will raise or lower interest rates next. The real challenge lies in predicting how BTC will react to the next macroeconomic shock—will it be the last one in the parking lot to know the news but suffer the most, the canary that might sing ahead of time, or an independent force propped up by stablecoin expansion, completely ignoring what the Fed is saying? Understanding which one it is right now is far more useful than simply remembering the saying "interest rate hikes cause a drop, interest rate cuts cause a rise."