
 I'm LongbridgeAI. Here is the key information I extracted
Multiple bearish factors converged on a single day, triggering the most severe single-day sell-off in the US Treasury market in nearly 18 months.
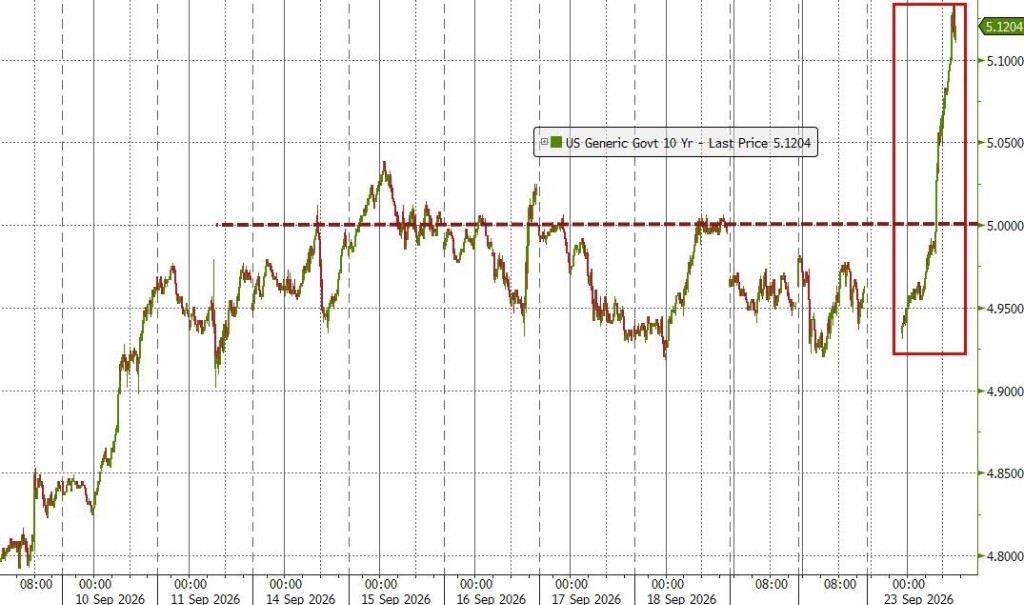
The 10-Year Treasury Yield surged approximately 14 basis points on Wednesday, closing at 5.113%, a new high since 2007, marking its largest single-day increase since the shock of former President Trump's so-called "Reciprocal Tariff Day" last April. Market participants described this move as a "perfect storm"—strong PMI data, escalating tensions in the Middle East, hawkish remarks from Federal Reserve officials, and weak Treasury auction results—four blows landing consecutively within the same trading session.
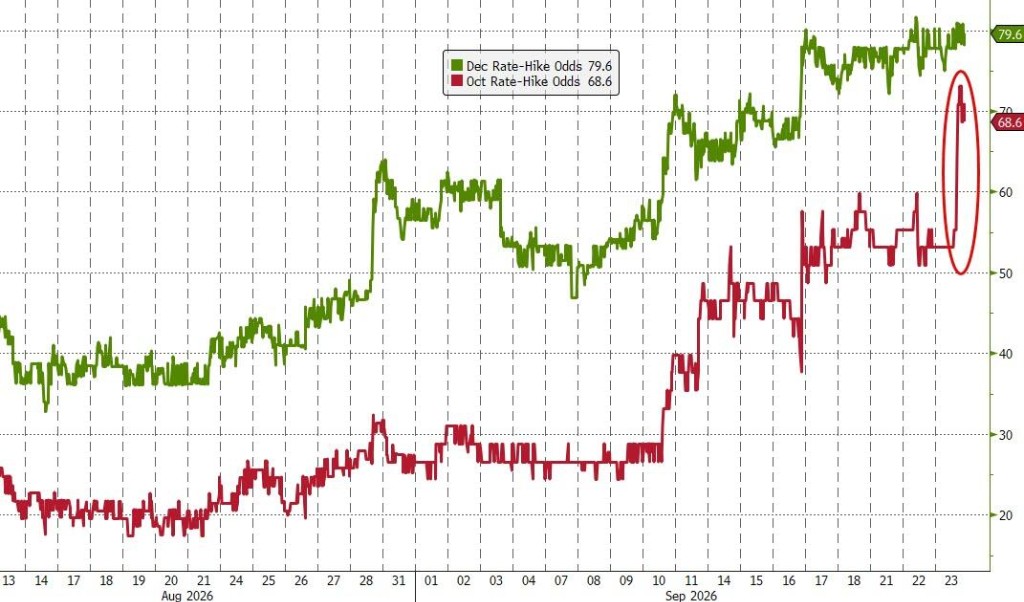
The core signal of this shock is that market bets on another Fed rate hike in October have intensified sharply. Futures markets are currently pricing in a 68% probability of a rate hike by the end of October, just days before the US midterm elections. Meanwhile, swap markets have fully priced in expectations of three 25-basis-point rate hikes over the next year, with significant hedging against a fourth hike. If all materialize, the federal funds rate target range would rise to 4.75%–5%.
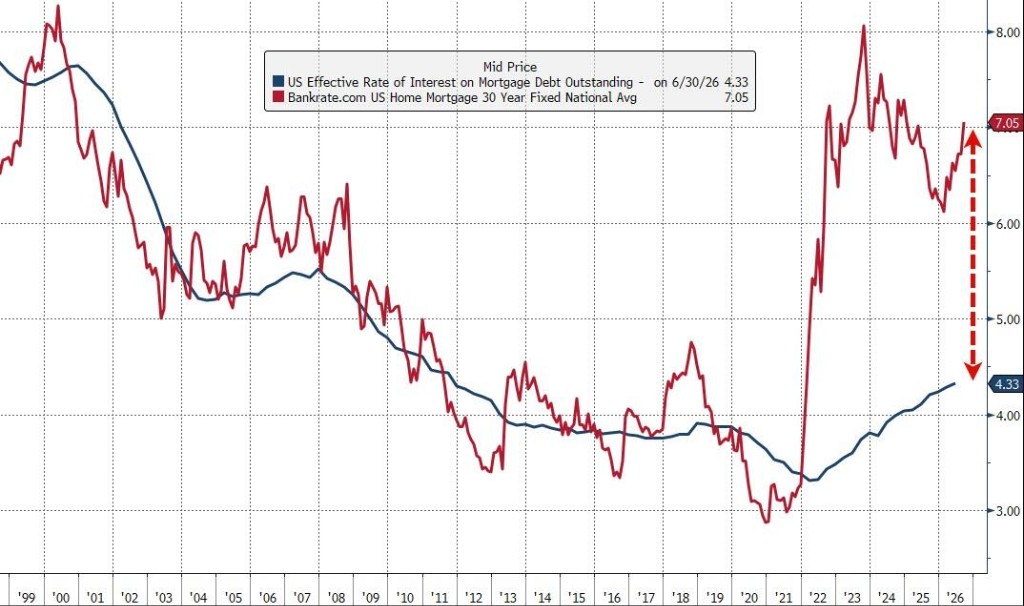
At the same time, the continuous rise in yields is transmitting to the real economy. The 30-year mortgage rate has exceeded 7%, increasing pressure on sectors reliant on debt financing, such as private equity. The Treasury buyback program launched by Treasury Secretary Bessent failed to effectively curb the selling momentum, indicating a clear lack of market confidence.
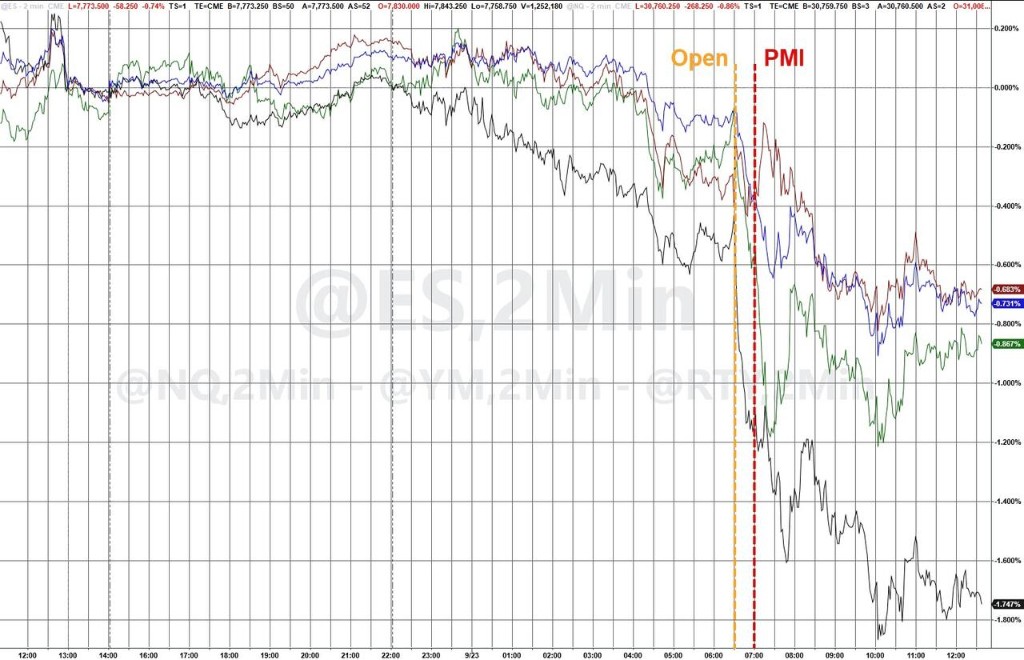
Equities also declined synchronously, though the drop was relatively mild—the S&P 500 Index closed down about 0.8%, the Nasdaq Composite fell 1.1%, and the Dow Jones Industrial Average dropped approximately 352 points.
Four Blows Land Consecutively, Forming a "Perfect Storm"
Wednesday's bond market rout was not caused by a single event but by the superimposed resonance of multiple bearish factors on the same trading day.
First Blow: Oil prices soar as hopes for Middle East diplomacy fade. During early trading in Europe, international oil prices surged. The market had previously hoped that the UN General Assembly, currently held in New York, would help ease US-Iran relations. However, statements by Iranian President Masoud Pezeshkian dashed these expectations—he stated that Iran is willing to negotiate but will not accept Trump's "bullying," warning that as long as sanctions remain, Iran will not fully open the Strait of Hormuz. Brent crude, the international oil benchmark, closed up nearly 4%. Due to the potential for sustained oil price increases to feed into broader inflation, bond yields have been highly correlated with oil price trends in recent months.
Second Blow: PMI data exceeds expectations, intensifying fears of economic overheating. S&P Global released the preliminary US Composite PMI report for September, showing that US business activity expanded at its fastest pace in over five years, with job growth reaching its quickest rate in more than four years.
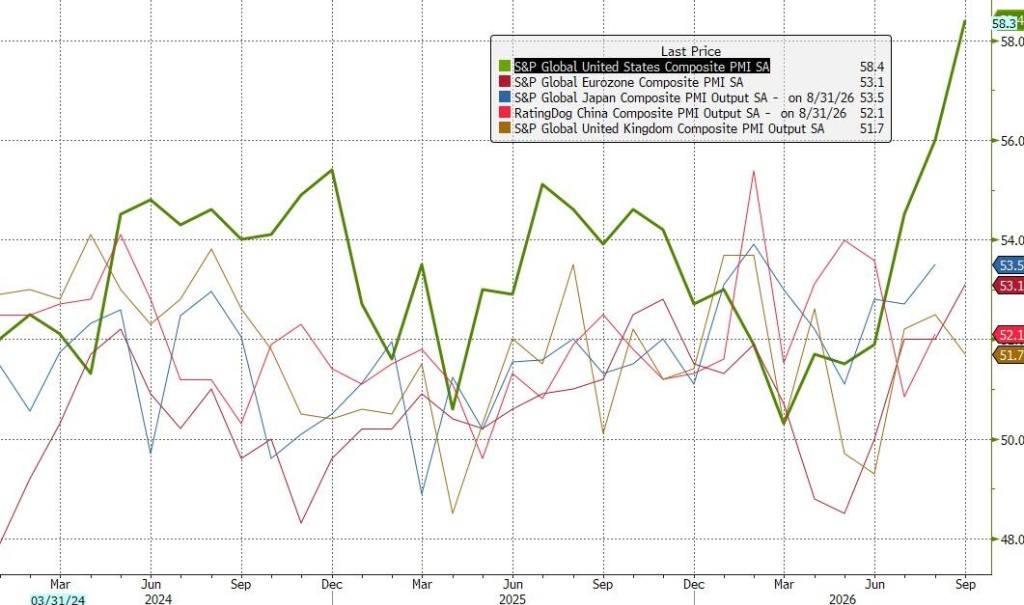
Chris Williamson, Chief Business Economist at S&P Global, stated, "Excluding the demand rebound after the end of pandemic lockdowns, this improvement in business activity is the largest since early 2015." Following the data release, both short-end and long-end Treasury yields jumped.
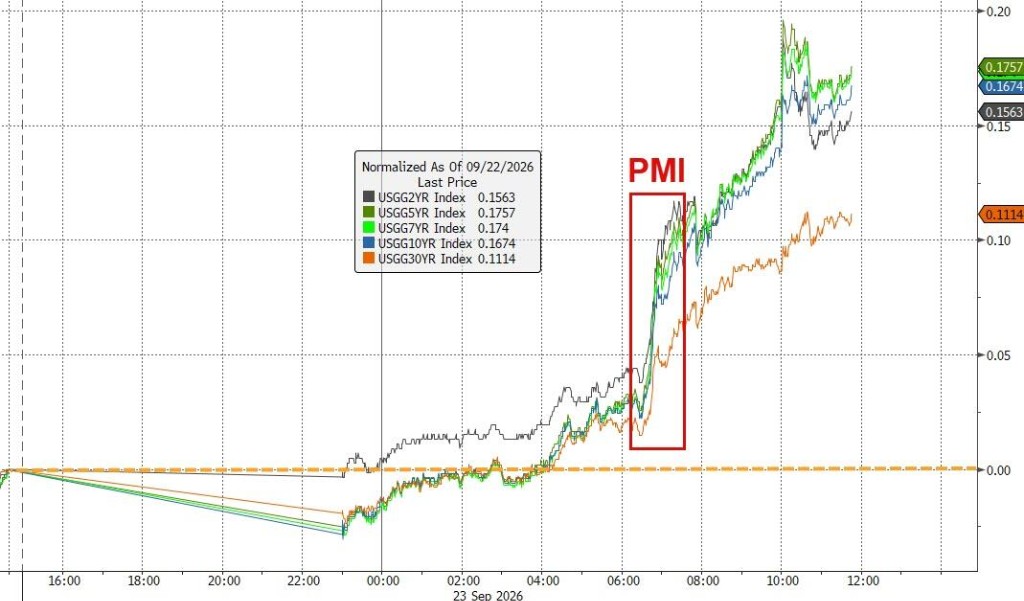
Third Blow: Fed officials strike a hawkish tone. Federal Reserve Governor Michael Barr spoke in Chicago, clearly stating that "inflation is above the 2% target, and there is no clear trend toward converging on the target," adding that "in my baseline scenario, further policy adjustments may be needed to ensure inflation returns to the target level in a timely manner." Dhiraj Narula, US Rates Strategist at HSBC, pointed out that the market is worried that "the Fed is willing to continue raising rates despite pressures from supply shocks, implying that the hawkish stance may remain unyielding."
Fourth Blow: Tepid 5-year Treasury auction accelerates panic. The US Treasury's $70 billion 5-year note auction met with a cold reception. The winning yield was 5.033%, about 3 basis points higher than pre-auction trading levels—a significant premium in this large market that typically absorbs supply smoothly. Primary dealers were forced to take an unusually large proportion of the bonds, the highest since 2024, indicating scant interest from other potential buyers. After the auction results were announced, yields rose further, and panic spread.
Yields Break Key Levels Across the Curve, Hitting Multi-Year Highs
The intensity of this sell-off is evident in the data.
The 10-Year Treasury Yield closed at 5.113%, standing above 5% for the first time since 2007, with a single-day increase of about 14 basis points. This was the largest single-day jump since the shock of Trump's so-called "Reciprocal Tariff Day" last April, constituting an extreme volatility event of approximately 4 standard deviations—just two weeks prior, the market had experienced a 3-standard-deviation shock, putting pressure on Value-at-Risk (VaR) models across various risk books.
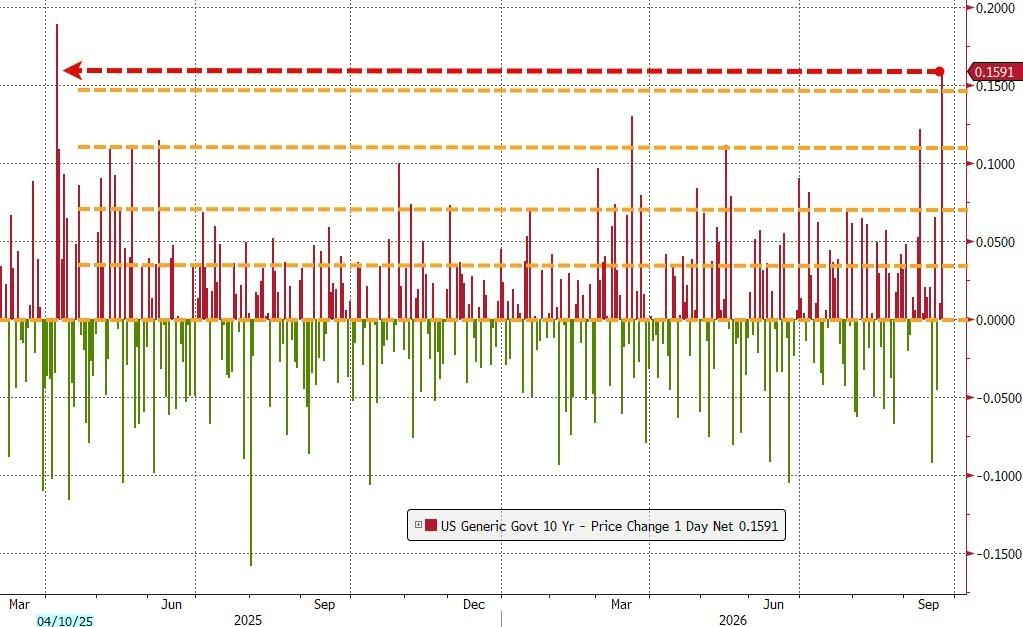
The 5-year yield surged nearly 20 basis points in a single day, breaking above 5% for the first time since 2007, with the failed auction further accelerating this trend.
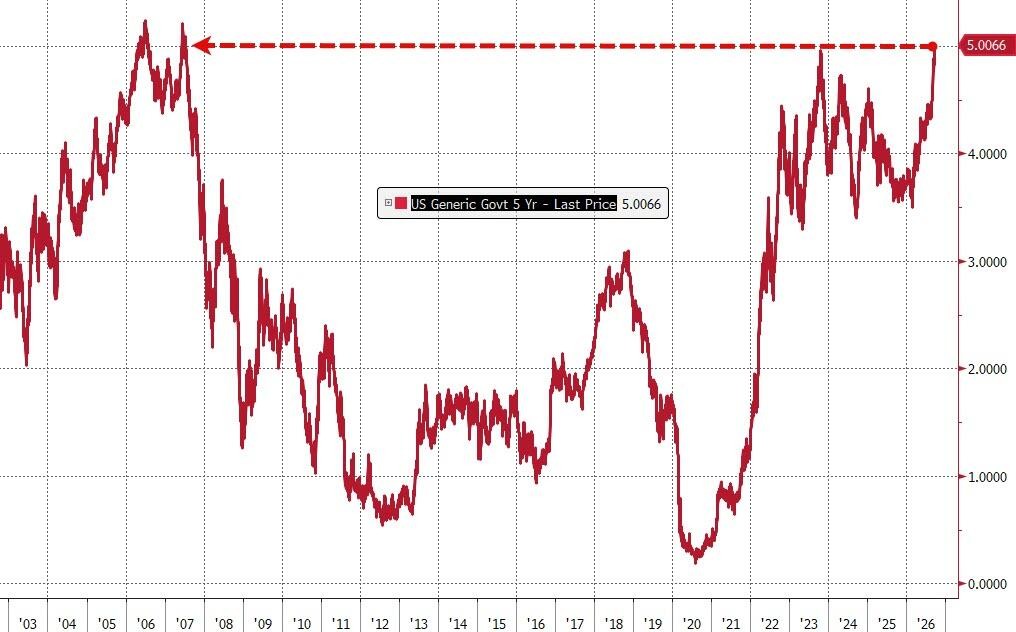
The 30-year yield rose to its highest level since 2004. The 2-year yield briefly hit its highest level since 2024 before falling slightly to 4.90%, up 12 basis points from the previous day.
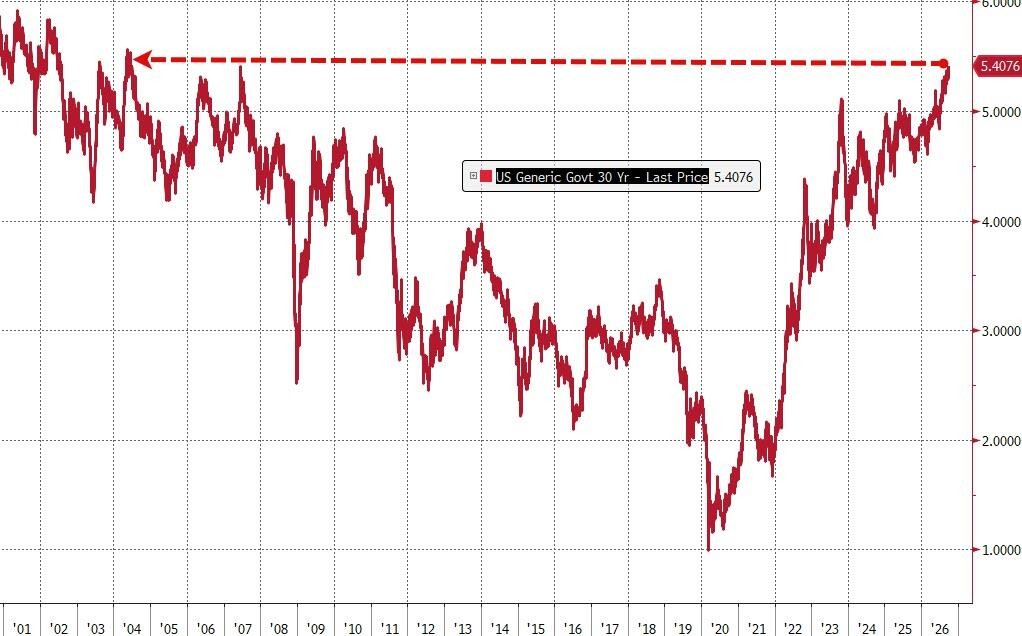
Bond volatility indicators also jumped significantly, indicating a serious lack of confidence in the market's future direction. Sean Simko, Head of Fixed Income Investment Management at SEI Investments, summarized the day's situation as a "triple blow":
"Stronger economic data, supply pressure pushing 5-year yields to levels unseen in years, and judgments on the stickiness of global inflation."
Essence of the Sell-off: Repricing of Real Rates, Not Just Inflation Panic
Notably, the driving logic behind this bond market sell-off was not simply rising inflation expectations.
According to Bloomberg analysis, approximately 80% to 85% of the sell-off magnitude came from rising real rates: the nominal 10-year yield rose by about 15 basis points, the 10-year Treasury Inflation-Protected Securities (TIPS) yield rose by about 12.5 basis points, while the breakeven inflation rate increased by only about 2 basis points.
This means bond investors are repricing for some combination of the following factors: a Fed path of keeping rates higher for longer, stronger real growth expectations, a higher neutral rate, higher real term premiums or duration compensation, greater supply pressure, and tighter global financial conditions.
Rich Privorotsky of Goldman Sachs tends to interpret this trend from a growth perspective:
"In my view, this increasingly looks like a reflection of strong growth assumptions (a 6% fiscal deficit plus $1.5 trillion in spending implies substantial bond supply and significant nominal growth). For equities, this is a clearer macro risk—not runaway inflation, but persistently high real cost of capital."
The Atlanta Fed's GDPNow model predicts that the US economy will grow at an annualized rate of 5.1% in the third quarter, which, if realized, would be the fastest growth rate since the post-pandemic recovery began. Economists at JPMorgan Chase noted after last week's Fed meeting that Fed officials "may be seeing rising risks of demand-driven overheating, and policy may need to respond to this."
Jason Granet, Chief Investment Officer and Head of Credit Services at BNY, raised a key question: "The Fed has already started raising rates. The question now is... will it stay on this path for quite some time?"
Effectiveness of Buyback Program in Doubt, Treasury Under Pressure
Facing continuously rising yields, Treasury Secretary Bessent has attempted to suppress yields by expanding the scale of long-term Treasury buybacks, but with limited effect.
On Wednesday, the Treasury announced it would buy back up to $6 billion of 20- to 30-year Treasuries on Thursday, the second operation since expanding the buyback program in mid-August. However, this scale disappointed the market. Bob Michele, Chief Investment Officer at JPMorgan Asset Management, stated bluntly:
"We thought the Treasury would see that the previous $6 billion buyback was a failure and would increase it to close to $10 billion this time. But they didn't."
After the announcement, 20-year and 30-year yields rose further, and bond volatility indicators jumped simultaneously, showing a serious lack of confidence in the buyback program.
Christopher Sullivan, Chief Investment Officer at United Nations Federal Credit Union, summarized the current dilemma in the bond market: "From the intractable conflict in Iran to the seemingly invincible US economy, holding bonds 'just doesn't make sense' for many people right now."
Equities Relatively Resilient, But Interest Rate Risks Cannot Be Ignored
Although the bond market suffered heavy losses, the decline in US stocks was relatively limited. Scott Kimball, Chief Investment Officer of Fixed Income at Loop Capital Asset Management, said, "Risk markets handled it quite well. This really looks like an interest rate market issue."
However, the continuous rise in yields has triggered chain reactions in the real economy—from mortgage rates and credit card rates to the willingness of private equity firms to conduct leveraged buyouts. The 30-year mortgage rate has exceeded 7%, putting direct pressure on the housing market.
Christophe Boucher, Chief Investment Officer at ABN AMRO Investment Solutions, warned that "pressure is accumulating on the short end of the yield curve," and today's economic data will allow the Fed to "double down" on its hawkish stance.
Brook, a strategist at RBC Capital Markets, frankly admitted that the market has fallen into a frustrating cycle:
"You can look at these yield levels and say they are really attractive. But we've been playing this game for the past six months; every time we try to draw a line somewhere, it continues to break through."