
 I'm LongbridgeAI, I can summarize articles.
ASML is set to report Q3 fiscal 2026 results on October 14, with Wall Street expecting revenue of approximately $13.2-$13.5 billion, a 55% year-over-year increase, and EPS around $12.47. Driven by AI infrastructure demand, the company's stock has surged, reaching a market cap of ~$700 billion. Investors are closely watching for gross margins near the upper guidance limit and strong High-NA EUV order momentum, as current growth is already priced in. Analysts have raised price targets, averaging $2,470.
TradingKey - ASML (ASML) will report its third-quarter fiscal 2026 financial results on October 14. As a core global supplier of extreme ultraviolet (EUV) lithography equipment, the company is benefiting from demand for advanced chips driven by the expansion of artificial intelligence infrastructure.
Markets currently expect ASML's third-quarter revenue to be approximately 11.6 billion to 11.8 billion euros, or roughly $13.2 billion to $13.5 billion, up about 55% year-over-year; expected earnings per American Depositary Receipt (ADR) share are approximately $12.1 to $12.5.
Consensus market expectations show ASML's third-quarter revenue at approximately $13.18 billion and earnings per share of around $12.47. As the company reports financial results in euros, U.S. dollar conversions and EPS accounting methodologies may vary across different data providers.
As of last Friday, ASML's stock price closed at $1,780.34, recording significant gains both year-to-date and over the past year, with its market capitalization rising to around $700 billion. As its valuation expands rapidly, this financial report needs not only to meet market expectations but also to prove that equipment demand driven by AI chips, advanced logic, and high-bandwidth memory can be sustained beyond 2027.
Third-Quarter Revenue Growth Already Reflected in Expectations
ASML previously expected third-quarter revenue to be between €11 billion and €12 billion, with a gross margin of 55% to 57%; installed base management revenue is expected to be approximately €2.9 billion, while R&D expenses and SG&A expenses are projected at around €1.2 billion and €400 million, respectively.
Based on market forecasts of around €11.6 billion to €11.8 billion, third-quarter revenue would sit near the mid-to-high end of the company's guidance range, representing significant growth compared to €9.33 billion in the second quarter. Compared to €7.5 billion in revenue from the same period in 2025, the increase could exceed 50%. Market forecasts for American Depositary Receipt (ADR) earnings per share are around $12.1 to $12.5, likewise reflecting the impact of an improved product mix and expanded revenue scale.
In the second quarter, ASML reported revenue of €9.33 billion and net profit of €2.92 billion, with basic earnings per share at €7.59. Installed base management revenue reached €2.76 billion, higher than management's original expectations, driving the gross margin up to 54%. Covering equipment maintenance, software upgrades, and productivity optimization, this business typically offers higher revenue stability than new equipment sales and serves as an important support for ASML's profit margins.
Because third-quarter revenue growth has already been fully anticipated by the market, simply reaching around €11.6 billion may not be enough to significantly drive up the stock price. Investors are more eager to see gross margins close to the upper limit of the 57% guidance, as well as service and upgrade revenues continuing to exceed expectations. If revenue approaches €12 billion while gross margins remain strong, it would indicate that high-value EUV systems and upgrade businesses are improving the overall product mix.
EUV Orders Are More Important Than Current-Quarter Revenue
ASML's recognized revenue for the quarter comes primarily from equipment orders signed months or even years ago, making net bookings a better reflection of future demand. Changes in EUV and High-NA EUV orders in the third quarter are likely to be key in determining the stock price direction after the earnings release.
ASML is the world's sole commercial supplier capable of supplying EUV lithography machines at scale. When TSMC, Samsung, Intel, and memory manufacturers expand advanced nodes, they all need to add EUV equipment. Rapidly growing demand for AI accelerators, custom chips, and HBM is driving advanced logic and DRAM makers to increase capital expenditures.
The company previously stated that its low-NA EUV capacity would be about 65 units in 2026, with plans to increase it by about 30% in 2027 and explore a further 30% expansion in 2028. DUV immersion lithography machines are following a similar expansion path, with capacity in 2026 at around 130 units. Management stated that 2027 low-NA EUV capacity is nearly fully covered by customer orders, and significant purchasing commitments have also been secured for 2028.
High-NA EUV is the core of ASML's long-term growth potential. With a unit price potentially reaching around $400 million, the equipment can enhance resolution for advanced processes and reduce the number of multiple exposure steps required in certain chip manufacturing stages. Intel previously completed High-NA EUV process qualification on certain 18A products, demonstrating that this technology is steadily progressing from R&D verification to mass production application.
A key focus for the third-quarter earnings report is the pace of High-NA equipment shipments and revenue recognition, as well as whether TSMC, Samsung, and Intel are accelerating adoption. If customer deployment timelines are advanced, ASML's average selling price and long-term revenue ceiling could be further raised.
Guidance Raised, Wall Street Average Price Target Rises to $2,470
In its second-quarter earnings report, ASML significantly raised its 2026 revenue guidance from the previous 36 billion to 40 billion euros to 43 billion to 45 billion euros, while raising its full-year gross margin forecast to 54% to 56%. This adjustment indicates that AI infrastructure investment is continuously translating into demand for advanced logic and memory capacity, while expansion plans from customers such as TSMC, Samsung, SK Hynix, and Micron Technology are also improving ASML's order visibility for the coming years.
Wall Street remains overall optimistic about ASML's long-term prospects. According to TipRanks, all 6 analysts covering the stock over the past three months have given it a Buy rating, with an average 12-month price target of $2,470.81, a high forecast of $2,865.89, and a low of $2,100. Based on the latest closing price of $1,780.34, the average price target represents a potential upside of approximately 38.78%.
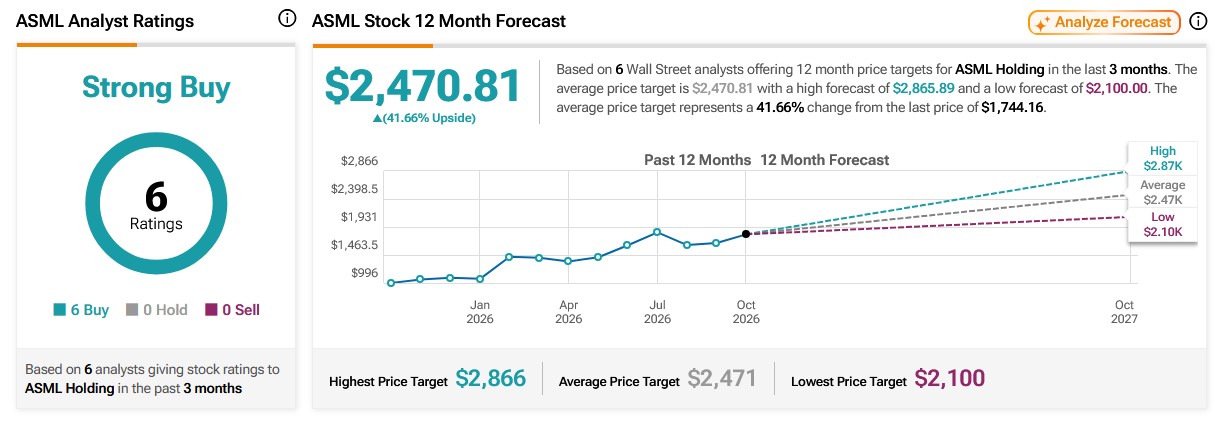
Source: TipRanks
Find out more