
 I'm LongbridgeAI. Here is the key information I extracted
Overview of Key Financial Events for the Week of November 02 - November 08 (All times in Beijing Time):
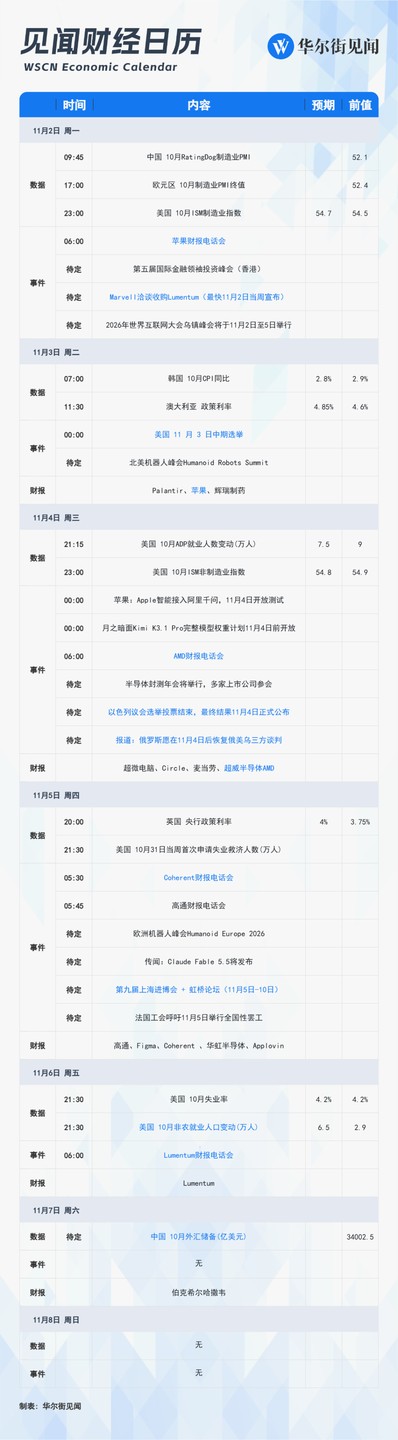
Wallstreetcn Calendar Reminder: Key Points to Watch Next Week:
Last Friday, Intel plummeted 29%, marking its largest single-day drop in history, while the NASDAQ Composite Index recorded its worst month in over a year. Amazon's capital expenditure hit record highs, Google's free cash flow turned negative, and Intel's gross margin guidance dropped sharply, severely damaging confidence in AI trades and leading to a broad sell-off in tech stocks.
Earnings: Next week, Apple and AMD will be the tech giants tested after this round of AI-driven selling — Apple's consensus revenue is approximately $113 billion, marking the debut of new CEO Tenus; AMD's guidance is around $13 billion, with the ramp-up of Helios cabinets and MI450 chips determining whether it can maintain its trillion-dollar market cap. These two earnings reports will directly price in whether market sentiment can stabilize. Additionally, earnings from optical module giants Coherent and Lumentum, Qualcomm, Super Micro Computer, and Berkshire Hathaway will also be released. Furthermore, reports indicate that Marvell is in discussions to acquire Lumentum, with an announcement possible as early as next week. Apple Intelligence will integrate Alibaba's Qwen, with testing opening on November 4.
Elections and Geopolitics: US Midterm Elections on November 3 will see the reelection of all 435 House seats and 35 Senate seats. The results will determine the difficulty Trump faces in advancing fiscal policies, tariffs, and industrial subsidies over the next two years. Betting markets currently price the probability of a Democratic "sweep" of both chambers at 67%. On November 4, the final results of the Israeli parliamentary elections will be announced, and trilateral negotiations between Russia, the US, and Ukraine are scheduled to resume in Abu Dhabi the same week. If successful, this would be the highest-level contact since Istanbul, causing fluctuations in oil, gas, and safe-haven assets.
Regarding economic data, the US October Non-Farm Employment data will be released. The previous value for September was only an increase of 29,000, with an expectation of 65,000. The 10-year US Treasury yield has closed at 4.9%. A stronger reading will consolidate expectations for a rate hike, causing synchronized movements in the US dollar, US Treasuries, and gold, making it the most significant macroeconomic data point globally next week. From China, October Foreign Exchange Reserves will be announced. Additionally, the 9th China International Import Expo and the Wuzhen Summit will open concurrently.
2027 Wallstreetcn Calendar: Lay out the year's important financial schedule in front of you in advance
While others react when events occur, you can know the next step by opening the calendar
Long-press the image to scan and purchase
Economic Indicators
- US October Non-Farm Payrolls Change and Unemployment Rate
On November 6, the US October non-farm payroll data will be released. September saw an increase of only 29,000 jobs, while the market expects an increase of 65,000 in October. The unemployment rate will be released on the same day. This is the most critical data point globally this week: the 10-year US Treasury yield closed at 4.9% this week. White House official Hassett stated that if inflation remains high, there is sufficient reason for the next rate hike. A stronger reading will consolidate rate hike expectations, causing synchronized fluctuations in the US dollar, US Treasuries, and gold, while US stocks switch between two narratives.
- Bank of England Policy Rate and Reserve Bank of Australia Policy Rate
On November 3, the Reserve Bank of Australia will announce its policy rate. The previous value was 4.60%, with market expectations rising to 4.85%, which would be the fifth rate hike of the year. On November 5, the Bank of England will announce its policy rate. The previous value was 3.75%, with market expectations of a 25 basis point hike to 4.00%. If rates are raised, concerns will focus on services inflation and wage growth. The reaction of the British pound and UK bonds to the statement's wording is typically greater than to the rate figure itself.
- China October Foreign Exchange Reserves
China's October Foreign Exchange Reserves will be announced on November 7. At the end of September, the reserve stood at $3400.25 billion. The central bank has increased its gold reserves for 23 consecutive months, with the volume of gold holdings being a recent focal point.
Earnings Reports
- Apple, AMD, Lumentum, Coherent, Qualcomm
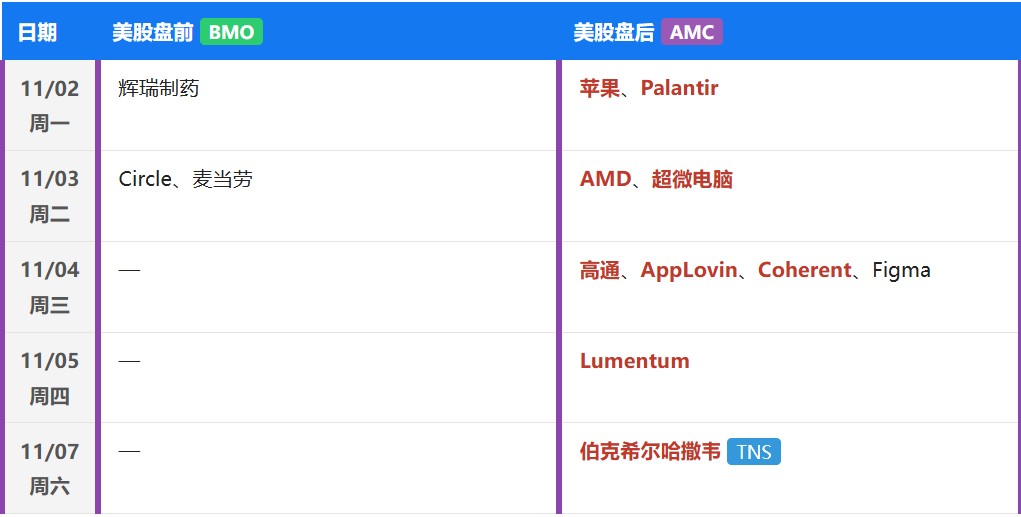
After the market close on Monday, Apple and Palantir will report. Apple's report is the first under new CEO Tenus, with consensus revenue around $113 billion and EPS of $1.98. Key points include memory price increases and holiday season guidance. After the market close on Tuesday, AMD will guide for revenue of approximately $13 billion and a gross margin of 56%, with the ramp-up of Helios and MI450 determining its trillion-dollar market cap. Earnings from Qualcomm, Lumentum, Coherent, and Berkshire Hathaway will also be released.
- A-Share Q3 Reports Concluded; Focus on Hua Hong Semiconductor in HK Stocks
The formal disclosure of A-share Q3 reports concluded on October 31, entering a disclosure gap next week. The next dense window will be the annual report preview period, during which performance clues will mainly come from institutional research and industry data following the Q3 reports. For HK stocks, watch for Hua Hong Semiconductor's earnings report on November 5.
Financial Events
- US Midterm Elections on November 3
The US will hold midterm elections on November 3, reelecting all 435 House seats and 35 Senate seats (including special elections for 2 seats in Florida and Ohio). The Republicans currently hold 218 seats in the House versus 214 for Democrats, and 53 in the Senate versus 47. Democrats need a net gain of 3 seats in the House and 4 in the Senate to flip control. If the Senate ends in a 50:50 tie, Vice President Vance will cast the deciding vote. The allocation of power over appropriations, tax bills, and personnel confirmations will thereby rewrite the difficulty of advancing fiscal policies, tariffs, and industrial subsidies. Betting markets currently price the probability of a Democratic "sweep" of both chambers at 67%.
- Final Results of Israeli Parliamentary Elections on November 4
According to CCTV International News, voting for the 26th Israeli Knesset election ended on the evening of October 27. Data from the Central Elections Committee shows a voter turnout of 74.3%, higher than the 66.3% in the same period of 2022, marking the highest for this period since 1988. Parties must cross a 3.25% vote threshold to enter the Knesset, with 120 seats allocated proportionally. The final results will be officially announced by the committee on November 4, after which the President will authorize a member to form a government.
- Russia Willing to Resume Trilateral Russia-US-Ukraine Negotiations After November 4
Citing Russian media reports on the 25th, Xinhua News Agency reported that Russian Presidential Aide Ushakov stated in an interview that Russia is willing to resume trilateral negotiations involving Russia, the US, and Ukraine after November 4. Ukrainian Foreign Minister Sybiga stated on the 27th that Ukraine is ready to participate in trilateral talks with the US and Russia in the United Arab Emirates and will use every opportunity to promote peace.
- Marvell in Talks to Acquire Lumentum (Announcement Possible as Early as the Week of November 2)
Marvell Technology is in deep negotiations to acquire data center optical device manufacturer Lumentum, potentially reaching a large M&A deal in the AI hardware supply chain. On October 28, Bloomberg cited insiders stating that the deal could be announced as early as next week. However, no final agreement has been reached, and details including timing remain variable.
- Apple: Apple Intelligence Integrates Alibaba's Qwen, Testing Opens on November 4
On October 31, Apple and Alibaba announced a partnership to integrate Qwen into Apple Intelligence. Chinese users will be able to directly utilize Qwen's text and image understanding, content generation, and other capabilities within Siri, writing tools, and visual intelligence. These features will open for testing with the latest iOS developer Beta version starting November 4 and will be officially launched for Chinese users with the release of iOS 27.3 in December.
- Shanghai CIIE + Hongqiao Forum (November 5-10)
The 9th China International Import Expo will be held in Shanghai from November 5 to 10, with the Hongqiao International Economic Forum opening concurrently. As a national-level open platform, the CIIE annually releases concentrated signals on Chinese import orders and market access. Key points include intended transaction amounts and signing situations in consumer goods, high-end equipment, and medical exhibition areas, influencing import chains and RMB asset sentiment.
- 2026 World Internet Conference Wuzhen Summit to be Held from November 2 to 5
From November 2 to 5, the 2026 World Internet Conference Wuzhen Summit will be held in Wuzhen, Zhejiang, with the theme "Open Source and Openness, Co-construction and Sharing – Joining Hands to Build a Community with a Shared Future in Cyberspace." It will feature 27 sub-forums, including the AI Wuzhen Dialogue and discussions on robotics and embodied intelligence. According to the Chinese government website, the conference invites representatives from global governments, international organizations, enterprises, and experts to exchange ideas on the concepts and practices of open-source and open development in artificial intelligence.
- SSE STAR Chip ETF Goes Overseas, to List on HKEX
The SSE STAR Chip ETF (588200) will go overseas through the Shanghai-Hong Kong ETF mutual listing. The HKEX mutual listing fund tracking this ETF was approved on October 28 and is expected to list on the Hong Kong Stock Exchange on November 6. Overseas investors will be able to trade directly in the HK stock market, facilitating convenient allocation to SSE STAR Market Chip Index assets.
- AI Large Model Tracking: Kimi K3.1 Pro Full Model Weights Open, Claude Fable 5.5 May Be Released
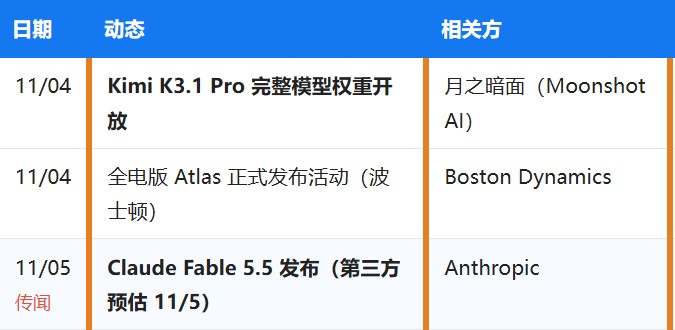
In the early hours of October 24, Moonshot AI released the first model of the Kimi K3.1 series, Kimi K3.1 Pro, and the high-speed version Kimi K3.1 Pro Highspeed. Full model weights are planned to be opened before November 4. Third-party countdown sites estimate that Claude Fable 5.5 will be released on November 5. Anthropic has not officially announced the date or model ID; however, the Microsoft Azure East US 2 directory already lists claude-fable-5-5, noting 1M context, a maximum output of 128,000 tokens, and an input cost of $10 per million tokens. This timing closely aligns with Anthropic's IPO roadshow starting the week of November 9.
- AI Industry Activity Tracking
AI activities are concentrated on two lines: Domestically, the Wuzhen Summit and the Security Expo, with the former themed around open source and featuring 27 sub-forums, and the latter introducing embodied intelligence and low-altitude security exhibition areas for the first time, with practical implementations of security large models and public safety agents being key points; Overseas, two humanoid robot summits in North America and Europe, where hardware manufacturers typically update their annual delivery guidance and supply chain lists, and domestic manufacturers' participation criteria are compared by the market.

- Semiconductor Packaging and Testing Annual Conference to be Held, Multiple Listed Companies Attending
Reporters learned that the 24th China Semiconductor Packaging and Testing Technology and Market Annual Conference (referred to as the "Packaging and Testing Annual Conference") will be held from November 4 to 6 at the Fengda International Hotel in Nanjing. During the two-day conference, leading companies in semiconductor packaging and testing, chip design, glass substrates, and advanced packaging equipment, such as Huatian Technology, JCET, Tongfu Microelectronics, Nanjing TSMC, Biren Technology, BOE, and Yuntian Semiconductor, will exchange views on the latest development directions in advanced packaging through main forums, thematic reports, and supply-demand matching sessions. (Shanghai Securities News)
- French Unions Call for Nationwide Strike on November 5
French unions have called for a nationwide strike on November 5.
Advance Warning for the Following Week
- November 9: China October CPI year-on-year; November 10: China October Imports and Exports.
- Anthropic Plans to Start IPO Roadshow as Early as the Week of November 9. According to media reports, Anthropic plans to start its formal IPO (Initial Public Offering) roadshow as early as the week of November 9.
- Two US Leveraged ETFs Linked to SK Hynix to Liquidate and Delist. Tradr ETFs announced that two of its leveraged products linked to SK Hynix ADRs will liquidate and delist around November 12. One is long and one is short. Listed for only a few months, their combined scale has shrunk to approximately $1.3 million, a drop of over 60% from their peak.
- November 10-11: US Stocks CoreWeave, Applied Materials, and Cisco to Disclose Earnings.
- Further out: Week of November 16, Anthropic lists on NASDAQ; November 17-18, APEC Meeting held in Shenzhen.