
 I'm LongbridgeAI, I can summarize articles.
Author: Zhou, ChainCatcher
Circle released its Q3 2026 earnings report before the US stock market opened on November 4th. Both revenue and earnings per share exceeded market expectations. This is the first time the company has delivered a seemingly good report card after two consecutive quarters of revenue falling short of expectations.
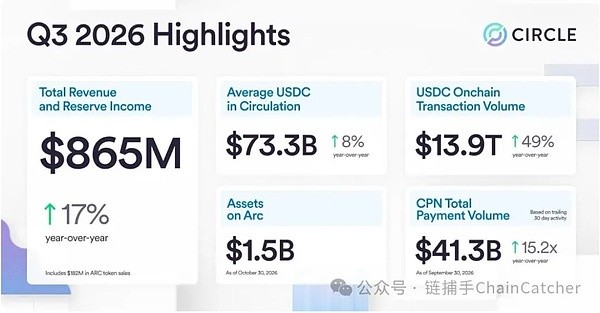
However, the better-than-expected performance was mainly driven by the one-time revenue from the pre-sale of ARC, the native token of its public chain Arc. At the same time, the company disclosed that it had laid off approximately 5% of its employees.
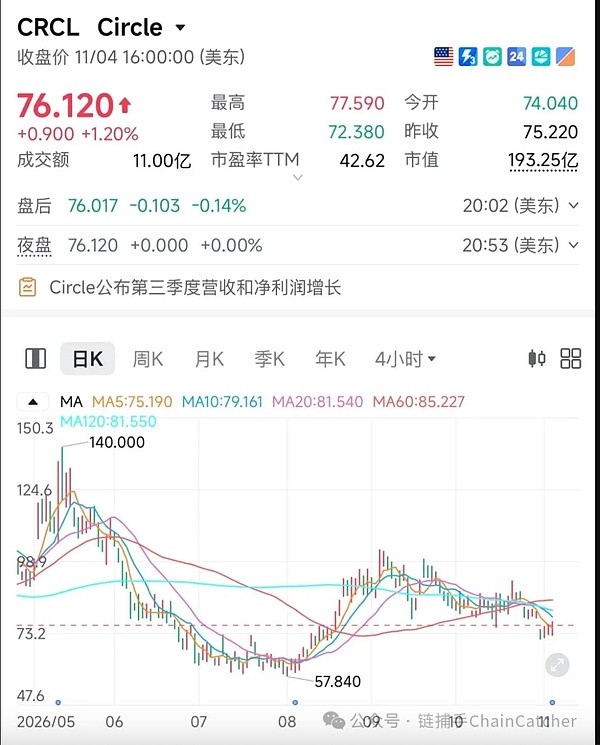
After the earnings release, Circle's stock price initially rose in pre-market trading before falling, ultimately closing slightly higher at $76.12, with a total market capitalization approaching $20 billion..
1. Better-than-expected performance mainly supported by ARC pre-sales
Circle Q3Total revenue and reserve income of $865 million, up 17% year-over-year. Net income from continuing operations of $226 million, up 5% year-over-year. Adjusted EBITDA was $317 million, an 85% year-over-year increase. Diluted earnings per share were $0.84, compared to market expectations of $802 million in revenue and $0.40 per share. The better-than-expected results were primarily driven by other revenue. Other revenue for the quarter was $207 million, a year-over-year increase of 627%, of which $182 million came from the ARC token presale. The ARC presale was completed in two rounds, raising a total of approximately $242 million. CFO Jeremy Fox-Geen explained in the conference call that presale revenue is recognized according to performance milestones, and with the completion of token delivery and the launch of the Arc mainnet, approximately 75% was recognized in the third quarter. This revenue has no corresponding distribution costs, making its contribution to profits more significant. Revenue excluding distribution, i.e., RLDC, reached $453 million, a year-over-year increase of 55%, and the RLDC profit margin rose from 41% in the second quarter to 52%. The adjusted EBITDA margin was 70%, and 50% excluding ARC. 2. Excluding ARC, core business revenue and profit declined year-over-year. According to the financial report, excluding pre-sale revenue, Circle's third-quarter revenue was approximately $683 million, a year-over-year decrease of approximately 8%, also lower than the previous two quarters. Adjusted EBITDA was approximately $135 million, a year-over-year decrease of approximately 21%, and pre-tax profit was approximately $46 million, the lowest this year. The main reason is the decline in reserve revenue. Third-quarter reserve revenue was $658 million, down 8% year-over-year, with the reserve return rate declining 61 basis points year-over-year to 3.54%, partially offset by an 8% increase in average circulating supply. Other revenue streams also failed to compensate. Excluding pre-sales, other revenue was only $25 million, down 11% year-over-year, which Fox-Geen attributed to a decrease in monetized blockchain integration projects during the quarter. Profit margins were also under pressure. Excluding pre-sales, RLDC's profit margin was 39.7%, down approximately 150 basis points from the second quarter. Net reserve profit margin declined approximately 80 basis points sequentially to 37.8%, which, according to Fox-Geen, was the first full quarter under the revenue-sharing arrangement with Hyperliquid. Even including pre-sale revenue, net profit only increased by 5% year-on-year, mainly due to a high base from approximately $61.3 million in income tax benefits in the same period last year. 3. USDC circulating supply stagnated, Circle intensified distribution to cope with competition. Reserve returns follow interest rate trends. Circle can actively strive for increased circulating supply, but this metric is also weak. At the end of the third quarter, USDC circulating supply was $73.9 billion, flat compared to the same period last year, and the average circulating supply for the quarter was also lower than in the second quarter. The total supply of stablecoins increased by 8% year-on-year to approximately $274 billion, while USDC's market share fell to 27%, a decrease of 183 basis points year-on-year, a significant widening of the decline compared to the second quarter. At the end of June, Open Standard, together with over 140 institutions including Visa, Mastercard, and Stripe, announced the launch of Open USD, a revenue-sharing stablecoin, raising concerns about USDC's distribution advantages. CEO Jeremy Allaire stated in a conference call that Circle will continue to increase its distribution investment, acknowledging a trade-off between incentives for partners and circulating supply growth. Binance is the latest example. The two parties signed a new five-year agreement, with Binance also investing $100 million in Circle. Specific economic terms were not disclosed, but Fox-Geen stated that the renewal did not involve upfront fees. Regarding Binance's recent security incidents, Allaire stated that Binance has recorded a net inflow of approximately $2.5 billion in the past 24 hours. Regarding the flat circulating supply, Allaire attributed it to the weak crypto market and emphasized that usage is still growing. According to him, USDC, with approximately 27% of the supply, carries 79% of the stablecoin trading volume, compared to 66% in the same period last year. On-chain transaction volume reached $13.9 trillion in the quarter, a year-on-year increase of 49%, with minting and redemption totaling $208 billion, a record for the quarter. Circle maintains its multi-year compound annual growth rate target of 40% in circulating supply, and Fox-Geen expects usage growth to drive a long-term recovery in circulating supply. Circle has already laid off approximately 5% of its workforce, and the CFO will step down at the end of the year. Circle conducted layoffs in the same quarter that its core business revenue declined. The company disclosed in its financial statement notes that it laid off approximately 5% of its workforce in the third quarter and incurred restructuring costs of $9.1 million, primarily for severance pay and other cash outlays. The company stated that this adjustment aimed to align its organizational structure with its operating model and strategic priorities. According to Circle's annual report, the company will have approximately 1,100 employees by the end of 2025; based on this estimate, the layoffs affected approximately 55 positions. The layoffs did not result in cost reduction. Fox-Geen stated that adjusted operating expenses increased year-over-year, primarily due to investments in Arc and AI-related infrastructure, as well as marketing expenditures including Chelsea sponsorship. Third-quarter marketing expenses more than doubled year-over-year to $11.3 million, while IT infrastructure expenses increased by approximately 90% year-over-year. Circle announced in September that CFO Jeremy Fox-Geen will step down by the end of the year, and the company is looking for a successor. Arc completes the genesis minting of 10 billion ARC tokens, transitioning to PoS and monetizing through staking. In its new business, Allaire stated that Arc is Circle's largest platform staking platform since USDC. The Arc mainnet launched on September 16th, operated by 11 founding validator nodes, and has connected with over 100 institutions and applications, including financial institutions such as BNY, HSBC, and Visa, as well as DeFi protocols such as Aave and Uniswap. As of late October, on-chain assets totaled approximately $1.5 billion. In the third quarter, Circle completed the genesis minting of 10 billion ARC tokens, becoming the first publicly traded company to mint network tokens for the new L1 blockchain. Circle holds 25% of these, and Arc plans to transition to PoS in 2027. Fox-Geen introduced three ways to monetize Arc, with all related revenue recorded as other income. Staking rewards are expected to be the primary recurring revenue, as Circle will stake its ARC holdings and earn rewards as a validator node after the PoS transition. The company may also selectively sell ARC, with the proceeds directly recorded as profit. ARC distributed to ecosystem participants will be recorded as revenue based on market capitalization, along with an equivalent distribution cost. He also pointed out that, according to US accounting standards, the value of ARC held by Circle is only recognized upon sale or distribution and is not currently reflected in the financial statements. According to Circle's filings with the SEC, the ARC held by investors in the second round of pre-sale will be locked for at least one year after Arc transitions to PoS, and will not be freely transferable until at least 2028. The risk warning also indicates that Circle may need to refund pre-sale funds if key milestones are not achieved. Against the backdrop of the Binance hack, Allaire also highlighted security as a selling point for Arc. He believes that Arc, operated by a known institution, better meets the security requirements of financial institutions than permissionless public chains. 6. CPN Payment Volume Nearly Triples in Three Months, Expected to Contribute Significant Revenue in 2027. CPN's annualized payment volume, calculated over the past 30 days, reached $41 billion at the end of the third quarter, representing a year-on-year increase of over 15 times and nearly a three-fold increase compared to the end of June. As of October 30, this figure had exceeded $58 billion. In September, Circle announced the acquisition of Singapore-based cross-border payment platform Tazapay for $400 million in Class A shares, a transaction expected to close in 2027. Tazapay's annualized payment volume exceeds $25 billion, with approximately 60% involving stablecoins. Allaire stated that Asia is the most active region for the Circle platform, and the company is in contact with the Hong Kong government, confident in its ability to enter Hong Kong's offshore stablecoin regulatory framework. Fox-Geen revealed that the company has already begun charging for some of CPN's traffic, and expects CPN to contribute substantial revenue in 2027 after Tazapay's integration. However, Allaire emphasized that Circle's goal is to reduce the unit cost of payments and will not replicate the fee structure of the traditional payment industry. 7. Guidance Remains Unchanged, Q4 Profit Margin Expected to Decline Due to Binance Incentives Circle maintains its full-year guidance unchanged. Full-year other revenue guidance is $310 million to $330 million, and RLDC profit margin is 41.7% to 43.7%, both including confirmed ARC presale revenue. Based on this, Q4 other revenue excluding ARC is expected to be approximately $30 million to $50 million, up from $25 million in Q3. Fox-Geen expects this to rebound as blockchain integration increases. Regarding profit margins, RLDC's profit margin for the first three quarters was approximately 45.5%. If the full-year figure falls within the guidance range, based on a rough estimate of fourth-quarter revenue of approximately $700 million, RLDC's profit margin for the fourth quarter would be approximately 29% to 38%, lower than the level of around 40% in previous quarters. Fox-Geen confirmed the decline in fourth-quarter profit margins in response to a question from a Goldman Sachs analyst. He stated that excluding ARC, the full-year RLDC profit margin would be close to the midpoint of the original guidance of 38% to 40%, and the decline in the fourth quarter can be seen by working backward from this, as Binance's incentive arrangements will be fully counted in a quarter for the first time. The fourth quarter is also the first quarter in which both the Hyperliquid revenue sharing arrangement and the renewed Binance partnership are fully accounted for. Fox-Geen refers to these two partnerships as investments in distribution, aimed at driving USDC circulation and RLDC growth in the long term. On the expense side, the full-year adjusted operating expense guidance remains at $570 million to $585 million, still trending towards the high end of the range. Based on this, the adjusted operating expenses for the fourth quarter are estimated to be approximately $149 million to $164 million, higher than the $139 million in the third quarter. It's worth mentioning that a retail shareholder asked when non-interest income would become a significant contributor, given that USDC's adoption rate was significantly outpacing revenue and profit growth. Allaire responded that the monetization of CPNs, the integration with Tazapay, and Arc's shift to PoS would collectively drive revenue diversification.