

China Aluminum Q1 Net Profit Expected to Increase 50% to 58% YoY, Reaching Historic Best for the Period | Cailian Press
 I'm LongbridgeAI, I can summarize articles.
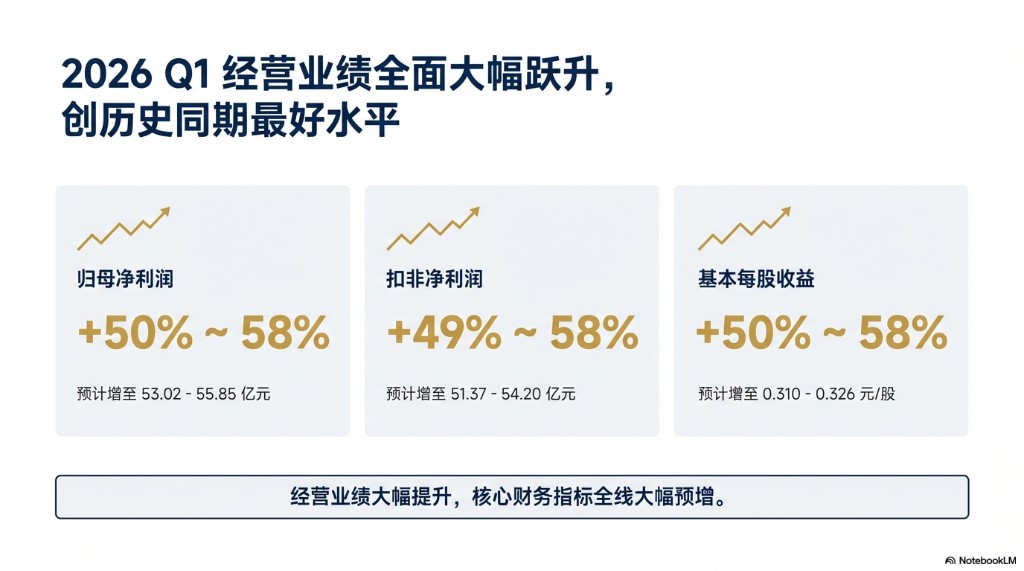
China Aluminum expects its first-quarter 2026 net profit attributable to parent company to reach RMB 5.302 billion to RMB 5.585 billion, a year-on-year increase of 50% to 58%, reaching the best level in the same period in history. The profit is mainly driven by the core business, with a synchronized increase in net profit after deducting non-recurring items. The substantial improvement in performance is attributed to three core factors: the dilution of marginal costs due to full production at stable and optimized levels, enhanced raw material bargaining power from an increased self-mining ratio, and refined cost reduction management through whole-industry chain synergy
On April 8, China Aluminum disclosed its first-quarter 2026 performance pre-increase announcement, expecting net profit attributable to shareholders of the listed company to be between RMB 5.302 billion and RMB 5.585 billion, a year-on-year increase of 50% to 58%, with an incremental gain of RMB 1.767 billion to RMB 2.050 billion. This performance significantly exceeds market expectations for the traditional off-season in the aluminum industry, and the company has characterized it as "the best level in the same period in history."
Profit quality is also resilient. Net profit after deducting non-recurring gains and losses is expected to be between RMB 5.137 billion and RMB 5.420 billion, a year-on-year increase of 49% to 58%, which is largely in sync with the increase in net profit attributable to the parent company. This indicates that performance is primarily driven by the core business, rather than relying on one-off gains. Basic earnings per share correspondingly rose to RMB 0.310 to RMB 0.326, an increase of over 50% from RMB 0.206 in the same period last year.
In comparison, the net profit attributable to the parent company in the same period last year (Q1 2025), after restatement, was RMB 3.535 billion. The mid-point for the current period is approximately RMB 5.444 billion, representing an expansion of nearly RMB 1.9 billion in profit volume within one year. In the aluminum industry, which is capital-intensive and has significant cyclical attributes, such a substantial year-on-year surge benefits from the external environment of a rising aluminum price center and also reflects the company's internal contributions in cost control and production capacity release.
Full Production at Stable and Optimized Levels: Significant Dilution of Marginal Costs Due to Increased Capacity Utilization
The announcement clearly states that "full production at stable and optimized levels is one of the core supports for the substantial improvement in performance during this period." For integrated enterprises like China Aluminum, with electrolytic aluminum and alumina as core assets, a one-percentage-point increase in capacity utilization significantly dilutes marginal costs.
Against the backdrop of relatively high aluminum prices, full production means maximizing the profit window per ton into actual profit. The company emphasizes that "various production and operation indicators continue to optimize," indicating that profit growth not only relies on production expansion but also benefits from simultaneous improvements in quality control and production efficiency, thereby further amplifying the synergistic effect of rising volume and prices.
Increased Self-Mining Ratio Enhances Bargaining Power for Raw Materials
The announcement specifically mentions that the self-mining ratio of resources has further increased. For aluminum smelting enterprises, bauxite is the most upstream core raw material. Purchasing ore externally is not only more costly but also faces risks of supply chain fluctuations. The increase in the self-mining ratio means the company's bargaining power at the raw material end is enhanced, and procurement costs are reduced, while also compressing the profit margins of third-party suppliers.
This logic is particularly crucial against the backdrop of intensifying global mineral resource competition. By extending the industry chain upstream, China Aluminum can capture a larger share of value throughout the entire process from bauxite to alumina to electrolytic aluminum, rather than solely relying on price differentials in the downstream smelting segment.