

Does Steeper Losses And Weaker Revenue Growth Change The Bull Case For Service Properties Trust (SVC)?
 I'm LongbridgeAI, I can summarize articles.
Service Properties Trust (SVC) reported Q2 2026 results showing revenue decline to $420.97 million and a widened net loss of $223.84 million. This deterioration challenges the bull case for its pivot to net lease properties, raising concerns about leverage and refinancing costs. The recent $500 million equity offering is now critical for addressing balance sheet risks. Analysts project positive earnings by 2029, but current losses highlight significant near-term investment risks.
- Service Properties Trust recently reported its second-quarter 2026 results, with revenue falling to US$420.97 million from US$503.44 million a year earlier and net loss widening to US$223.84 million from US$38.16 million.
- Although the six-month net loss increased to US$375.02 million, basic loss per share from continuing operations was largely unchanged at US$4.63 versus US$4.67 a year earlier, suggesting the larger loss is being spread across a bigger share base.
- We’ll now examine how this wider quarterly net loss and weaker revenue performance could reshape Service Properties Trust’s existing investment narrative.
Explore 26 top quantum computing companies leading the revolution in next-gen technology and shaping the future with breakthroughs in quantum algorithms, superconducting qubits, and cutting-edge research.
Service Properties Trust Investment Narrative Recap
To own Service Properties Trust today, you need to believe its pivot toward net lease properties and ongoing hotel repositioning can eventually translate recurring revenue into more stable cash flows, despite prolonged losses. The latest quarter makes that belief harder to hold near term, with revenue down to US$420.97 million and net loss deepening to US$223.84 million. That deterioration arguably heightens the main risk right now around leverage, refinancing costs and the company’s capacity to support even a modest dividend.
The most relevant recent announcement is the US$500 million follow on equity offering completed in March 2026. In light of the wider net loss and still negative earnings, this capital raise now looks even more central to the story, because it interacts directly with balance sheet risk and the ability to refinance expensive debt. For many investors, the core catalyst has shifted toward seeing clear evidence that this new equity actually translates into lower interest burden and better coverage ratios.
But while the stock may screen as “good value” on revenue multiples, investors should be aware that elevated leverage and ongoing net losses could still...
Read the full narrative on Service Properties Trust (it's free!)
Service Properties Trust’s narrative projects $1.4 billion in revenue and $144.2 million in earnings by 2029.
Uncover how Service Properties Trust's forecasts yield a $2.33 fair value, a 72% downside to its current price.
Exploring Other Perspectives
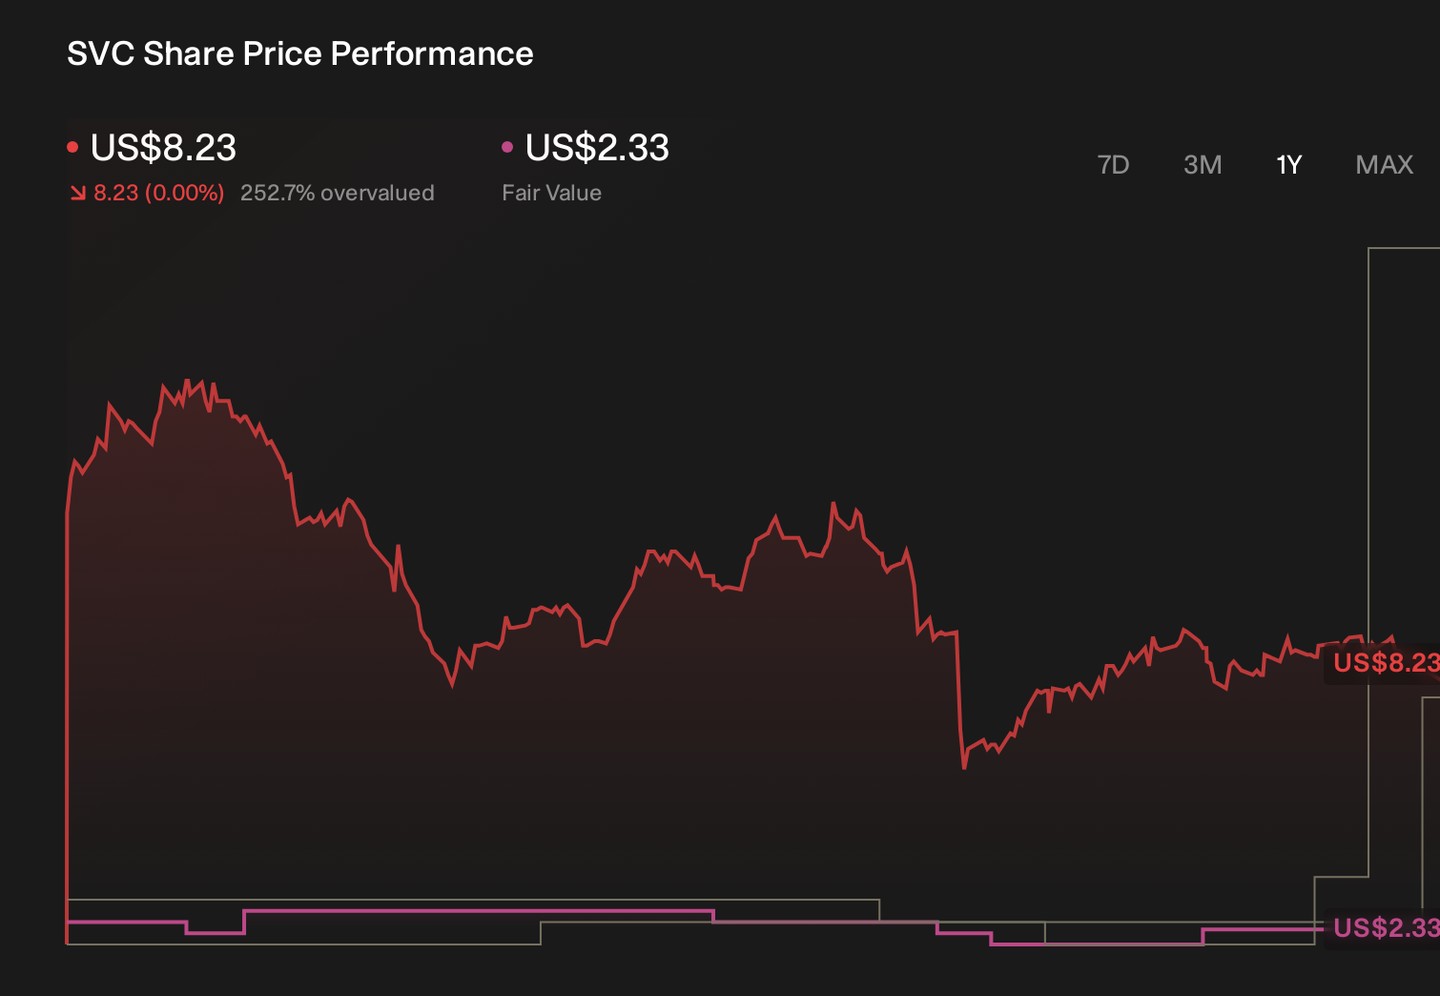
Before this weak quarter, the most optimistic analysts were still assuming revenue would shrink about 5.6 percent a year and earnings only turn positive by 2029, so this latest loss could push you to question whether that upbeat path or the more cautious balance sheet focused view better fits what you are seeing now.
Explore 3 other fair value estimates on Service Properties Trust - why the stock might be worth as much as 28% more than the current price!
The Verdict Is Yours
Don't just follow the ticker - dig into the data and build a conviction that's truly your own.
- A great starting point for your Service Properties Trust research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- Our free Service Properties Trust research report provides a comprehensive fundamental analysis summarized in a single visual - the Snowflake - making it easy to evaluate Service Properties Trust's overall financial health at a glance.
No Opportunity In Service Properties Trust?
Don't miss your shot at the next 10-bagger. Our latest stock picks just dropped:
- The future of work is here. Discover the 37 top robotics and automation stocks leading the charge in AI-driven automation and industrial transformation.
- Outshine the giants: these 17 early-stage AI stocks could fund your retirement.
- AI is about to change healthcare. These 43 stocks are working on everything from early diagnostics to drug discovery. The best part - they are all under $10b in market cap - there's still time to get in early.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
New: Manage All Your Stock Portfolios in One Place
We've created the ultimate portfolio companion for stock investors, and it's free.
• Connect an unlimited number of Portfolios and see your total in one currency
• Be alerted to new Warning Signs or Risks via email or mobile
• Track the Fair Value of your stocks
Try a Demo Portfolio for Free