
O

Aug 11 at 06:43 AM
🐶 Options Puppy Morning Macro Note (11 Aug 2026)
 I'm LongbridgeAI, I can summarize articles.
The market feels very different now. 🧐
We are seeing QT happening while US Treasury yields fall, the Japanese Yen stabilizes, and both bonds and stocks rally together. That is not the usual textbook setup.
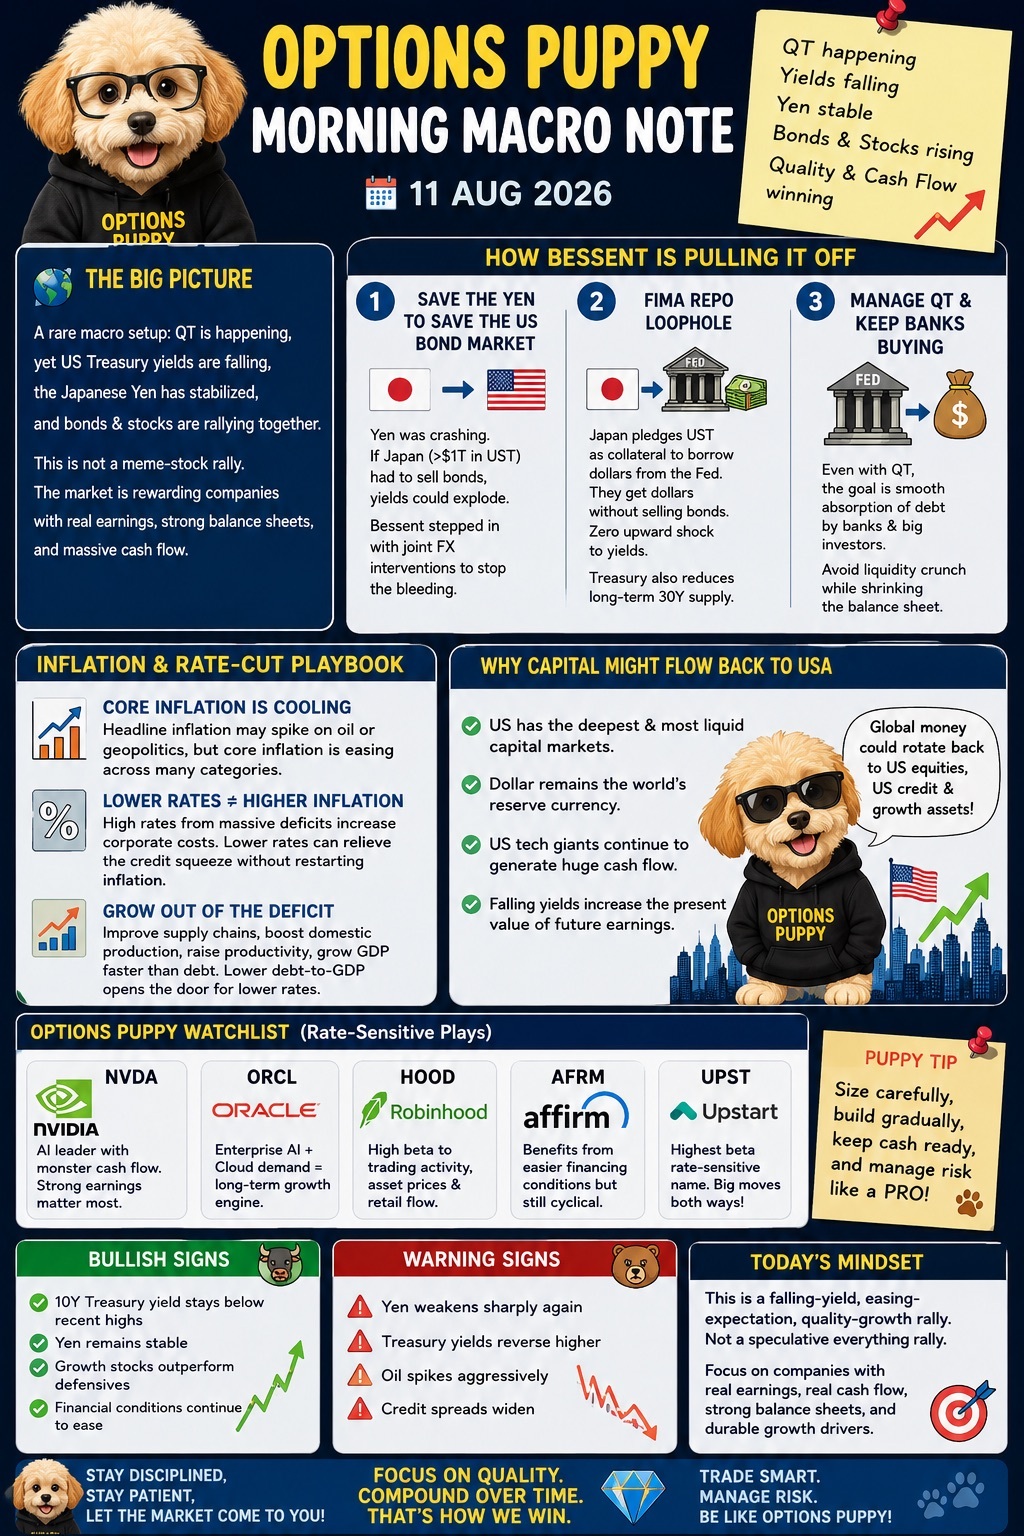
The interesting part is that this rally is not a meme-stock rally. The market is rewarding companies that are actually printing cash flow and reporting strong earnings. 💵📈
As the market starts to price a possible September rate pivot, I think the biggest move could happen in rate-sensitive stocks. Options Puppy likes to think ahead rather than chase after the crowd.
🐶 Why I am watching rate-sensitive names
These are higher-risk ideas, but they tend to react strongly when yields fall:
- UPST
- AFRM
- HOOD
- ORCL
- NVDA$NVIDIA(NVDA.US)
When interest rates drop, financing conditions improve, borrowing becomes cheaper, and growth expectations usually expand. That is why these names can move very quickly once the market believes easier policy is coming. 🚀
🇯🇵 Step 1: Saving the Yen to protect the US bond market
The first problem was the Japanese Yen. It was weakening sharply.
Why does the US care? Because Japan owns a huge amount of US Treasuries. If Japan had to sell a large amount of bonds to defend its currency, Treasury prices could fall and yields could spike. 📉➡️📈
The policy response was to stabilize the Yen before that stress spilled into the US bond market.
🏦 Step 2: The FIMA repo backstop
Instead of forcing Japan to sell Treasuries for dollars, the Fed can provide dollars through the FIMA Repo Facility.
Japan can pledge Treasuries as collateral, borrow dollars, support the Yen, and keep the bonds on its balance sheet. 🏛️💵
That helps reduce upward pressure on Treasury yields.
At the same time, the Treasury can lean more on shorter-term issuance and reduce pressure from long-duration supply.
🏦 Step 3: QT without a funding accident
Even though the Fed is shrinking its balance sheet, policymakers still want banks and large investors to absorb government debt smoothly.
The goal is simple: avoid a liquidity crunch while QT continues.
Think of it as trying to remove excess liquidity slowly without causing a seizure in the plumbing of the financial system. 🔧
📉 The inflation argument
The bullish macro case is that core inflation is cooling even if headline inflation occasionally jumps because of oil or geopolitical events.
If underlying inflation keeps easing, the Fed has more room to cut rates later.
Lower policy rates would reduce financing costs for businesses and households and could support economic activity without automatically creating another inflation spiral.
🏭 Growing out of the deficit
The longer-term thesis is not austerity. The idea is:
- improve supply chains,
- increase domestic production,
- raise productivity,
- and grow GDP faster than debt.
If growth improves, the debt-to-GDP ratio can stabilize over time, making lower interest rates more sustainable.
🇺🇸 Why capital might flow back to the United States
This is the part I think many investors are underestimating.
If US yields decline in an orderly way while the economy remains relatively resilient, global investors may prefer US assets again. 🌎➡️🇺🇸
Possible reasons:
- the US still has the deepest capital markets,
- the dollar remains the main reserve currency,
- large-cap tech companies continue to generate strong cash flow,
- and falling yields increase the present value of future earnings.
If Japanese yields stay contained and Europe remains slower-growth, international capital could rotate back into US equities, US credit, and even longer-duration growth assets.
That would be another tailwind for names such as NVDA, ORCL, HOOD, AFRM, and UPST.
🐶 What Options Puppy is watching today
Bullish signs
- 10Y Treasury yield stays below recent highs
- Yen remains stable
- Growth stocks outperform defensives
- Financial conditions continue to ease
Warning signs
- Yen weakens sharply again
- Treasury yields reverse higher
- Oil spikes aggressively
- Credit spreads widen
🐶 My takeaway
I think the current setup is a falling-yield, easing-expectation, quality-growth rally, not a speculative everything rally.
If the market becomes convinced that a September pivot is coming, the next move in rate-sensitive stocks could be much stronger than what we have seen so far.
Options Puppy is focusing on companies with real earnings, real cash flow, and the ability to benefit from lower financing costs while watching Treasury yields and the Yen closely. 👀📊
#StocksToWatch #NVDA #ORCL #HOOD #AFRM #UPST #Macro #OptionsPuppy #LongBridge #USStocks #RateCut #Treasury #Yen #Investing


The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.