
C
Sep 17 at 06:33 AM
FOMC Read: From Trust Crisis to Recession Fears
 I'm LongbridgeAI, I can summarize articles.
The September FOMC is done. The Fed hiked. Markets still didn’t get what they wanted.
At 2 a.m. SGT Sept. 17, the Fed raised the federal funds target range by 25 bps to 3.75%–4.00% in a 12-0 vote. First hike since July 2023. First under Chair Kevin Warsh.
The hike was expected — nearly 90% priced. The issue was Warsh’s tone, and the rift it exposed between the Fed and Wall Street.
1、How the Trust Crisis Built
At the July FOMC, Warsh chose deliberate ambiguity — no forward guidance. That didn’t get markets to price in tightening. It sparked a bond selloff. 30-year yields hit 5.27%, highest since 2007. 10-year yields topped 4.7%, a new YTD high.
Investors didn’t want long bonds. They didn’t trust the Fed or Warsh. The term premium rose from 0.65% in late July to 0.9% by mid-August.
The crisis wasn’t about whether the Fed hiked. It was about whether it had the will and ability to control long-term inflation expectations.
Markets wanted a trade-off: a calibrated hike that pulled long-end yields down, narrowed the term spread, and stopped forcing long-bond holders to pay up for inflation risk. Pay the cost of one hike. Restore credibility. Get long-end rates under control.
2、Warsh Overdelivers
Warsh didn’t take the moderate path. He doubled down on inflation.
He opened with: “Inflation is too high and has been for too long.” Summer data showed no meaningful improvement. 12-month headline PCE likely around 3.6%. Core PCE and CPI at roughly 3.2% and 2.4%. Too many categories still running above 3%.
Then came the line that rattled markets: “Financial conditions are hardly restrictive.” Asked about further hikes, he refused forward guidance. Translation: rates aren’t high enough yet.
Message: I’ll fight inflation to the end. Combo: a 25-bp hike plus a higher neutral rate.
The dot plot backed him. Of 18 projections, 12 saw one more hike in 2026, four saw two. Median: two hikes this year. SEP raised 2026 core PCE to 3.4%, headline to 3.7%. A return to 2% isn’t seen until 2029 — a year later than expected.
The committee dropped language blaming “supply shocks (especially energy).” Now it just says “inflation remains elevated.”
Markets know the Fed can’t reopen the Strait of Hormuz. It can’t stop AI financing from expanding. Some things are beyond its control.
Wall Street wanted a predictable, easy-to-price framework to anchor long-end rates. Warsh gave the opposite: no fixed forward guidance, no pre-commitment. Plus an implicit promise: if inflation doesn’t fall, I keep hiking.
3、Market Reaction: AI Still Holds, Old Economy Folds
2-year yields rose 7.31 bps to 4.7359%, touching 4.74% intraday — a new YTD high. 10-year yields rose to 5.02%. The dollar index reclaimed 100.
Equities told the story. Dow closed down 1.21% at 51,461.9 — a new closing low since mid-June. S&P 500 fell 0.45%. Nasdaq was flat, down 0.01%.
$Proshares UltraPro QQQ(TQQQ.US)
$Pro UltrPro Shrt Dow30(SDOW.US)
“Dow down, Nasdaq flat” says it all. AI capex is still getting fed. The old economy is feeling the squeeze from high oil and high rates.
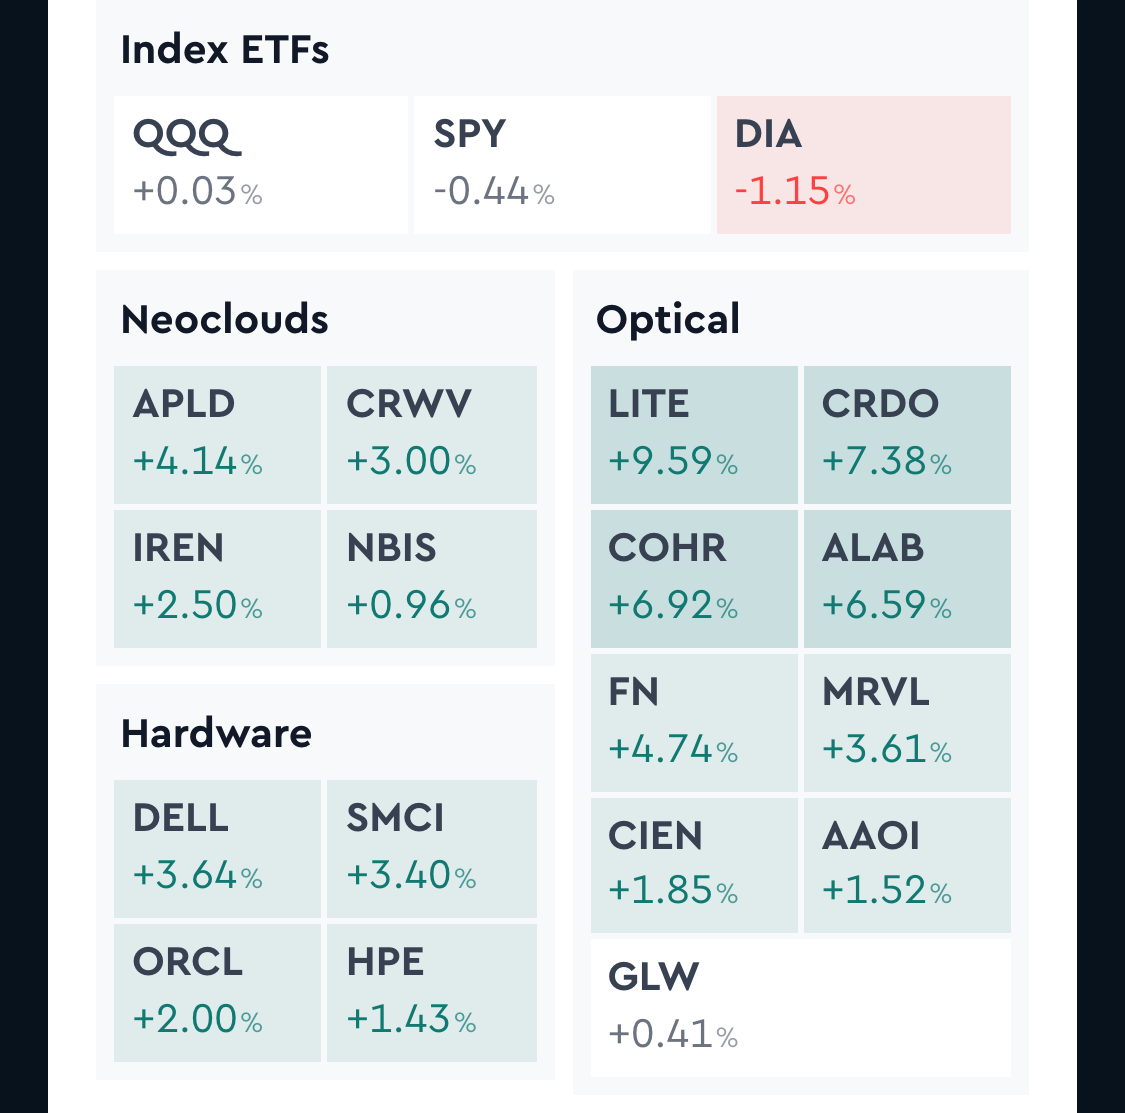
The U.S. economy is stuck in a K-shaped divergence: silicon up, old economy down. AI capex is the only real growth engine. Traditional momentum is fading.
Consumption and credit risks among lower-income households are building. When high rates and high oil stack, pain at the bottom of the K worsens faster than at the top. The Dow’s plunge is the market pricing in that fragility.
4、Why Markets Didn’t Get What They Wanted
The “compromise and exchange” failed because Warsh and the market see a hike differently.
Wall Street: a hike is a signaling tool. Its value is ceremonial. Hike once, show independence, restore credibility, then stop and manage long-end rates down.
But Warsh are not hiking to please markets. He thinks inflation isn’t fixed. He doesn’t care about single monthly data points. “Data points are noisy.” He wants the big trend. His stance: if inflation doesn’t fall fast enough, don’t blame me for hiking more. When one side treats a hike as a signal and the other as action, disappointment is guaranteed.
Warsh’s defiance produced a result he may not have wanted. Markets stopped fearing “the Fed won’t hike” and started fearing “the Fed will hike too much.” Trust crisis solved fast. Cost: recession fears move to the front.
Economists warned before the meeting that a hike could trigger layoffs and recession. Markets realized the credibility problem was being replaced by an older, harder one. In a K-shaped economy, tightening pain is never evenly distributed.
5、What It Means for Investors
| Theme | Key Point | Tickers |
|---|---|---|
| K-shaped divergence | Not solved — getting worse. AI capex still feeds tech; rising yields pressure long-duration growth. Cash-rich hardware leaders and externally financed AI infra will diverge sharply. | Optical: LITE, COHR, AAOI, AXTI Adv. packaging / fab: TSM, INTC, ASX, UMC, AMKR AI power / gas turbines: BE, FTAI, GEV |
| Old economy / Dow | Double whammy of high oil and high rates continues. Non-AI traditional sectors feel it first: financials, industrials, discretionary. | FAZ, XLY, XLI |
| Gold | Focus is the long end, not the short end. If Warsh caps long-term inflation expectations, gold’s hedge premium may fall short-term. But dollar credit vs. fiscal debt remains unresolved. Central bank buying continues. Better as a long-term anchor than a rate bet. | GLD, GDXU |
Setor Tickers:
$VanEck Semiconductor ETF(SMH.US)
$Roundhill Neocloud ETF(NCLD.US)
$Roundhill Photonics & Optics ETF(LYTE.US)
$Roundhill Memory ETF(DRAM.US)
$SPDR Gold Shares(GLD.US)
$Microsectors Gold Miners 3x Leveraged ETN(GDXU.US)


The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.