
<p>Behind the Breakthrough of Inter-Institutional REITs: Front-End Acquisition of Power Stations, Back-End Sale of Shares, A New Assembly Line Has Been Established</p>
 I'm LongbridgeAI, I can summarize articles.
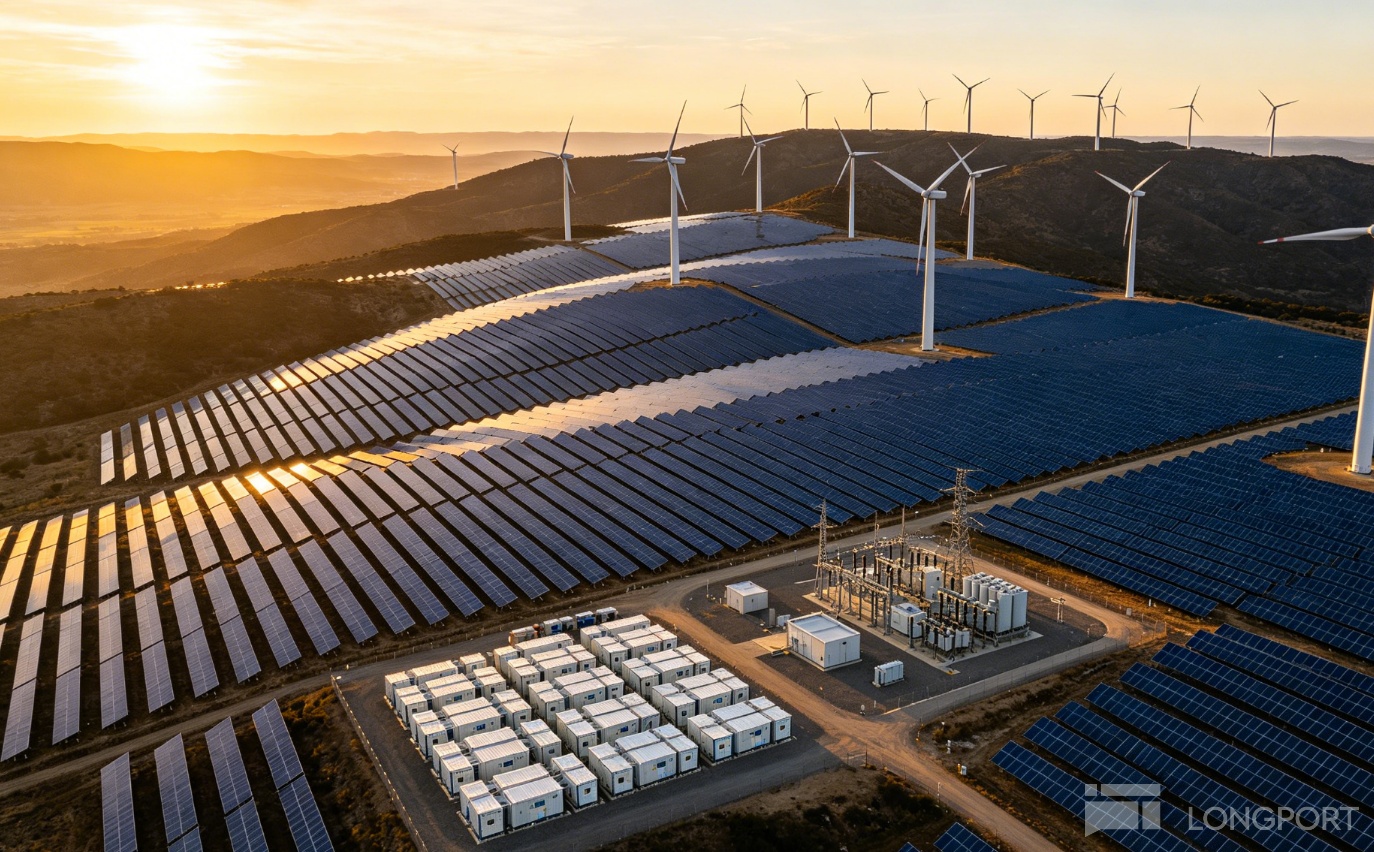
On September 7, Brookfield announced via its official WeChat account that its Brookfield China Renewable Energy Fund (BCRF) has launched its first round of fundraising, with an expected scale exceeding RMB 12 billion. The related signing ceremony was held in Xiamen on the eve of the opening of the 26th China International Fair for Trade in Investment. New China Life plans to contribute RMB 4 billion, accounting for approximately one-third of the first-round target. The two parties signed an investment agreement; other investors have not yet been disclosed, and fund closing is subject to certain conditions and approvals.
This will be Brookfield's first RMB-denominated energy fund focused on the Chinese market. Its investment mandate is clear: it will only acquire operational wind, solar, and storage assets backed by long-term contracts, avoiding new projects.
Around the time this fund was unveiled, institutional interbank REITs continued to gain traction on exchange project information platforms. On August 20, Bicheng Energy completed the first expansion of its distributed solar REIT. On August 27, JinkoSolar disclosed a plan to apply for an institutional interbank REIT using 34 wholly-owned project companies and 57 commercial and industrial distributed PV stations under its portfolio, with a total installed capacity of approx. 298 MW. On September 4, the Kai Xian New Energy RMB 200 million institutional interbank REIT, managed by Xingzheng Asset Management, was accepted by the Shenzhen Stock Exchange. Also on September 7, a smaller RMB 134 million deal from Haiyan, Zhejiang, entered the acceptance queue.
One timeline charts 'acquiring power stations' in the primary market, while the other tracks 'selling stakes' in the securitization market. For the past two years, they moved independently; since early summer this year, they have finally synchronized. The institutional interbank REIT market, which crossed the RMB 100 billion cumulative threshold in late July, lists energy as its third-largest underlying asset class and one of the most active sectors for new deals recently. To understand why Brookfield chose this moment to raise RMB capital, one must first understand how this chain operates.
A tariff document gives pricing to existing assets
The catalyst for this shift was a policy directive on electricity tariffs.
On January 27, 2025, the National Development and Reform Commission (NDRC) and the National Energy Administration (NEA) issued Document No. 136, promoting the marketization of renewable energy feed-in tariffs. It drew a line at June 1 of that year: existing projects commissioned before this date would transition via a difference mechanism, while incremental projects after this date would enter market-based bidding, gradually phasing out the longstanding guaranteed volume and price model.
Superficially, this appears bearish: tariffs are no longer locked, making future cash flows from power stations uncertain. Yet precisely this uncertainty pushed the industry in another direction.
On one side, new project development cooled significantly. NEA data shows national grid-connected PV additions reached 71.768 GW in H1 2026, down approx. 66% YoY; centralized capacity fell by roughly 70%, while distributed dropped 62.6%. Within distributed segments, C&I additions plummeted 76.6% YoY to 20.39 GW—the steepest decline. Residential installations fell 15% to 21.831 GW. The residential slowdown followed a pattern: Q1 saw an 89% YoY surge driven by rush-to-install ahead of the June 1 cutoff, but demand front-loading led to cumulative negative growth in H1.
Wind faced similar base-effect digestion. H1 wind additions totaled 38.62 GW, down approx. 25% YoY, though cumulative capacity still grew 18.5%. Storage presented a different picture: by end-June, national operational new-storage capacity hit 153 GW (+61% YoY). However, CNESA reported H1 additions of 21.81 GWh, with power scale declining approx. 18% YoY for the first time, signaling a slowdown in hyper-growth.
The root cause lies in Document 136: post-June 1 incremental projects must compete in spot markets, preventing pre-locked returns. Since C&I rooftops rely heavily on self-consumption, they are most sensitive to tariff and curtailment risks, causing investors to pull back first. Developers are unwilling to continue leveraging high debt to keep new plants on their balance sheets as in previous years.
On the other side, already-operational plants with long-term PPAs offer predictable cash flows, becoming attractive targets for institutions. Especially small-to-medium holders lacking financing and trading capabilities prefer to lock in gains amid tariff volatility and industry consolidation. Sellers thus emerged in bulk.
Previously, renewable profits concentrated in two areas: upstream manufacturing via module shipments, and developers via capacity expansion. As manufacturing margins compressed and new-project returns became uncertain, value shifted to an previously overlooked segment: who holds plants long-term, and who can transform them into tradable assets. Subsequent M&A funds, institutional REITs, insurance capital, and foreign players all positioned around this nexus.
Brookfield is no stranger to China. It opened a Beijing office in 2013, formed its China energy team in 2017, partnered with GLP in 2018 for logistics rooftop PV, and signed a 25-year fixed-tariff PPA with BASF in Zhanjiang in 2022. It currently manages approx. 15 GW of energy assets in China. Months prior, it co-sponsored a joint venture with CICC to structure two Shanghai inner-ring commercial rental apartments into an institutional interbank REIT. Approved by exchanges on April 28 and launching its first tranche of RMB 800 million on June 5, this was the nation's first 市场化长租公寓机构间 REIT. The distinction? Previously, it used globally raised USD capital; now, fundraising, contributions, and future exits are entirely within the RMB onshore system—a process it has already navigated once.
Where does acquisition capital come from?
Acquisition of existing plants isn't new to 2026. Earlier, development funds targeted new builds; GLP partnered with the National Green Development Fund and NEA Group subsidiaries to establish a nearly RMB 20 billion green energy investment platform, while Zhonglian Fund launched a new energy infrastructure development fund in 2023. What surged this year, however, were M&A funds specifically targeting existing assets. Differences in capital sources and structures reveal the strategies of various player types.
The most typical model is off-balance-sheet M&A funds by industrial players. On July 23, Sungrow Power Supply announced that its subsidiary, Sungrow New Energy, contributed RMB 199 million alongside Huatai affiliates to establish Suzhou Huaxu New Energy Fund, with a subscribed total of RMB 1 billion. Huatai Asset Management contributed RMB 800 million (80%), Huatai Baoli served as GP contributing RMB 1 million, and Sungrow New Energy held 19.9%. The fund has a 30-year lifespan.
The terms rigidly define eligible assets: priority given to wind, centralized PV, and storage, with single-unit scales exceeding 200 kW, minimum IRR of 8%, and annual base dividends of at least 5%. Priority is also given to grid-connected plants recommended by Sungrow New Energy. A five-member investment committee is entirely appointed by the GP, giving Sungrow no veto power, and the fund remains off-listed.
In essence, Sungrow leveraged under RMB 200 million to control RMB 800 million in insurance capital, acquiring mature plants from its own portfolio. This removes assets and liabilities from its books while continuing to collect O&M and trading service fees. On August 24, Huatai Asset disclosed that this RMB 800 million originated from a planned carbon-neutral green energy equity investment plan.
Insurance companies acting as anchor LPs represent another structure. The Beijing Jingneng New Energy M&A Fund, established in Haidian District in 2025, has registered capital of RMB 2.501 billion. Taikang Life subscribed RMB 1.75 billion (69.97%), while the Jingneng group contributed approx. 30%. Jingneng Tongxin serves as GP, focusing exclusively on energy M&A.
Some operators built layered fund networks themselves. In September 2023, Bicheng Energy partnered with GLP Capital (GCP) to create Luoneng Capital. Luoneng's Phase I new energy development fund closed in June 2024 at approx. RMB 2 billion, planning RMB 10 billion in total investment. In January 2026, it partnered with Touzhong Asset and Luoneng Capital to launch a C&I solar-storage M&A fund, completing Phase I fundraising and initial closings. In July, it joined two Chengdu state-owned entities to form a RMB 1 billion M&A fund, establishing its Southwest HQ in Pengzhou. By early September, it partnered with Siegrist New Energy, Luoneng, and Touzhong to create a RMB 500 million grid-side independent storage development fund. Equity financing advanced simultaneously: on September 2, Bicheng announced completion of a multi-hundred-million RMB Series C1 round led by Zhonghai Fund, with participation from Chengdu Communications Investment and Yankuang Capital. In four years, cumulative financing exceeded RMB 2 billion, with grid-connected capacity nearing 2 GW.
Concord New Energy followed a similar path, partnering with Taikang and China Merchants Bank affiliates in December 2025 to establish an RMB 1.811 billion fund, with initial delivery of 401 MW of wind assets.
State-owned enterprise integration also progressed: earlier this year, Inner Mongolia Electric Power, a subsidiary of State Energy Group, acquired 1.6 GW of wind from its controlling shareholder for RMB 5.336 billion. In June, Yankuang Energy, under Shandong Energy Group, invested RMB 16.415 billion to merge its thermal-wind-solar-storage-sales integrated power platform into the group.
Foreign acquisition of onshore plants didn't start with Brookfield. Macquarie's Asia Infrastructure Fund II invested in private wind developer Shanghai Sine in 2017, securing 50% joint control, growing capacity from 222 MW to 864 MW before exiting via buyback in December 2021. In September 2024, JinkoSolar disclosed a transaction with New York-headquartered Aviva Capital, which purchased a 268 MW residential PV package across Henan, Jiangxi, and Jiangsu. Both parties established an investment vehicle, marking the first introduction of an international fund into China's residential PV sector. In January 2025, Saudi ACWA Power partnered with Sungrow's subsidiary to commission 132 MW of PV in Guangdong (comprising three sites) and signed an initial 200 MW wind 组合 with Mingyang Smart Energy.
In these early cases, foreigners typically used offshore capital or joint ventures with local developers. Brookfield's fund differs in that fundraising, contributions, and future exits are anchored in the RMB onshore system, with domestic insurance capital as the cornerstone LP.
Tracing these lines, insurance capital's role ascends step-by-step. Initially limited to subscribing to stakes; later, Pacific Asset Management acted as both manager and anchor investor for Trina Home, Towngas Smart Energy, and Haier projects; then Taikang gained controlling interest in the Jingneng fund, and Huatai Asset held 80% in the Huaxu fund. Now, New China Life's proposed RMB 4 billion contribution places an anchor LP role with a foreign GP.
Insurance capital's willingness to advance stems from its liability structure. New China Insurance's H1 2026 report showed investment assets exceeding RMB 1.9 trillion and green finance investments surpassing RMB 110 billion as of end-June. Long-duration life insurance funds seek stable dividend-paying assets over 20-30 years; the cash flow cycles of operational plants align perfectly.
Scanning the investment mandates of these M&A funds reveals a common refrain: only acquire existing, grid-connected assets with long-term contracts and good curtailment profiles. Almost none are structured for new projects.
In August, exit channels cleared first
Front-end confidence in deploying billions to continuously acquire plants relies on a premise: back-end exits must function, recycling cash for subsequent batches. Prior to August 2026, 'exits' were sporadic 个案; only after summer did they become true channels.
Regulatory frameworks arrived first. On July 24, Shanghai and Shenzhen exchanges synchronously revised asset securitization guidelines, formally naming the former 'holding-type real estate ABS' as Institutional Interbank REITs. They clarified four equity attributes: no reliance on external credit enhancement, pari passu structure, no mandatory repurchase, active management, distribution ratios ≥90%, and codified expansion mechanisms. Rules and mechanics were defined in one go.
By August, acceptance, listing, and expansion lines converged densely.
On the acceptance front, volume and variety rose together. Haier's RMB 5 billion project was accepted by SZSE on July 27; next day, Yichu Digital Intelligence's RMB 675 million independent storage project was accepted. On August 3, Caitong-Zhengtai Aneng's RMB 6.662 billion residential PV project was accepted by SSE, set by Zhengtai Aneng Digital Energy (Zhejiang) Co., Ltd., breaking the record for largest accepted scale in new energy institutional interbank REITs; it pivoted to existing asset revitalization after terminating its spin-off listing in Sept 2025. Same day, Huanghe Tianwei's RMB 304 million storage project from Shanxi coking coal sector was accepted.
On August 17, Guolian Asset Management's RMB 230 million Jiangsu Guokai project was accepted, with Suqian local SOE as original rights holder. On August 28, CITIC Securities-managed SPIC-Huanghe Hydro Water-Solar Complementary Project was accepted, with SPIC's Huanghe Upstream Hydropower Development Co. as originator. Planned issuance of RMB 6.3 billion makes it another mega-clean energy deal exceeding RMB 6 billion. By early September, a smaller RMB 134 million Haiyan deal entered acceptance, showing product 下沉 to county levels.
On the listing front, first-tranche storage and CSP projects landed. On April 28, Caitong AM-First Solar project was issued and listed on SSE on June 9, sized at RMB 451 million, underlying a 200 MW/800 MWh grid-side independent storage station in Jiuquan, Gansu, marking the nation's first independent storage institutional interbank REIT. Molten salt CSP's first deal also progressed: Zhejiang Zhongguang New Energy's RMB 750 million project passed SSE review on July 3, awaiting listing.
PV projects followed in August. On August 4, Shanghai Hongzuo New Energy's RMB 160 million distributed PV project was established, with bank wealth management products subscribing directly upon issuance. On August 18, ICBC-RiTou-Hangtai Digital Intelligence's RMB 383 million project issued, with ICBC Wealth Management as core investor.
The signal from expansions is more critical. On August 20, Bicheng Energy's RMB 297 million first-tranche distributed clean energy institutional interbank REIT (established late 2025, underlying ~130 MW) completed its first expansion, raising cumulatively over RMB 800 million and expanding underlying assets to ~400 MW. Transitioning from 'issuing first tranches' to 'continuously injecting new plants' signifies true asset rotation.
An earlier deal connected head and tail. Issued April 15 and listed May 28 on SSE, Shengang-Zhongliande New Energy Institutional Interbank REIT was only RMB 114 million, underlying distributed PV on industrial/commercial rooftops. Its uniqueness lay in the originator: Suzhou Zhongliande New Energy itself was a Pre-REITs real estate investment fund. A front-end fund nurturing/acquiring assets ultimately exited via institutional interbank REIT. Development funds nurture assets, M&A funds acquire them, REIT channels exit them—closing the full 'fundraise-invest-manage-exit' loop on new energy assets.
One level higher lies public REITs. Currently, approx. ten clean energy public REITs cover hydro, offshore wind, onshore wind, and centralized PV. Late July to early August saw listings of AVIC-CNNC Hui Neng (two wind farms, 196 MW combined) and Huatai Three Gorges New Energy (Dalian Zhuanghe III offshore wind, 298.8 MW), both receiving over 100x subscription multiples during issuance.
Industry volume scaled up. According to Brilliance Ratings, H1 2026 saw 24 institutional interbank REIT issuances totaling RMB 33.013 billion, volume approx. 11x YoY, scale growing approx. 24x. Energy infrastructure accounted for RMB 6.401 billion (19.39%), the third-largest underlying asset. By late July, cumulative scale broke RMB 100 billion.
Brookfield's fund targets wind, solar, and storage—all three categories have securitization precedents: wind earliest (Taikang Asset-Caitong-Vision New Energy project, RMB 285 million, underlying 100 MW Hanjin wind farm, first holding-type real estate ABS for clean energy); solar via Bicheng/Zhongliande; storage via First Solar in April 2026 and Zhongguang CSP in July. It wasn't Brookfield igniting the track; rather, exit channels cleared first, validated by transactions, enabling front-end billion-scale, platform-style M&A funds to truly form. What it seeks isn't just plants, but a proven exit pipeline.
The final hurdle is tariffs
Channel closure is factual, but channels solve 'who buys assets, how to monetize,' failing to answer: how much power will these plants generate, and at what price?
The coldest water came from one of the largest foreign operators in China, Singapore's Keppel Seghers. As of Sept 2025, its China renewable capacity totaled approx. 9.4 GW across 16 provinces. H1 2026 results showed global renewable base net profit down 48% YoY, with China region profit dropping approx. 55% due to onshore wind curtailment rising to mid-single digits, market-driven tariff reductions, cancellation of onshore wind VAT refunds, and weak wind/solar resources. This isn't isolated: NEA data shows national average wind utilization rate was 90.9% in H1, with utilization hours down 170 YoY.
Even experienced foreign holders face this reality, proving that internal rates of return calculated at acquisition must ultimately be realized through annual utilization hours and trading results. Hence Brookfield, Zhonglian, and Bicheng repeatedly emphasize their O&M and trading capabilities.
Another layer: this fundification is essentially redistribution of existing stock, not an engine for increment. As noted, these M&A funds almost exclusively buy grid-connected assets, while C&I distributed additions fell 76.6% YoY in H1. Existing stock gets repriced, transferred, and securitized repeatedly, but who builds new plants and with what capital remains unanswered by this fund cycle. Development funds persist, but 2026's denser capital activity clearly landed on the existing side.
Then there's concentration. Thresholds like 200 kW single unit, 8% IRR, and grid-connected status exclude many sub-100 MW small holders, positioning them primarily as sellers. Assets concentrate from dispersed developers toward top operators, insurance capital, and foreign institutions. Whether primary market acquisition pricing can sustainably align with secondary market REIT distribution yields and volatile tariffs will test this model going forward.
Returning to Brookfield's deal itself, it remains 'in progress': RMB 12 billion is the first-round target, RMB 4 billion is New China's proposed contribution, initial acquisition targets undisclosed, and closing requires conditions/approvals. Track formation and fund success are two separate matters.
Previously, industry money flowed mainly to manufacturing and development ends; now holding/operation and securitization stepped to the forefront—a recent evolution. On the signing table in Xiamen on Sept 7, one side sat Brookfield managing approx. $1.2 trillion in assets, the other New China Life holding over RMB 10 trillion in investments. They aren't trading modules or capacity numbers, but twenty years of future electricity fees from each plant. Brookfield Energy APAC Head Cheng Jingyao used the phrase 'prudent and 稳健' in the press release.
This capital cycle closed in August. How fast and long it turns depends not on how much the fund raises, but on how much each kWh sells for.


The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.