
[HK IPO] Robotechnik, the world's No.1 silicon photonics equipment provider, pivoting from photovoltaics to silicon photonics
 I'm LongbridgeAI, I can summarize articles.
Hello, I'm Lu Xian. Researching the investment field and sharing overseas information.
Yesterday I shared [Hong Kong IPO] JWOCETEC, a global leader in automotive electronics PCBs. Today, I'm sharing another semiconductor equipment target — Robot Technology, which manufactures intelligent manufacturing equipment, listing on September 29. This company is already listed on the A-share market; this time it's issuing H-shares in Hong Kong, ranking first globally in silicon photonics intelligent manufacturing equipment. Let's break it down.
I. New Share Issuance Overview
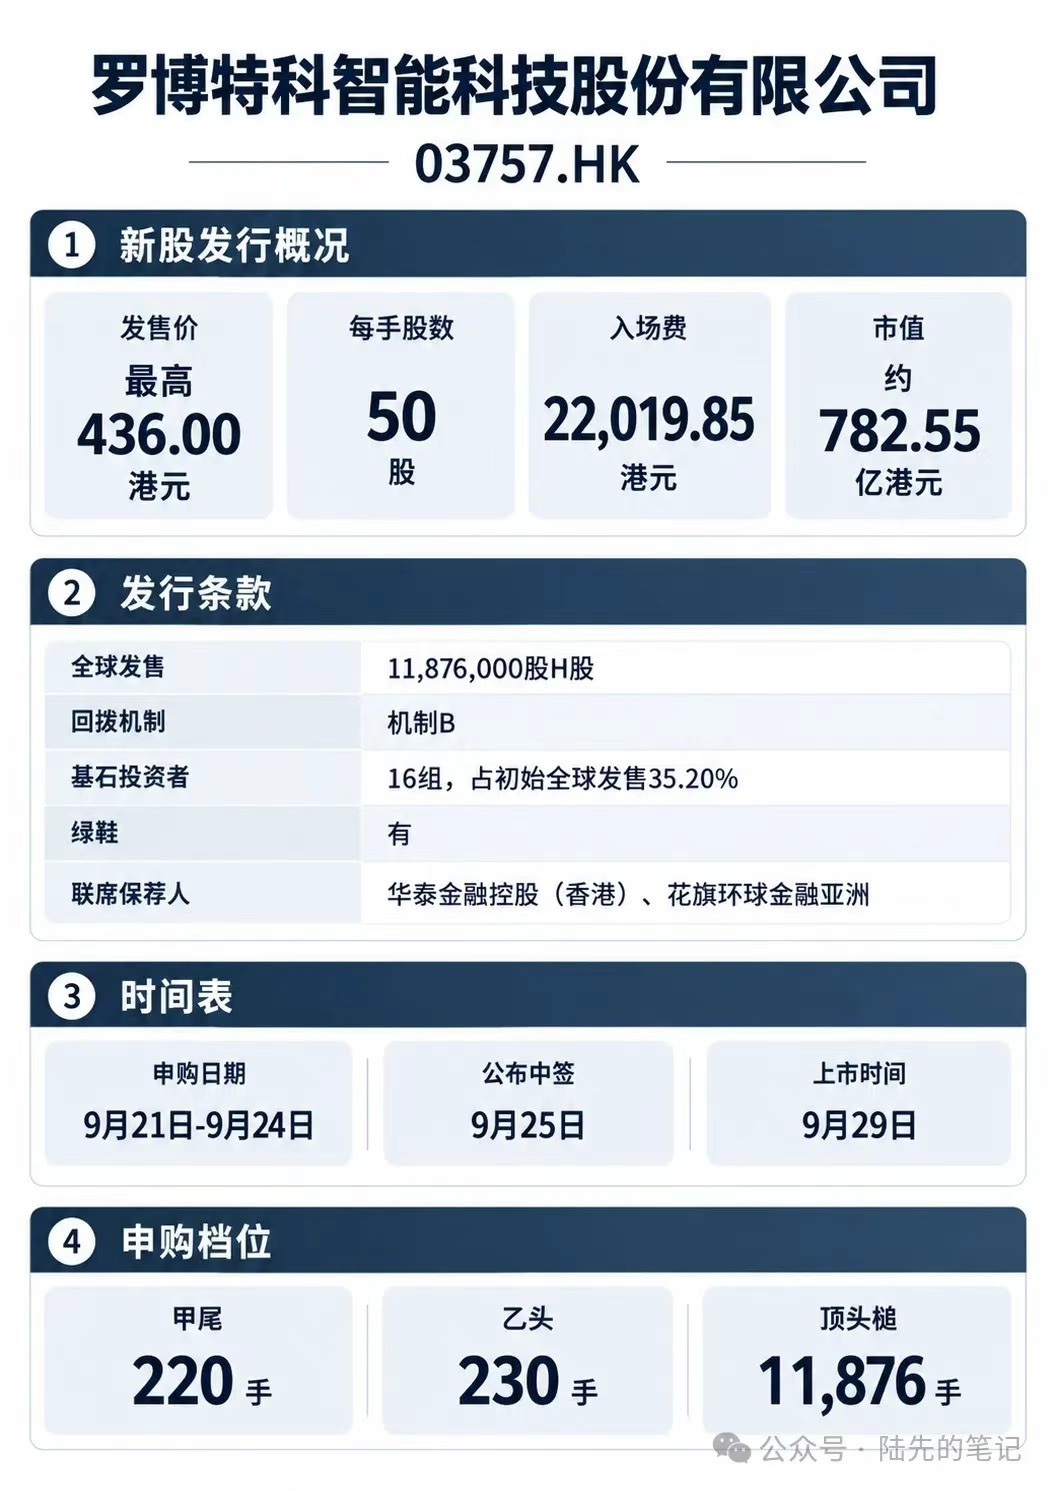
Company Name: Robot Technology Intelligent Science & Technology Co., Ltd. (03757.HK)
Offer Price: Up to HK$436.00
Lot Size: 50 shares
Minimum Investment: HK$22,019.85
Market Cap: ~HK$78.255bn
Global Offer: 11,876,000 H-shares
Cross-allocation Mechanism: Mechanism B
Cornerstone Investors: 16 groups, representing 35.20% of the initial global offer
Greenshoe: Yes
Joint Sponsors: Huatai Financial Holdings (Hong Kong), Citi Global Markets Asia
Subscription Period: Sept 21 - Sept 24
Allotment Results Announcement: Sept 25
Listing Date: Sept 29
Sub-category Tail: 220 lots
Sub-category Head: 230 lots
Top Bidder: 11,876 lots
II. Company Fundamentals Analysis
Robot Technology focuses on intelligent manufacturing equipment with two product lines. One is photovoltaic (PV) manufacturing solutions, used in PV cell and module production lines. The other is silicon photonics assembly and testing equipment, used in the manufacturing and testing of silicon photonics modules, optoelectronic components, and photonic chips. The latter is currently the core focus of capital markets.
In terms of industry position, based on 2025 revenue, Robot Technology ranks first globally in the silicon photonics intelligent manufacturing equipment market, with a market share of approximately 20.5%. This silicon photonics equipment track is directly tied to AI computing power. Data center optical modules are evolving from 400G to 800G and 1.6T. Traditional optical modules rely on discrete component assembly, while silicon photonics solutions use semiconductor process integration, offering lower costs and reduced power consumption. Demand for upstream equipment will follow the expansion of optical module production, which is why Robot Technology has caught the market's attention.
The revenue structure has changed dramatically. In 2023, PV manufacturing solutions accounted for 95% of revenue, with silicon photonics equipment at zero. In 2024, PV dropped to 92.5%, while silicon photonics contributed RMB 50.18mn, accounting for 4.5%. By 2025, PV fell to 45.6%, and silicon photonics rose to RMB 439mn, accounting for 46.3%. In just two years, silicon photonics went from zero to half of the business. Meanwhile, PV business shrank from RMB 1.49bn to RMB 433mn, a 70% decline. This is driven by overcapacity in the PV industry and a significant contraction in equipment procurement, forcing Robot Technology to transform. The growth in silicon photonics has effectively offset the decline in PV.
Looking at financial data over three years: Revenue was RMB 1.57bn, RMB 1.104bn, and RMB 949mn in 2023, 2024, and 2025 respectively, declining for two consecutive years. Gross profit decreased from RMB 343mn to RMB 328mn, but the gross margin improved from 21.9% to 34.5%, indicating a shift towards higher-margin products, as silicon photonics equipment margins are significantly higher than PV equipment. Net profit fell from RMB 79mn in 2023 to RMB 63mn in 2024, and turned into a loss of RMB 45mn in 2025. The main reasons for the loss are insufficient absorption of fixed costs due to the shrinkage of PV business and high early-stage investments in silicon photonics. R&D expenses increased from RMB 86mn to RMB 106mn, exceeding 11% of revenue.
Customer concentration remains high. The top five customers accounted for 63.2% of revenue in 2025, with the largest customer representing 19.4%. High customer concentration is common in the equipment industry, and fluctuations in orders from a single client can impact revenue. On the supplier side, the largest supplier accounts for 20.3%, which is relatively diversified.
Use of proceeds: 40% for capacity expansion and improving delivery speed, 20% for product and technology R&D innovation, 20% for strategic investments and acquisitions, 10% for establishing a global sales and service network, and 10% for working capital. Based on the maximum price, net proceeds are approximately HK$4.961bn. The company paid dividends in the three years prior to listing, though amounts were small. Cornerstone investors are locked for six months.
III. IPO Subscription Analysis and My Strategy
The core highlight for Robot Technology is its #1 global position in the silicon photonics equipment track, combined with the demand for optical module equipment driven by AI computing power expansion. The drag from PV business is being offset by silicon photonics, which exceeded PV in proportion in 2025, signaling the completion of its transformation. 16 cornerstone subscriptions account for 35.20% of the global offer, indicating moderate-to-strong lock-up strength. With dual sponsors Huatai and Citi, plus a greenshoe option, the market stabilization configuration is robust.
Fundamentals are decent, but risks are also obvious. Revenue has declined for two consecutive years, and the company posted a loss in 2025. The valuation implies a market cap of HK$78.255bn, resulting in an extremely high P/S ratio. PV business hasn't yet bottomed out, and whether silicon photonics orders can continue to scale up depends on the expansion pace of downstream optical module manufacturers. If market sentiment had been hotter previously, it might have seen some trading activity.
My strategy: Do not subscribe.
$ROBOTECHNIK(03757.HK)


The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.