

Nebius 3Q26 First Take: Headline numbers were solid, with both growth and profitability beating estimates. GAAP OP turne…
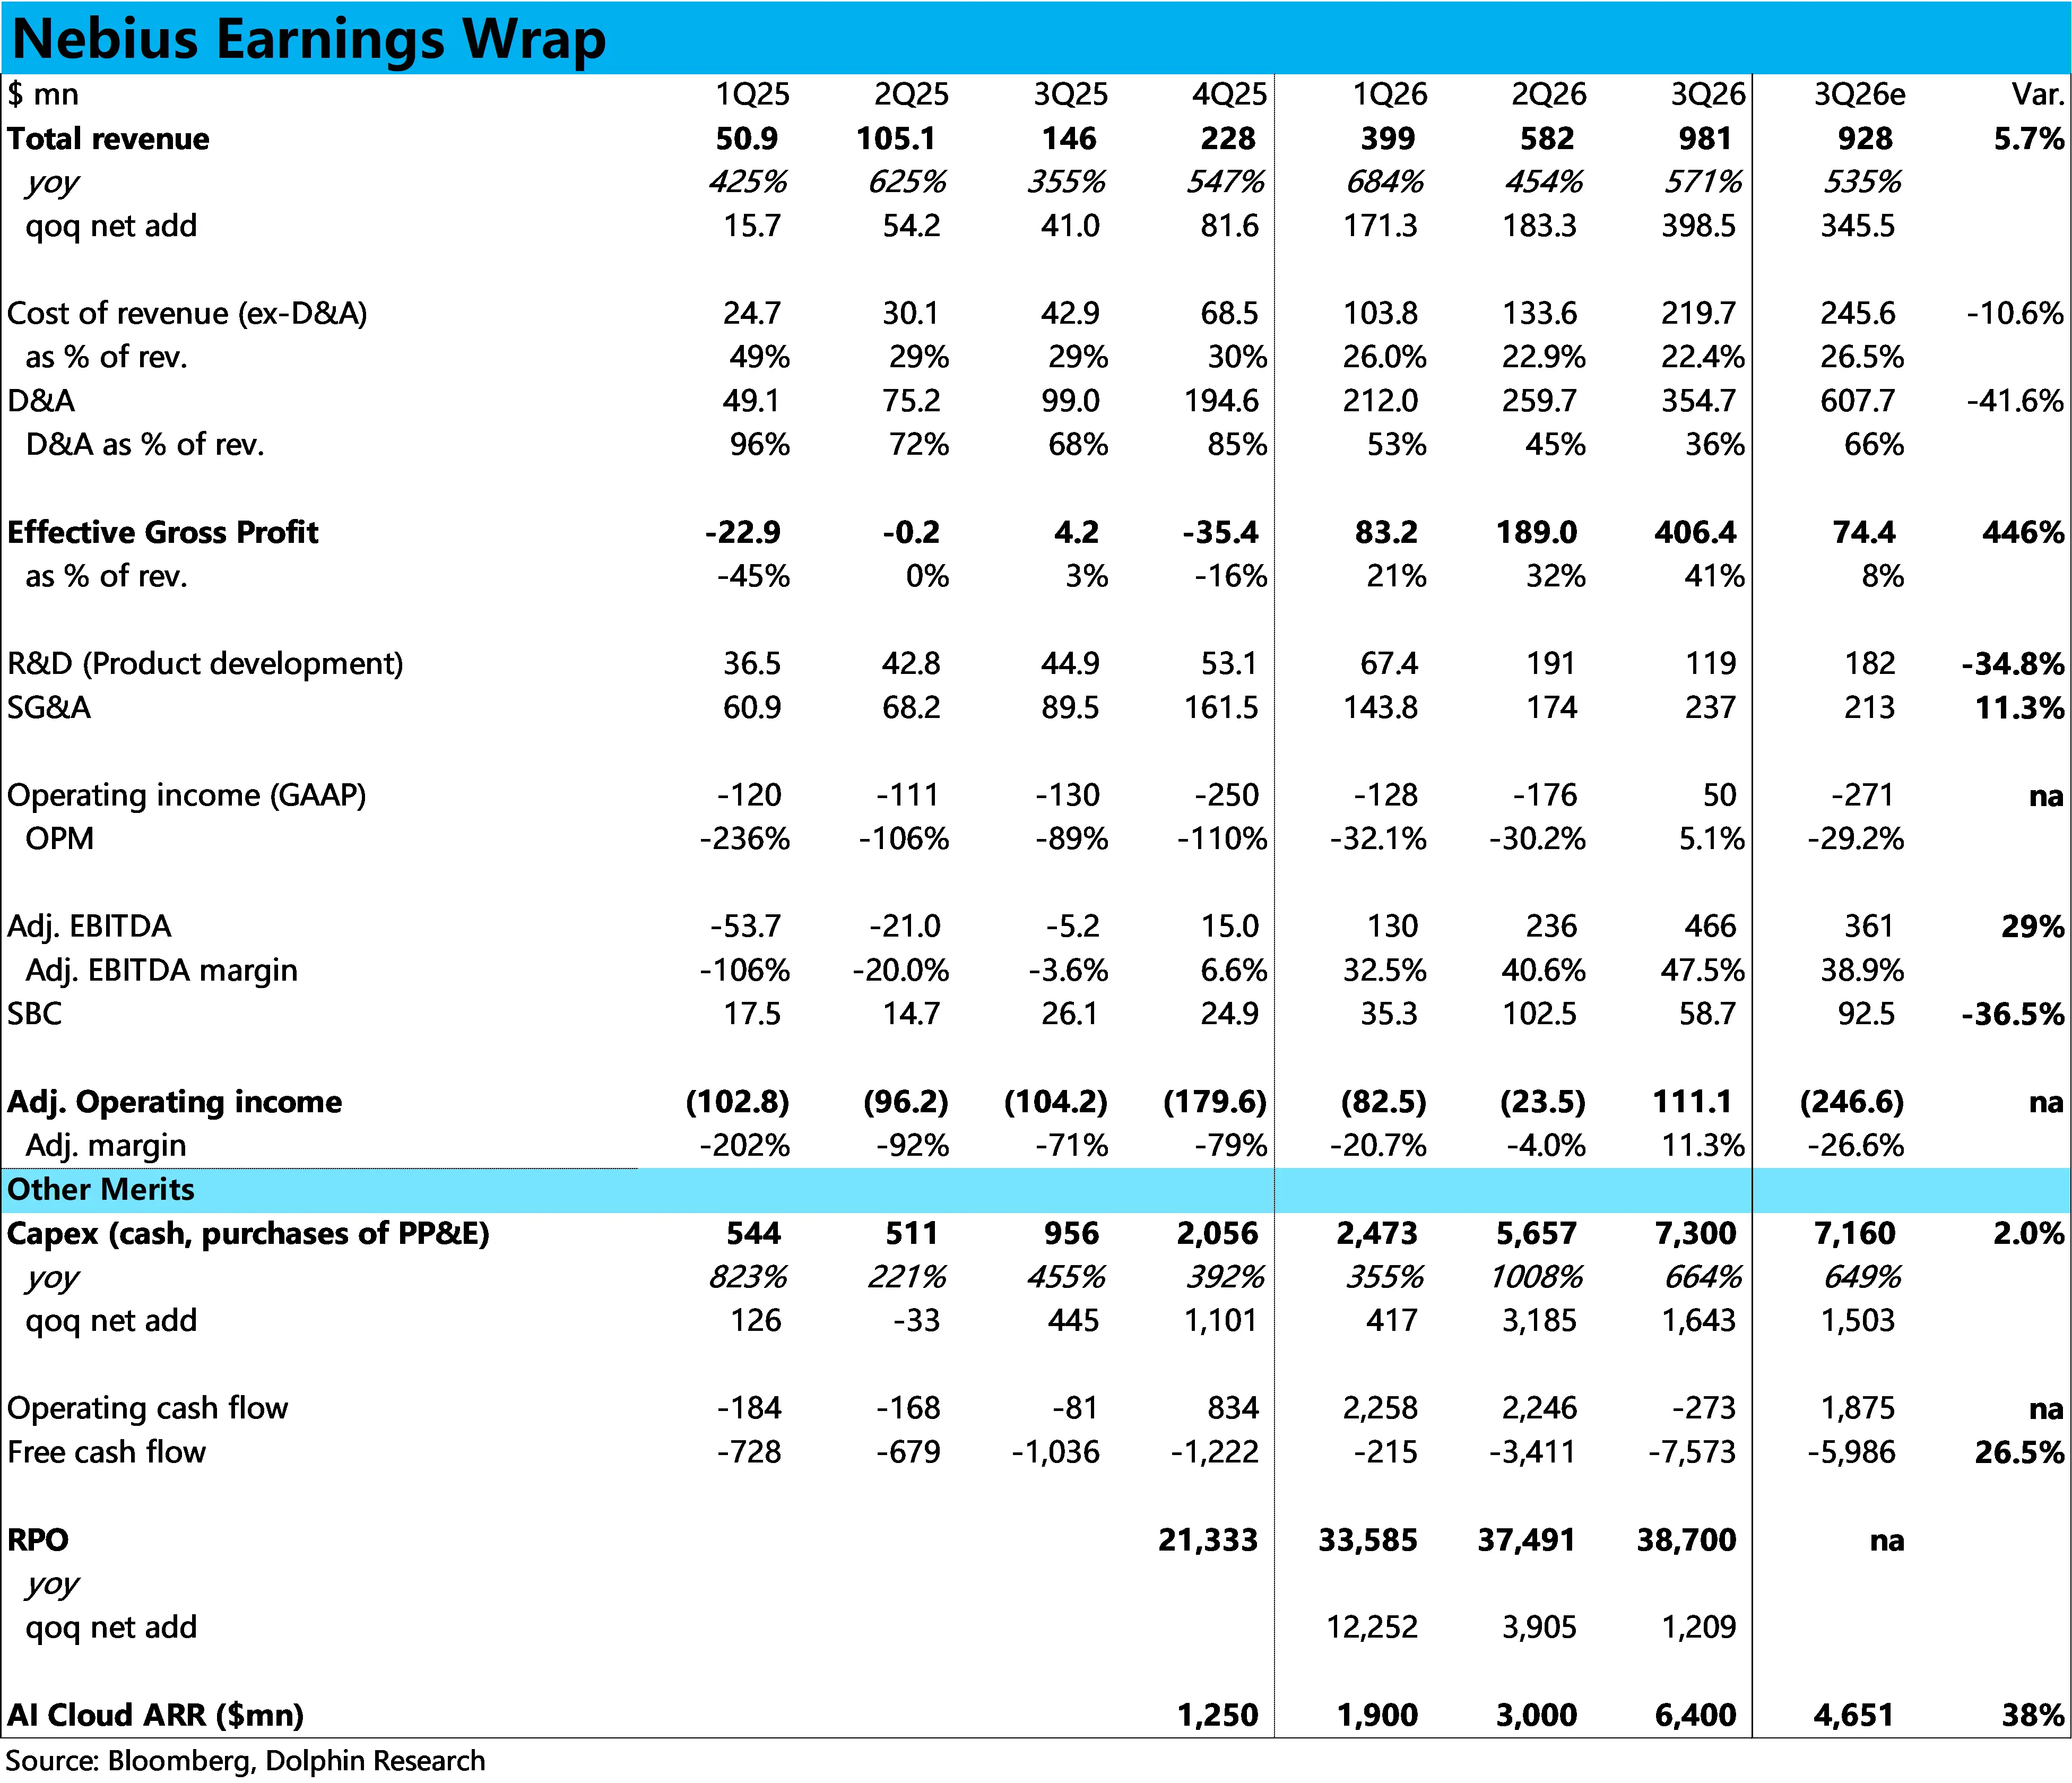
Nebius 3Q26 First Take: Headline numbers were solid, with both growth and profitability beating estimates. GAAP OP turned positive for the first time.
That said, after CRWV’s strong print yesterday, NBIS had already rallied ~15%, front-running a decent quarter. A closer look shows several issues: delayed capacity go-lives dragged the 4Q revenue guide well below consensus; RPO was flat QoQ; and the 2027 outlook was not particularly exciting.
1) Revenue: +68% QoQ, but ~$330 mn was one-off
Revenue came in at ~$980 mn, ~6% above consensus. However, roughly $330 mn was one-off ‘asset-light’ revenue (partners build compute, Nebius provides DC architecture and platform deployment), calling into question the quality of the beat.
2) Capacity go-live: slower; third-party hosted sites pushed to next year
The company said multiple third-party hosted sites are delayed to 1H27. The New Jersey Microsoft project will deliver more than half by year-end, with the remainder pushed to 2Q27; self-built sites are on track and contracts tied to delayed capacity remain intact.
As a result, the 2026 revenue guide was moved to the low end of the $3.0–3.4 bn range, implying 4Q revenue of ~$1.0 bn, ~30% below consensus.
3) Profit: ahead of estimates, but with ‘misleading’ factors
Adj. EBITDA beat by ~29%, with margin at ~47%. GAAP OP was ~$50 mn, turning positive for the first time, but two ‘misleading’ factors were at play.
First, the quarter included sizable one-off asset-light revenue, which likely carries higher margin. Also, D&A ran ~40% below consensus, likely because slower capacity ramps left a large portion of assets not yet in service.
4) Orders and pricing: pricing still rising, but RPO barely grew
New contracts signed this quarter exceeded $25 mn per MW per year (vs. >$20 mn last quarter). However, this was widely anticipated by the market.
Quarter-end RPO was ~$38.7 bn, up just 3% QoQ (~$1.2 bn), indicating few new wins in 3Q. Management noted contracts signed since 3Q total over $12 bn, likely concentrated in 4Q.
5) Cash flow: operating cash flow turned negative; moved to net debt
Capex was ~$7.3 bn, in line with expectations but up nearly 30% QoQ. FCF was about -$7.6 bn, well below consensus.
With cash down slightly and debt up by nearly $5.7 bn, NBIS moved from net cash to net debt of roughly $5.5 bn. The balance sheet deteriorated.
Full-year 2026 capex was raised to ~$27 bn, implying 4Q capex of ~$11.6 bn and a continued step-up. This points to mounting investment and funding pressure.
6) 2027 outlook: revenue in line, capex far above, profitability better
Revenue guidance of $12–13 bn is about 1% below consensus at the midpoint, with conservative build assumptions. Capex of $40–45 bn is ~34% above consensus at the midpoint, and the mix of higher capex vs. average revenue will raise execution-efficiency concerns.
Management said 75–85% of next year’s capex will be covered by customer prepayments and contract-backed financing. Prepayments are estimated at $17–20 bn.
Profitability guidance was also constructive, targeting PBT breakeven in 4Q27 (incl. interest; GAAP not specified), ahead of consensus. $Nebius(NBIS.US)
The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.