
 I'm LongbridgeAI, I can summarize articles.
Usually a consistent beat-and-raise name, $AppLovin.US turned in a rare miss this time. Both the print and guide point to slowing revenue growth, below buy-side hopes. This ties to chatter about weaker ad conversion on AppLovin, making investors more wary on competitive dynamics, and puts the onus on management to explain and restore confidence.
In detail. Key points:
1. Growth continues to decelerate
Q2 revenue grew 53% YoY, but momentum is easing as the base rises, consistent with prior software trends. For H2, the company guided revenue to $2.06–2.09bn, implying a mid-point growth of roughly 47%.
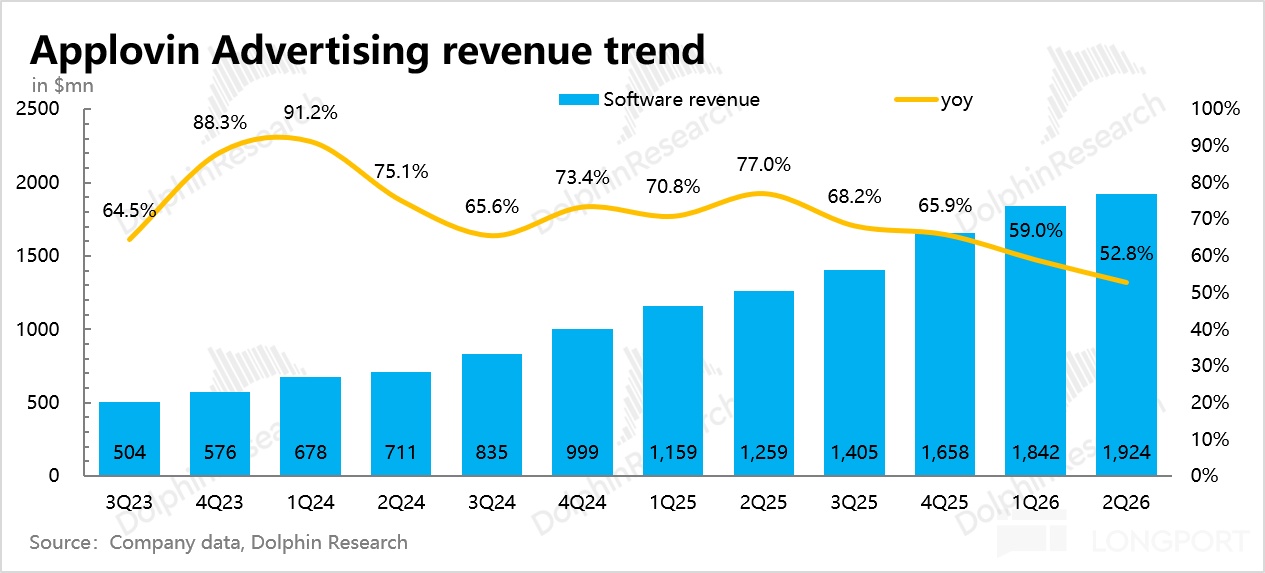
While part of this is natural decel, at an early stage of expanding into e-comm ads, investors would prefer to see faster e-comm ramp to offset the inevitable slowdown in gaming ads. Specifically, sustaining >7% QoQ growth (consistent with >30% YoY) would signal incremental contribution from e-comm on top of 20–30% in gaming.
Backing into the numbers, Q2 grew only 4.4% QoQ and Q3 guide implies +7.6% QoQ. That suggests the June launch of the full self-serve e-comm ad system added limited in-quarter contribution.

2. ROAS edge has been dented
AppLovin’s three-year surge has been closely tied to superior conversion efficiency, second only to Google in third-party ad networks. But Jul tracking from some firms indicates that with eCPM moving higher, supply on AppLovin Max is pleased, while the demand side sees ROAS deterioration.

Meanwhile, Unity’s new Vector system is driving ongoing conversion gains. Meta’s Audience Network returned to iOS slowly in Q1 with underwhelming results, but client feedback in Q2 started to improve, and its own platforms Facebook and Instagram, helped by Advantage+, continue to attract incremental budgets.
As a result, a few sizable agencies cut Max budgets or diverted incremental spend elsewhere. As shown below, AppLovin’s share slipped in Q2, though we also note some rebound so far in Q3; we suggest watching for management’s detail on trends since Q3 began.


3. Margin optimization likely near-term peak
Q2 OP margin was 78%, and Adj. EBITDA margin 84%, both posting their first QoQ downtick. Q3 guide also implies near-term margin pressure.
Given already-elevated margins, plus necessary sales build-out and new tool investments to penetrate e-comm, Dolphin Research had flagged downside margin risk over the past two quarters. That view is playing out.
This is partly a short-term input–output mismatch. Whether margins recover will hinge on stronger feedback from e-comm advertisers.


4. Buybacks: paced by market cap moves
In Q2, as investors realized Meta’s iOS comeback in app ads was slower, the stock rebounded through Apr–May. The company reduced buybacks QoQ and repurchased $550mn in Q2, buying 1.1mn shares at an Avg. price of $500, suggesting a market-cap-management style.
By Q2-end, $1.8bn remained authorized, with $3.1bn in cash on hand; relative to its market cap, that is not large. However, with roughly $1bn FCF per quarter over the past year, there is room to expand the buyback; at present, implied shareholder return from repurchases is modest and insufficient as a primary support during a reset.

5. Key financial metrics at a glance

Dolphin Research view
Shifts in competition remain the core of this year’s investment debate on AppLovin. Essentially, it comes down to changes in AppLovin’s relative ROAS advantage.
(1) On one hand, deeper penetration of e-comm clients adds more bidders, which broadly lifts eCPM. That can pressure conversion for existing gaming clients.
(2) On the other hand, there is new competitive pressure. Sources include Unity, whose Vector is fully rolled out and improving, and Meta, which is returning to iOS app ads via Audience Network (excluding ads on Meta’s own platforms). There is also CloudX, which inserts a ‘pre-bid’ optimization layer between sellers and mediation platforms without fully replacing Max; Dolphin Research views this as largely sentiment-driven in the near term, given it was founded by former co-founder Jim Payne.
Both Unity and Meta showed marginal improvement in Q2 vs. Q1. As a result, at least from a sentiment and expectations standpoint, the Q2 impact on AppLovin would be greater.
While the two peers are unlikely to match AppLovin’s leading ROAS in the near term, advertisers may still test incremental budgets across those channels. Advertisers have long preferred to diversify channels and avoid single-vendor dependence, as long as conversion efficiency holds.
Just as TikTok pressured Meta, Unity and Meta’s renewed focus will inevitably affect AppLovin. Moreover, unlike TikTok back then, Unity and Meta do not carry the same geopolitical overhang.
Thus, when IronSource shut down, most of its share flowed to Unity. Although Unity enjoys an integration advantage, AppLovin still offers higher ROAS, yet it captured little of IronSource’s vacated share.
Beyond the broader ‘AI eating software’ fear, competitive worries have hung over AppLovin this year. Before Jun, with Meta’s iOS return progressing slowly and the full self-serve launch as a catalyst, the stock rallied.
After Jun, e-comm ad demand did not surge with the self-serve rollout (see below: Pixel installs held around 7,000 with no notable uptick). At the same time, some advertisers offered positive feedback on Meta’s marginal improvement, and AppLovin resumed a pullback.

Following nearly a month of correction and some valuation reset, this disappointing print further dents near-term sentiment. After-hours the stock fell 15% to a $119bn market cap, implying 22x 2026 P/E vs. 29x last quarter.
On the results themselves, Dolphin Research sees signs of an emotional overshoot. Sustained confidence repair will require clearer signals, such as progress in e-comm client penetration and ROAS optimization in core gaming.
<End here>
Dolphin Research 'AppLovin' archive
Earnings
Trans dated May 7, 2026.《Applovin (Trans): multiple growth vectors; still many opportunities to invest》
Earnings review dated May 7, 2026.《Applovin: still a sweetheart, but has capital moved on?》
Trans dated Feb 12, 2026.《Applovin (Trans): highly confident vs. Meta》
Earnings review dated Feb 12, 2026.《Applovin: scary narratives overwhelm even strong results?》
Hot takes
Genie take dated Feb 2, 2026.《Gaming stocks bloodbath: did Google snap like Thanos?》
Short-seller note review dated Jan 20, 2026.《Applovin: shorts stir the pot to start the year—how strong is the firepower?》
Short-seller note review dated Mar 30, 2025.《Muddy Waters joins in—Is Applovin really a 'cracked egg'?》
Short-seller note review dated Feb 28, 2025.《A 40% drawdown: does Applovin deserve this?》
Deep dives
Initiation Part 2 dated Jan 10, 2025.《Copy-paste prowess: can Unity clone Applovin’s cash machine?》
Initiation Part 1 dated Jan 3, 2025.《Unpacking the 'feel-good' Applovin: a five-year master plan to win》
Risk disclosure and disclaimer for this piece: Dolphin Research disclaimer and general disclosures