
 I'm LongbridgeAI, I can summarize articles.
Ulta Beauty beat Q2 FY2027 earnings and revenue estimates, raising full-year guidance. However, shares declined due to slowing comparable sales growth (3.8% vs 6.7% prior year) and mixed analyst reactions. While operating income grew over 10%, concerns persist regarding decelerating future growth rates and the expiration of buyback programs, leading to a valuation re-rating despite strong operational results.
This $23 billion cosmetics colossus reported earnings after the market closed on Aug. 27. Healthy results across the board weren't enough to wow the market, and the stock sold off following the release before paring those losses over the next two sessions.
Even analysts are conflicted over the state of the business, so a deeper dive into the numbers is warranted to figure out where ULTA shares are headed next.
Strong Beat and Guidance Raise Not Enough to Boost Shares
Double beats and raises haven't always been enough to reward companies during the most recent quarter. Many top-line figures in the retail sector were juiced by tariff refunds, which are (hopefully!) a one-time boost that won't be recurring in Q3. Ulta largely escaped the tariff net, which means its Q2 fiscal year 2027 (FY2027) results aren't aided by a one-time cash influx. Earnings per share (EPS) totaled $6.55 in the period, ahead of the estimated $6.22. Revenue also beat estimates, growing 8.9% year over year (YOY), and the company raised its fiscal 2027 sales growth outlook to 6.7%-7.2%. Comp sales also grew 3.8% YOY, and operating income grew more than 10% to $379.6 million.
So why the tepid response to a genuinely good quarter? The first factor standing out is gross margin, which dipped from 39.2% to 39.1%. But that largely reflects last year's Space NK acquisition, a U.K. retailer with structurally lower economics. Operating margin actually improved 10 basis points (bps) YOY, so the margin story starts on flimsy ground. The real concern is growth, which the company's own projections show will slow in the coming months.
Acquisitions and New Store Openings Shroud Growth Deceleration
Ulta Beauty MarketRank™ Stock Analysis
- Overall MarketRank™
- 91st Percentile
- Analyst Rating
- Moderate Buy
- Upside/Downside
- 14.8% Upside
- Short Interest Level
- Healthy
- Dividend Strength
- N/A
- News Sentiment
- 1.49
- Insider Trading
- Selling Shares
- Proj. Earnings Growth
- 11.38%
See Full Analysis
Additionally, it's worth reiterating what comp sales strip out: new stores and acquisitions. The gap between net sales outlook and comp sales expectations is supplied by the Space NK acquisition and 31 new store openings, the latter of which laps in the next reporting period. Investors are not buying the 8.9% headline revenue growth figure in the future, nor the 13.3% EPS growth. The 2024 buyback authorization program expires at the end of this year, and any further repurchase agreements will need board approval. Ulta will have bought back $3 billion worth of shares at the culmination of this program, and a lack of future buybacks will likely suppress the 13.3% EPS growth back toward the 10.1% operating income growth figure. If comps and buybacks continue to decline (and the company doesn't make another acquisition), the market could re-rate the stock even lower.
Analysts and the Chart Show Conflicting Momentum Far From Settled
Beauty is in the eye of the beholder, which is why multiple stock analysis firms can view the same report and reach different conclusions. The day after the report, Goldman Sachs and DA Davidson raised their price targets, while Bank of America and Barclays Group lowered theirs. Even experts disagree, and the stock's price action reflects buyers' and sellers' conflicting motivations.
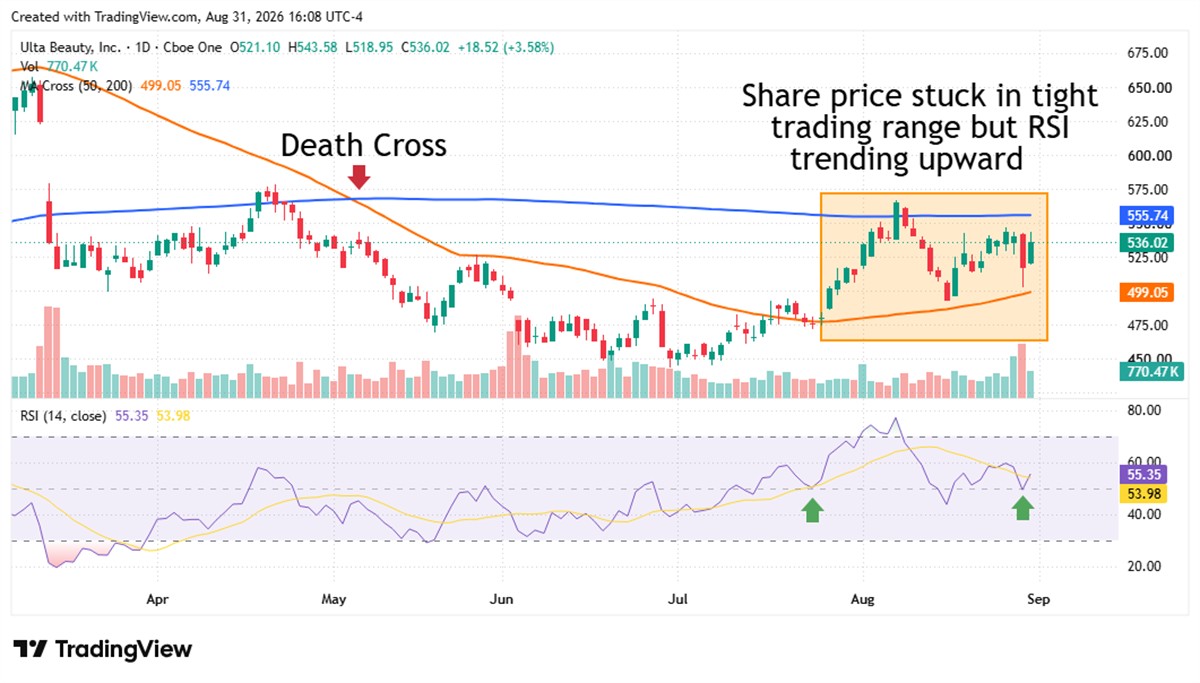
ULTA shares are still down nearly 10% year-to-date (YTD), although the stock has recovered about half of its losses over the last three months. A Death Cross in early May put bulls on the defensive, but the Relative Strength Index (RSI) began trending up from Oversold levels shortly thereafter. The RSI re-entered bullish territory as the share price overtook the 50-day moving average, a resistance level not surpassed since early March.
But now comes the tough part. The next earnings catalyst is still three months away, and the stock is now stuck between resistance at the 200-day moving average and support at the 50-day moving average. A break above the 200-day would be a strong signal that the uptrend is resuming, but if the RSI dips back under 50, it could mean another long period of range-bound trading ahead of fiscal Q3 results.
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
Add As Preferred Source
Should You Invest $1,000 in Ulta Beauty Right Now?
Before you consider Ulta Beauty, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and Ulta Beauty wasn't on the list.
While Ulta Beauty currently has a Moderate Buy rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here