
 I'm LongbridgeAI, I can summarize articles.
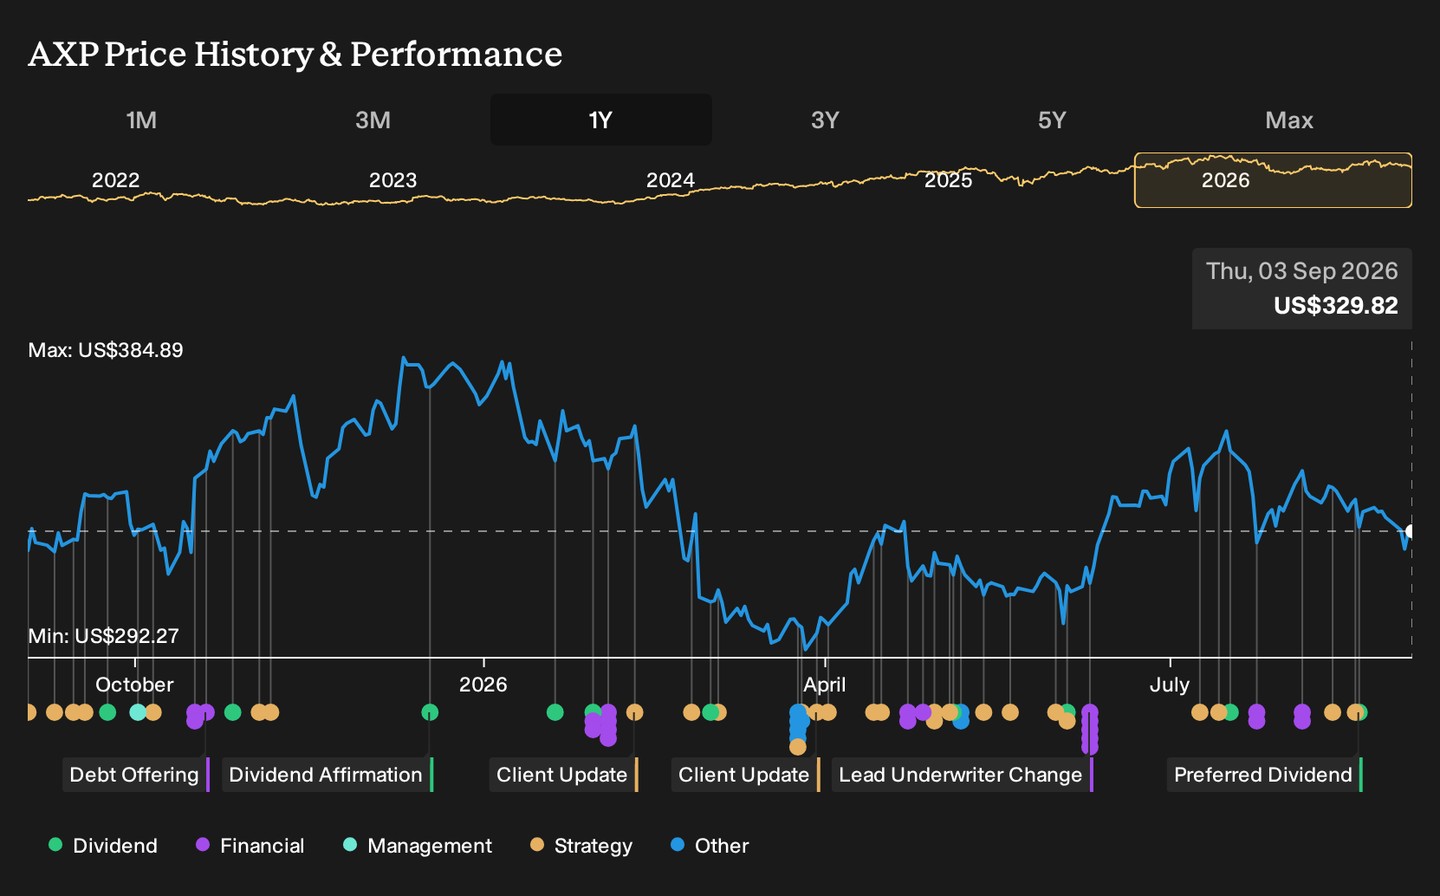
American Express reported Q2 revenue that missed analyst expectations, contrasting with stronger results from peers like Visa and Mastercard. This performance highlights specific execution risks regarding premium card spending and competitive pressure from digital wallets. Despite the miss, AXP maintained full-year guidance of 9-10% revenue growth and EPS of $17.30-$17.90. The article analyzes whether this reflects a temporary dip or persistent shift, noting fair value estimates suggest potential upside despite rising rewards pressure.
- In the past quarter, American Express reported Q2 revenues that fell short of analyst expectations, even as several major card-issuing peers delivered stronger results.
- This contrast with companies such as Bread Financial, Visa, Mastercard, and Synchrony Financial highlights how investor attention has sharpened around American Express’s company-specific performance rather than sector-wide trends.
- We’ll now examine how American Express’s softer-than-expected Q2 revenue shapes the existing investment narrative built around premium fees and affluent spending.
AI is about to change healthcare. These 37 stocks are working on everything from early diagnostics to drug discovery. The best part - they are all under $10b in market cap - there's still time to get in early.
American Express Investment Narrative Recap
To own American Express, you need to believe its premium, fee-focused model and affluent customer base can support earnings growth even when quarterly results are uneven. The softer Q2 revenue and stock pullback sharpen attention on execution in premium cards and spending trends, but they do not materially alter the near term catalyst of product refreshes and younger customer growth. The biggest risk remains rising competitive and rewards pressure that could compress margins if revenue disappoints again.
Against this backdrop, the recent Q2 2026 earnings release, which confirmed full year revenue growth guidance of about 9 to 10 percent and EPS of US$17.30 to US$17.90, is especially relevant. It anchors the current premium valuation and capital return program, including sizeable buybacks, while investors reassess whether the latest revenue miss reflects a temporary bump or a more persistent shift in spending and fee income momentum.
Yet beneath the appeal of premium fees and affluent spend, investors should also be aware of the growing threat from alternative payment platforms and how quickly that risk could...
Read the full narrative on American Express (it's free!)
American Express' narrative projects $95.1 billion revenue and $14.8 billion earnings by 2029. This requires 11.4% yearly revenue growth and an earnings increase of about $3.7 billion from $11.1 billion.
Uncover how American Express' forecasts yield a $374.94 fair value, a 14% upside to its current price.
Exploring Other Perspectives
Some of the most optimistic analysts were assuming revenues could reach about US$98.7 billion by 2029, yet Q2’s revenue miss and rising pressure from digital wallets show how differently you and others might view American Express’s future path.
Explore 7 other fair value estimates on American Express - why the stock might be worth 5% less than the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your American Express research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- Our free American Express research report provides a comprehensive fundamental analysis summarized in a single visual - the Snowflake - making it easy to evaluate American Express' overall financial health at a glance.
Interested In Other Possibilities?
Don't miss your shot at the next 10-bagger. Our latest stock picks just dropped:
- Capitalize on the AI infrastructure supercycle with our selection of the 55 best 'picks and shovels' of the AI gold rush converting record-breaking demand into massive cash flow.
- The latest GPUs need a type of rare earth metal called Neodymium and there are only 30 companies in the world exploring or producing it. Find the list for free.
- We've uncovered the 11 dividend fortresses yielding 5%+ that don't just survive market storms, but thrive in them.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
New: Manage All Your Stock Portfolios in One Place
We've created the ultimate portfolio companion for stock investors, and it's free.
• Connect an unlimited number of Portfolios and see your total in one currency
• Be alerted to new Warning Signs or Risks via email or mobile
• Track the Fair Value of your stocks
Try a Demo Portfolio for Free