
 I'm LongbridgeAI, I can summarize articles.
Qualcomm (QCOM) stock rose 3.23% on Sep 11, driven by a strategic AI collaboration with Amazon Web Services and broad chip price hikes. Analysts upgraded sentiment as the company pivots to enterprise infrastructure. However, risks include potential equity dilution from Amazon warrants, accelerating revenue loss from Apple's in-house modem shift, manufacturing pricing disputes with Samsung, and delayed AI data center revenue until 2027.
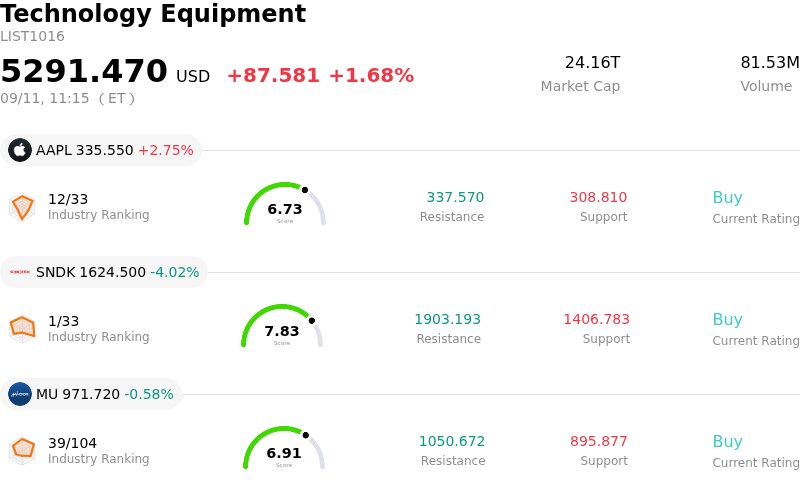
Qualcomm Inc (QCOM) moved up by 3.23%. The Technology Equipment sector is up by 1.68%. The company outperformed the industry. Top 3 stocks by turnover in the sector: Apple Inc (AAPL) up 2.75%; SanDisk Corporation (SNDK) down 4.02%; Micron Technology Inc (MU) down 0.67%.
What is driving Qualcomm Inc (QCOM)’s stock price up today?
Qualcomm experienced notable intraday volatility and finished higher as bullish momentum surrounding its long-term artificial intelligence strategy continued to rebuild. The primary catalyst driving market sentiment is the landmark multi-generational collaboration announced with Amazon Web Services. Under this agreement, Qualcomm will co-develop customized silicon for AI inference data centers alongside advanced optical connectivity solutions. The deal, which includes warrants allowing Amazon to acquire equity tied to substantial potential commercial hardware purchases over the coming decade, provides tangible validation that Qualcomm can successfully scale its footprint in enterprise infrastructure beyond its core mobile chip business.
Adding to the positive market momentum, Qualcomm recently implemented broad double-digit price increases across its chip portfolio to counteract rising component and memory costs globally. This move underscores the company's strong pricing power and helps protect profit margins as it rolls out next-generation platforms, including the Snapdragon X2 Elite for AI-capable personal computers. Investors are viewing these pricing adjustments and new product rollouts as key enablers for accelerating non-handset revenue, helping the semiconductor designer pivot toward high-margin growth vectors in cloud computing and edge devices.
Analyst actions further fortified investor sentiment during the trading session, highlighted by a research upgrade from Piper Sandler. Wall Street brokerages are increasingly recognizing the structural growth narrative as Qualcomm diversifies away from pure smartphone market exposure. While risks related to mobile market maturity and internal customer modem transitions persist, the growing enterprise commitment to Qualcomm's custom silicon and optical networking technologies has led institutional investors to re-evaluate the stock's long-term valuation trajectory amidst ongoing sector rebalancing.
Technical Analysis of Qualcomm Inc (QCOM)
Technically, Qualcomm Inc (QCOM) shows a MACD (12,26,9) value of 4.844, indicating a buy signal. The RSI at 67.804 suggests neutral condition and the Williams %R at 9.167 suggests overbought condition. Please monitor closely.
Media Coverage of Qualcomm Inc (QCOM)
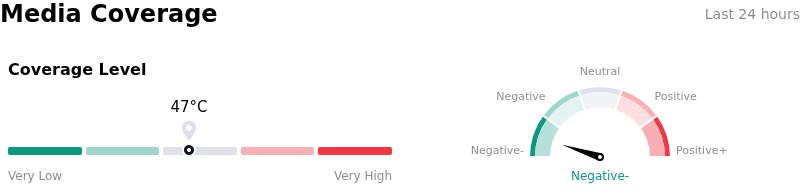
In terms of media coverage, Qualcomm Inc (QCOM) shows a coverage score of 47, indicating a moderate level of media attention. The overall market sentiment index is currently in extremely bearish zone.
Fundamental Analysis of Qualcomm Inc (QCOM)
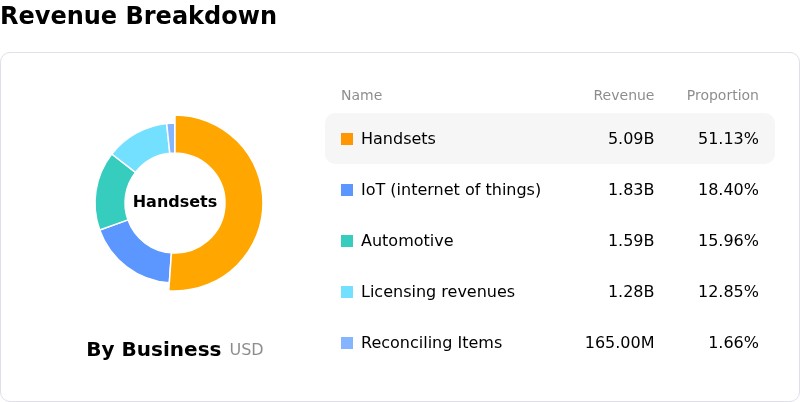
Qualcomm Inc (QCOM) is in the Technology Equipment industry. Its latest annual revenue is $44.28B, ranking 6 in the industry. The net profit is $5.54B, ranking 9 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Hold, with an average price target of $194.40, a high of $400.00, and a low of $100.00.
More details about Qualcomm Inc (QCOM)
Company Specific Risks:
- Potential Share Dilution from Amazon Warrant Grant: Recent SEC Form 8-K filings reveal that Qualcomm granted Amazon warrants to purchase up to 25 million shares of common stock at $161.26 per share, introducing a potential 2.34% equity dilution that triggered profit-taking and fueled intraday volatility following initial hype around their server chip partnership.
- Accelerating Apple Revenue Loss and Handset Weakness: Management projections and analyst reports highlight that revenue loss from Apple is set to accelerate starting in Q4 FY2026 as Apple shifts toward in-house modem solutions, compounding ongoing revenue softness in the core CDMA Technologies smartphone segment.
- Manufacturing Bottlenecks and Pricing Friction with Samsung: Contract negotiations between Qualcomm and Samsung over 2nm chip manufacturing have hit an impasse over pricing, risking production delays for upcoming application processors that could jeopardize key 2026 smartphone launch schedules.
- Lagging AI Data Center Revenue vs. Immediate Upfront Costs: Institutional commentary notes that despite recent announcements of AI server processors and data center partnerships, material revenue contribution from AI silicon is not expected until 2027, leaving the company exposed to elevated development costs without near-term offsetting cash flow.
Find out more