
300941
14.620.61%
B
Oct 16, 2025 at 11:28 AM
Summary of Q3 2025 financial reports of the four major US banks and verification of post conclusions
 I'm LongbridgeAI, I can summarize articles.
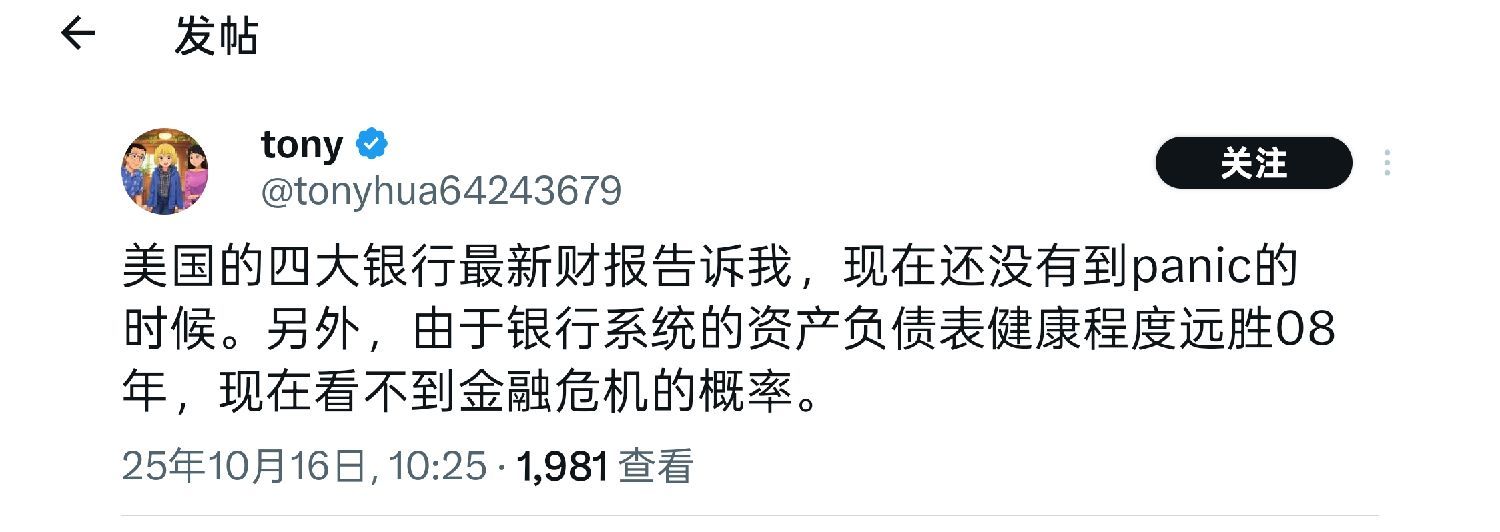
X post (from @tonyhua64243679) discussed the latest earnings reports of the four major U.S. banks (JPMorgan Chase, Bank of America, Citigroup, Wells Fargo), concluding that there is no need to panic as the banking system's balance sheets are far healthier than in 2008, making a financial crisis unlikely at present. Below is a summary and verification based on the earnings data:
Earnings Overview
These banks reported their Q3 results around October 14-15, 2025, showing strong overall performance driven by U.S. economic resilience, investment banking, and trading activities, with both profits and revenue growing and exceeding analyst expectations. Details are as follows:
JPMorgan Chase: Net profit of $14.39 billion, up 12% YoY; EPS of $5.07 (beating expectations of $4.85); revenue rose 9% to $47.12 billion. Trading and market revenue grew 25%, while investment banking fees increased 16%. Consumer spending and corporate transactions were strong, though credit losses rose slightly.
Bank of America: Net profit of $8.5 billion, up 23% YoY; EPS of $1.06 (beating expectations of $0.95); revenue rose 11% to $28.09 billion. Investment banking revenue surged 43% to $2.05 billion. Wealth management and trading fees improved, with optimism about economic growth despite deposit cost pressures.
Citigroup: Net profit of $3.8 billion; revenue grew 9% YoY (~$21-22 billion). All major divisions set quarterly records, including services, markets, and wealth management. Global operations were strong, while restructuring efforts to improve efficiency continued.
Wells Fargo: EPS of $1.66 (beating expectations); revenue of $21.43 billion (beating expectations of $21.14 billion). Housing loans and commercial banking performed well, with shares rising 7-9%, reflecting investor confidence in cost control and asset quality.
Overall, banks showed no major issues, such as large-scale loan defaults or liquidity crises. Although credit loss provisions increased slightly (due to rising delinquency rates in credit cards and commercial real estate), they remained manageable.
Post Conclusion Verification
The post's argument holds: Based on standard metrics and official reports, bank balance sheets are far superior to those during the 2008 financial crisis. The crisis then stemmed from subprime mortgage collapses, insufficient capital buffers, and high leverage, whereas today, the Dodd-Frank Act and Basel III reforms demand higher capital quality and stress tests, leading to:
High Capital Ratios: Common Equity Tier 1 (CET1) ratios far exceed regulatory minimums (4.5% plus buffers). For example, JPMorgan ~14.8-14.9%, Bank of America 11.6%, Citigroup 13.2%, Wells Fargo targeting 10-10.5% (actual higher). Pre-2008 equivalent ratios were only 8-10% and of lower quality; current ratios are near historical highs, providing strong buffers.
Asset Quality & Liquidity: Delinquency rates are higher in some areas but below 2008 peaks, with adequate loan loss provisions. Liquidity ratios are above pre-pandemic levels, and uninsured deposit reliance has normalized to pre-2022 levels. The Fed's April 2025 Financial Stability Report called the system "robust and resilient," with vulnerabilities "moderate."
However, a September 2025 New York Fed study using the "Economic Value Systemic Risk" (EVSR) metric suggested systemic risk may exceed 2008 levels, citing declining economic capital, fragile deposit bases (more uninsured deposits), commercial real estate refinancing, and shadow bank exposures. This view, based on forward-looking models, may overstate risks in a mild economic environment and represents a researcher's perspective, not Fed consensus.
Overall, strong Q3 results and reinforced capital support the post's "no need to panic" stance. There are no crisis signs currently, but economic changes (e.g., interest rates or recession) must be monitored.
Personal view: The rate-cut cycle is about to begin in full, the financial sector is broadly stable, and it's time to actively invest in mainstream core assets.
$Tesla(TSLA.US) $Coinbase(COIN.US) $Taiwan Semiconductor(TSM.US) $Robinhood(HOOD.US)

Citigroup
USC

Bank of America
USBAC

JPMorgan Chase
USJPM

Chase
SZ300941

Robinhood
USHOOD

Wells Fargo
USWFC

Coinbase
USCOIN

Tesla
USTSLA

Taiwan Semiconductor
USTSM

COIN 2X Long ETF
USCONL

07311
HK07311

TSDD
USTSDD

TSLL
USTSLL

TSLQ
USTSLQ

09366
HK09366

07766
HK07766

07366
HK07366

TSLR
USTSLR

III
USIII

XLF
USXLF

BAC-B
USBAC-B

BAC-E
USBAC-E

BAC-K
USBAC-K

BAC-L
USBAC-L

BAC-M
USBAC-M

BAC-N
USBAC-N

BAC-O
USBAC-O

BAC-P
USBAC-P

BAC-Q
USBAC-Q

BAC-S
USBAC-S

BML-G
USBML-G

BML-H
USBML-H

BML-J
USBML-J

BML-L
USBML-L

MER-K
USMER-K

JPM-C
USJPM-C

JPM-D
USJPM-D

JPM-J
USJPM-J

JPM-K
USJPM-K

JPM-L
USJPM-L

JPM-M
USJPM-M

WFC-A
USWFC-A

WFC-C
USWFC-C

WFC-D
USWFC-D

WFC-L
USWFC-L

WFC-Y
USWFC-Y

WFC-Z
USWFC-Z
The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.