

Mitsui Fudosan Accommodations Fund (TSE:3226) Heads Into Earnings With 7.4% TTM EPS Growth Narratives
 I'm LongbridgeAI, I can summarize articles.
Mitsui Fudosan Accommodations Fund (TSE:3226) reported FY 2026 results with total revenue of ¥13.7b in 2H and basic EPS of ¥2,523.68, leading to a trailing twelve month EPS of ¥4,847.54 and a net profit margin of 45.3%. Despite a 7.4% earnings growth, concerns arise over debt coverage and dividend sustainability, as the fund trades at a premium P/E of 27.6x. Investors are advised to consider long-term trends and balance sheet risks alongside the fund's consistent earnings growth.
Mitsui Fudosan Accommodations Fund (TSE:3226) has wrapped up FY 2026 with total revenue of ¥13.7b in the second half and basic EPS of ¥2,523.68, while trailing twelve month revenue sits at ¥26.9b and EPS at ¥4,847.54, supported by net income of ¥12.2b. Over the past reported halves, revenue has moved from ¥12.8b in 2H FY 2025 to ¥13.2b in 1H FY 2026 and then ¥13.7b in 2H FY 2026. Basic EPS has stepped from ¥2,301.22 to ¥2,323.86 to ¥2,523.68 as net profit margins held in the mid 40% range. This sets up a results season where investors will be focused on how sustainable those margins look against the latest numbers.
See our full analysis for Mitsui Fudosan Accommodations Fund.
With the headline figures on the table, the next step is to see how this earnings print lines up with the widely held narratives about the fund, and where the numbers start to push back against those stories.
Curious how numbers become stories that shape markets? Explore Community Narratives
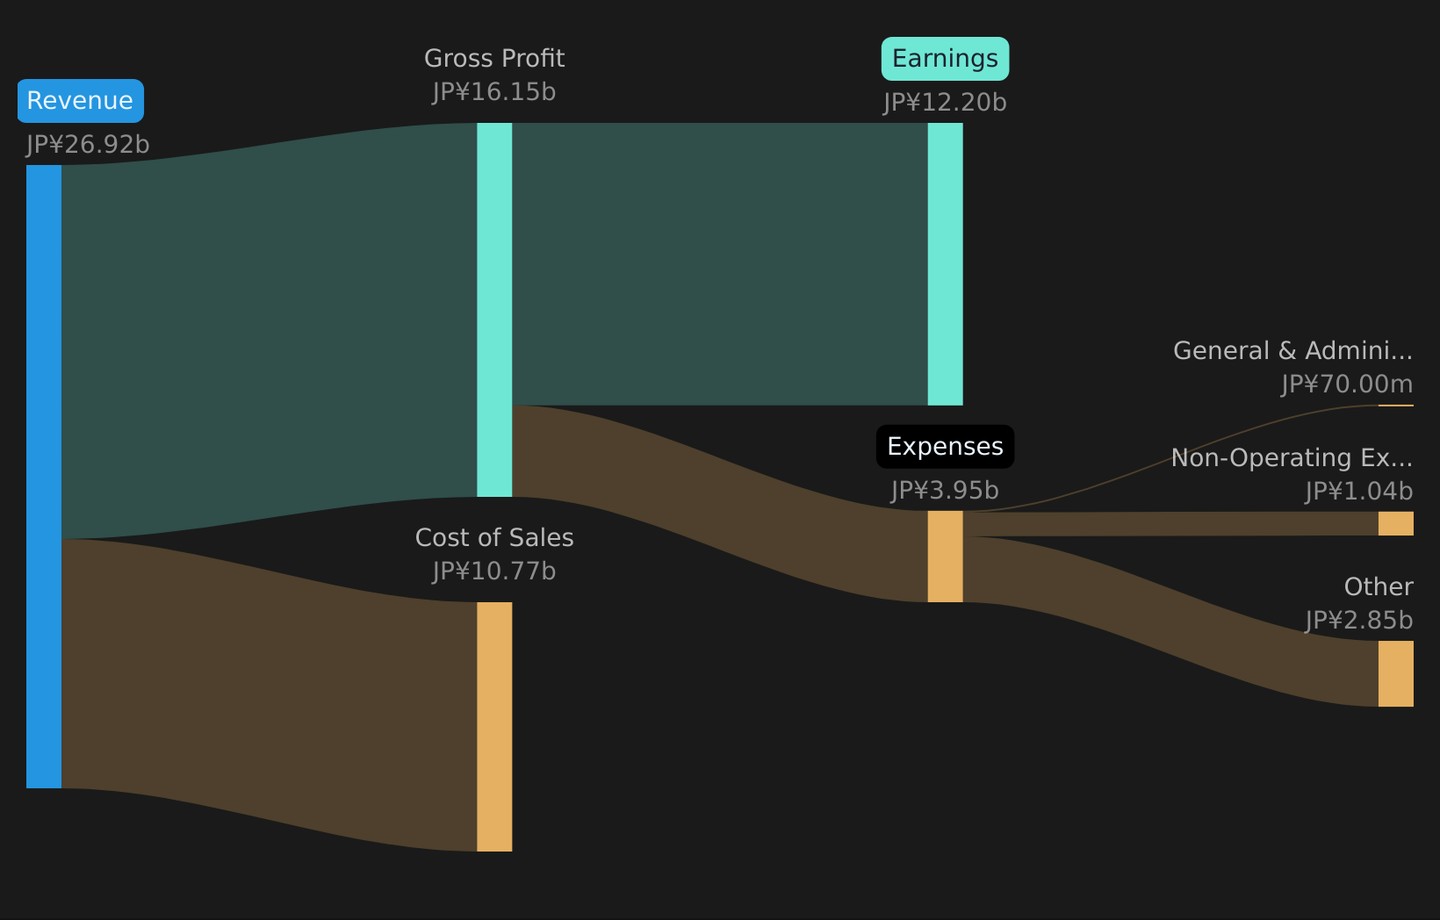
TTM earnings grow 7.4% on 45.3% margins
- Trailing twelve month basic EPS sits at ¥4,847.54 with net profit margin at 45.3% versus 44.5% a year earlier, and earnings growth over the last year at 7.4% compared with a 4.1% average over five years.
- What stands out for the generally optimistic view is how steady profitability looks, with:
- Revenue over the last twelve months at ¥26.9b and net income at ¥12.2b, which keeps margins in the mid 40% range even as revenue growth was forecast around 1.5% per year against a 5.8% JP market benchmark.
- Basic EPS across the last three reported halves moving from ¥2,301.22 to ¥2,323.86 to ¥2,523.68, which supports the idea of consistent earnings power while still leaving questions about how much of that can continue if revenue grows more slowly than the broader market.
Curious how this earnings momentum shapes the bigger story around Mitsui Fudosan Accommodations Fund, and where other investors think it could go from here? 📊 Read the what the Community is saying about Mitsui Fudosan Accommodations Fund.
Premium 27.6x P/E with modest DCF gap
- The fund trades on a trailing P/E of 27.6x, above the Global Residential REITs average of 24.3x and peer average of 21.8x, while the DCF fair value of ¥139,047.56 sits about 3.9% above the current share price of ¥133,600.
- What is interesting for a more optimistic angle is how the valuation and cash flow picture line up, with:
- The current price sitting slightly below the DCF fair value estimate, which tempers concerns that the higher than peer P/E automatically means a stretched valuation.
- Five year earnings growth averaging 4.1% a year and trailing revenue of ¥26.9b, which helps explain why some investors might accept premium multiples while still having to weigh that against slower forecast revenue growth versus the JP market.
Cash flow and dividend coverage under pressure
- Debt is flagged as not well covered by operating cash flow and the 3.38% dividend is described as not well covered by earnings, which sits alongside trailing FFO of ¥7,781m and FFO per share of ¥6,181.87 over the last twelve months.
- Critics focusing on the more cautious view point to these coverage metrics as key watchpoints, with:
- The combination of weaker debt coverage by operating cash flow and a dividend that is not well covered by earnings standing in contrast to the otherwise strong 45.3% net margin and ¥12.2b of net income over the same period.
- The reliance on accommodation assets and income distribution alongside a premium 27.6x P/E, which means balance sheet and payout coverage risks sit alongside the fund’s consistent earnings growth record when investors think about downside protection.
Next Steps
Don't just look at this quarter; the real story is in the long-term trend. We've done an in-depth analysis on Mitsui Fudosan Accommodations Fund's growth and its valuation to see if today's price is a bargain. Add the company to your watchlist or portfolio now so you don't miss the next big move.
Seen enough to sense both the upside and the pressure points? Take a moment to look through the numbers yourself and decide how comfortable you are with the balance of income, valuation and balance sheet support, then round out your view by checking 2 key rewards and 2 important warning signs
See What Else Is Out There
Despite strong margins and earnings, the fund pairs a premium 27.6x P/E with weaker debt and dividend coverage, which raises questions about downside protection.
If you are uneasy about that balance sheet strain and payout pressure, it is worth quickly comparing this fund with companies in the solid balance sheet and fundamentals stocks screener (34 results) to see options with stronger financial backing.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
New: Manage All Your Stock Portfolios in One Place
We've created the ultimate portfolio companion for stock investors, and it's free.
• Connect an unlimited number of Portfolios and see your total in one currency
• Be alerted to new Warning Signs or Risks via email or mobile
• Track the Fair Value of your stocks
Try a Demo Portfolio for Free