

Jensen Huang Just Delivered Incredible News for Nvidia Stock Investors
 I'm LongbridgeAI, I can summarize articles.
Nvidia CEO Jensen Huang indicated that chip sales could double next year, driven by the new Vera Rubin architecture which significantly reduces AI inference costs. With a market cap of $5.4 trillion and expected revenue growth of 70% in fiscal 2028, Nvidia appears undervalued at a P/E ratio of 28.1. However, risks include potential infrastructure spending slowdowns due to interest rates, regulatory concerns over AI development pace, and increased financing of sales to startups.
Nvidia (NVDA +1.34%) supplies the world's best graphics processing units (GPUs) for data centers, which are the primary chips used in artificial intelligence (AI) training and inference workloads. Demand for this hardware is outstripping supply as technology giants spend record amounts of money to build infrastructure in the race for AI supremacy.
Nvidia was a $360 billion company when the AI boom started gathering momentum in early 2023, but it's now worth almost 15 times more, with a market capitalization of $5.3 trillion at the close of trading last Friday. According to a series of comments by CEO Jensen Huang last week, there might be plenty of growth left in the tank. Read on.
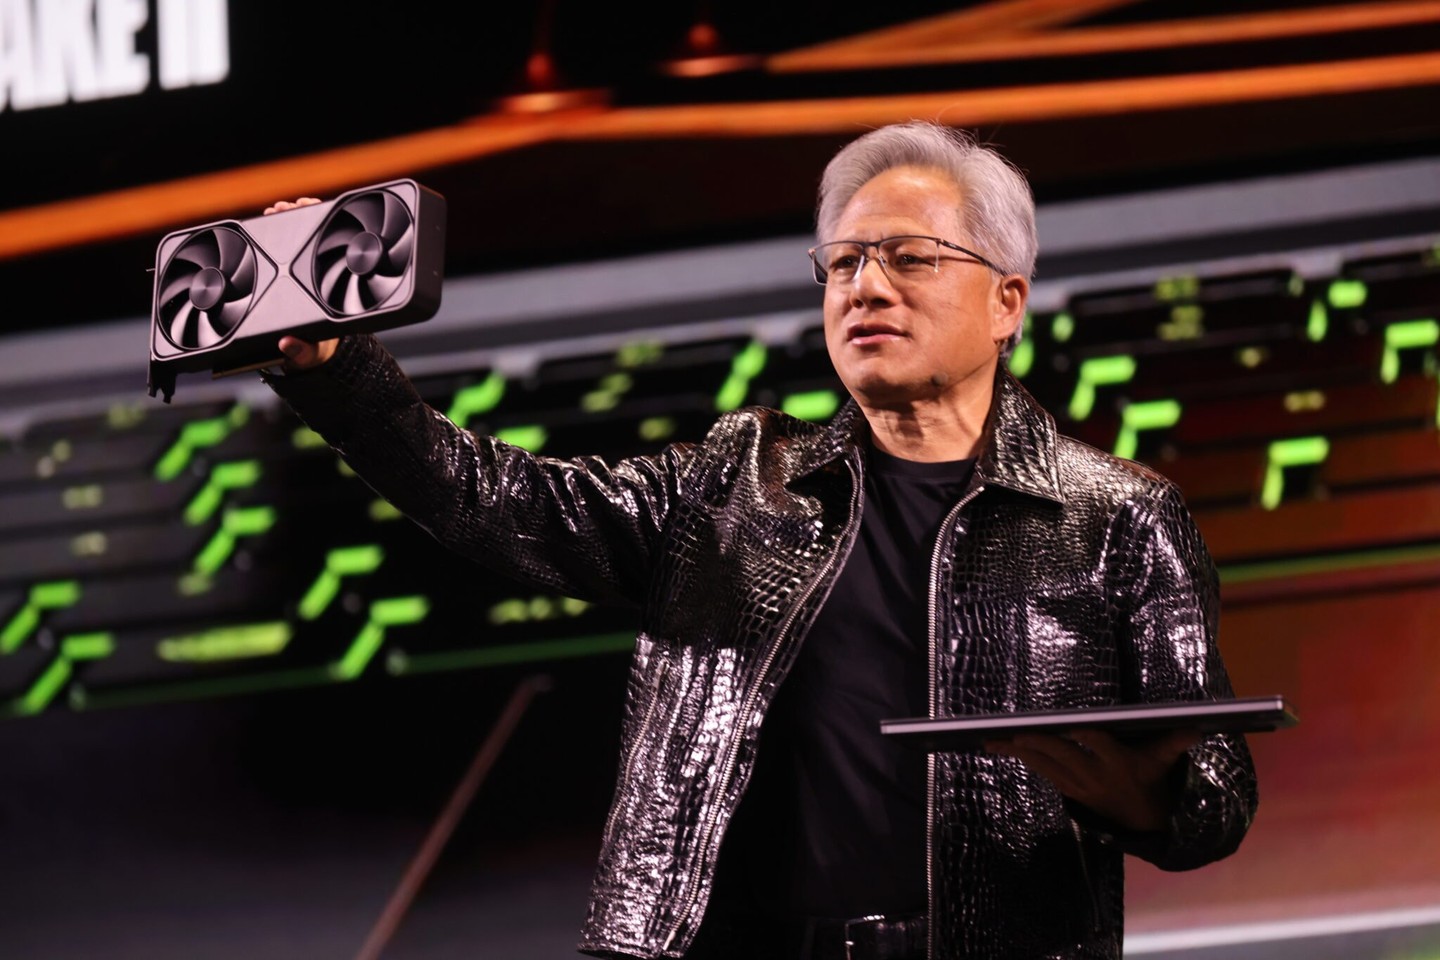
Nvidia CEO Jensen Huang. Image source: Nvidia.
Nvidia's chip sales could double next year
Nvidia's Blackwell Ultra architecture is at the foundation of its flagship GB300 GPU, which is currently the most popular data center chip in the AI industry. It offers up to 50 times more performance in certain configurations compared to the company's original Hopper-based H100 GPU from 2022, highlighting the sheer pace of innovation.
But Nvidia just started shipping its next-generation data center system called Vera Rubin. It includes the Rubin GPU, the Vera central processing unit (CPU), and a series of upgraded networking components, and it can provide up to 30 times more performance than the equivalent Blackwell Ultra system. Moreover, it can reduce inference token costs by a staggering 97%.
Inference tokens are the text, images, and computer code an AI model generates in response to a prompt, so Vera Rubin will significantly reduce the cost of deploying AI software. This will likely encourage more AI adoption while also making data center operators more profitable, which will spur further demand for Nvidia's chips.

NASDAQ: NVDA
Key Data Points
A few months ago, Jensen Huang said every frontier AI company planned to adopt Vera Rubin at launch, which wasn't the case for Blackwell Ultra, so this new architecture was already expected to be a bigger commercial success than its predecessor. But Huang offered even more color during a speech in Scotland last Thursday, saying Nvidia could sell twice as many chips next year compared to this year.
Nvidia doesn't disclose how many chips it sells annually. However, it's on track to deliver around $411 billion in total revenue during its current 2027 fiscal year (which ends on Jan. 31, 2027), based on Wall Street's average estimate. Moreover, management recently told shareholders to expect 70% revenue growth in fiscal 2028, implying the company could bring in almost $700 billion next year.
If recent quarters are anything to go by, over 90% of that revenue will come from the data center business alone.
Nvidia stock looks like a bargain heading into next year
Nvidia stock is trading at a price-to-earnings (P/E) ratio of 28.1, less than half its 10-year average of 61.4. It's also trading at just 14 times Wall Street's average fiscal 2028 earnings estimate, which suggests the stock would have to double over the next 18 months or so just to maintain its current P/E.
NVDA PE Ratio data by YCharts
From that perspective, Nvidia looks like an absolute bargain right now -- but there are a few risks to consider. First of all, the top five hyperscalers (like Amazon and Microsoft) are on track to spend a combined $800 billion on infrastructure this year, which Nvidia believes will grow to $1.3 trillion next year. Those are enormous numbers, and since some of those companies are using debt financing, the recent rise in interest rates could disrupt their plans.
Second, leading AI labs Anthropic, OpenAI, and xAI recently agreed that slowing down the pace of development might be necessary to minimize the potential risks to humanity. Anthropic founder Dario Amodei is worried developers could soon lose control of their most powerful models, citing a spate of recent cybersecurity incidents. Any slowdown in development will almost certainly reduce demand for chips.
Third, Nvidia is actually financing a growing portion of its sales to AI start-ups. CFO Colette Kress recently told investors that around 25% of the company's fiscal 2028 sales will come from customers it has financed in some way. As I highlighted earlier, Nvidia could bring in almost $700 billion in sales next year, meaning roughly $175 billion might be funded by its own balance sheet.
In other words, a massive chunk of Nvidia's fiscal 2028 sales could come from customers that don't have the money to pay for its chips upfront, which is a risky proposition.
Some of the above issues are already baked into Nvidia stock, hence its low valuation, so I still think it's a buy. Future returns might be determined by how those risks develop; if they subside, for example, investors could do very well from here.