

JPMorgan Q3 Earnings Preview: Revenue Expected to Rise 10%, Highest Wall Street Target at $420
 I'm LongbridgeAI, I can summarize articles.
JPMorgan is set to report Q3 2026 earnings on October 13, with analysts projecting a 10.4% revenue increase to $51.23 billion and EPS of $5.93. Wall Street sentiment remains optimistic, driven by strong capital markets and net interest income, though some targets suggest potential sequential slowdowns in trading. Barclays and BofA have set high price targets of $420, while the average target stands at $372. Investors will monitor whether results exceed expectations or if rising expenses and credit costs impact profitability.
TradingKey - JPMorgan (JPM) will report its third-quarter fiscal 2026 financial results before the market open on October 13, Eastern Time, and host an earnings call at 8:30 a.m. the same day.
As of the close on October 12, JPMorgan's stock price stood at $334.30, up 0.39% for the day.
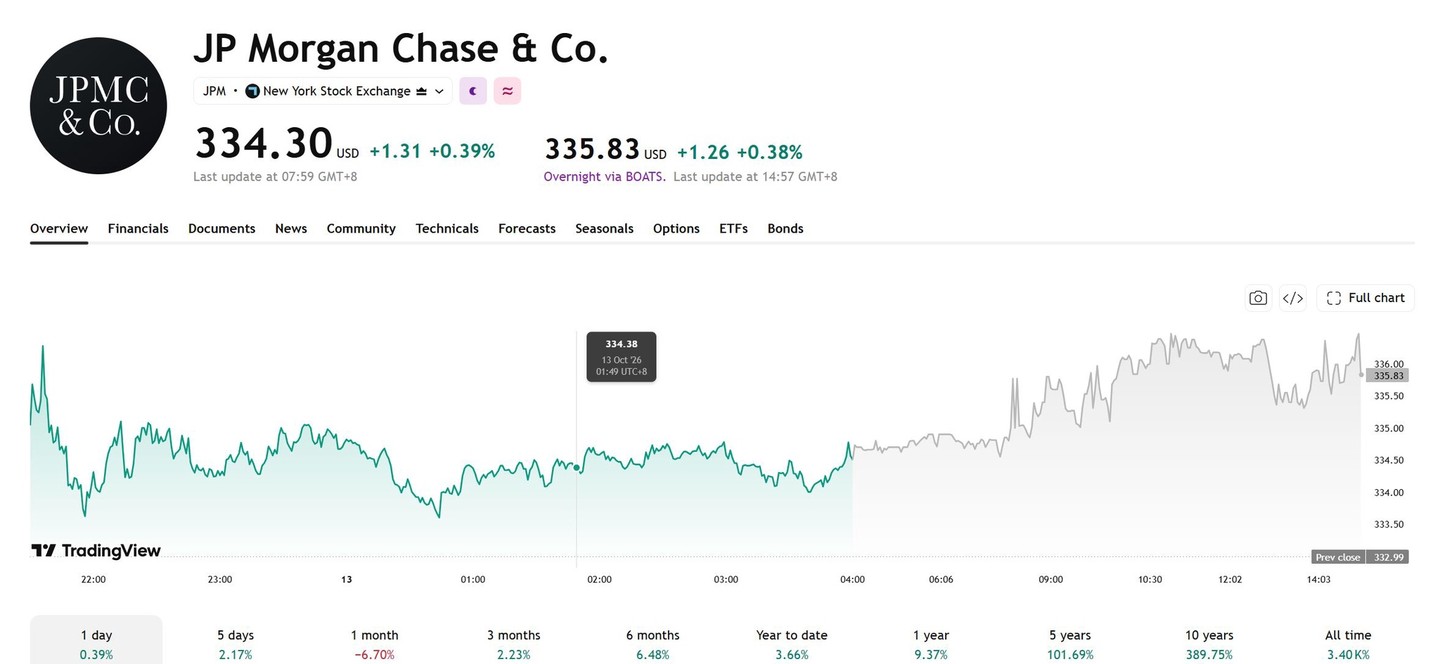
[Source: TradingView]
Wall Street Expects Revenue Growth of 10.4%
According to FactSet data, analysts expect JPMorgan Chase's third-quarter revenue to reach $51.23 billion, up 10.4% year-over-year; earnings per share are projected at $5.93, up about 11% year-over-year.
Market expectations have been revised upward significantly compared with late June, when analysts projected revenue of $48.92 billion and earnings per share of $5.49. The rising expectations indicate that the market is more optimistic about JPMorgan Chase's capital markets business and net interest income performance, though some of the positive factors may already be reflected in the stock price and valuation.
JPMorgan Q2 Results Hit Record High: Can Trading Revenue Continue?
In the second quarter, JPMorgan Chase reported revenue of $57.35 billion, net income of $21.16 billion, and earnings per share of $7.70. Corporate & Investment Bank revenue reached $24.85 billion, up 27% year-over-year; investment banking revenue was $3.9 billion, up 45% year-over-year; and Markets & Securities Services revenue was $13.69 billion, up about 33% year-over-year.
Among this, equity markets revenue surged 86% year-over-year, becoming the primary growth driver for the capital markets division. The strong second-quarter growth raised the comparison base for the third quarter, meaning that even if double-digit growth is maintained this quarter, sequential performance may still slow.
Investment Banking, Trading and Net Interest Income Are Key Metrics
JPMorgan Chase Co-President Doug Petno stated that third-quarter investment banking fee revenue and markets revenue are expected to grow in the mid-to-high double digits year-over-year. M&A activity, equity issuance, and trading demand will impact capital markets revenue this quarter.
However, as revenue from certain trading and investment banking operations reached elevated levels in the second quarter, third-quarter performance may pull back sequentially. Investors need to monitor whether actual growth reaches the upper end of the company's expectations, and whether both equity and fixed-income trading can sustain growth simultaneously.
Net interest income is also a key driver of earnings. JPMorgan's second-quarter net interest income rose 9.9% year-over-year to $25.51 billion, and the bank raised its 2026 net interest income forecast from $103 billion to $105.5 billion. However, the company also raised its full-year adjusted expense guidance from $105 billion to $107.5 billion, and rising expenses could weaken the contribution of revenue growth to profits.
Credit costs also warrant attention. In the second quarter, the provision for credit losses was $2.5 billion, and net charge-offs were $2.4 billion. If delinquency rates for credit cards and consumer loans rise, increased provisions could offset part of the net interest income growth.
Wall Street's Highest Price Target Sees $420
According to data from StockAnalysis, as of pre-market on October 13, the average price target from 25 analysts for JPMorgan is $372.14, implying an 11.32% upside from its latest closing price of $334.30.
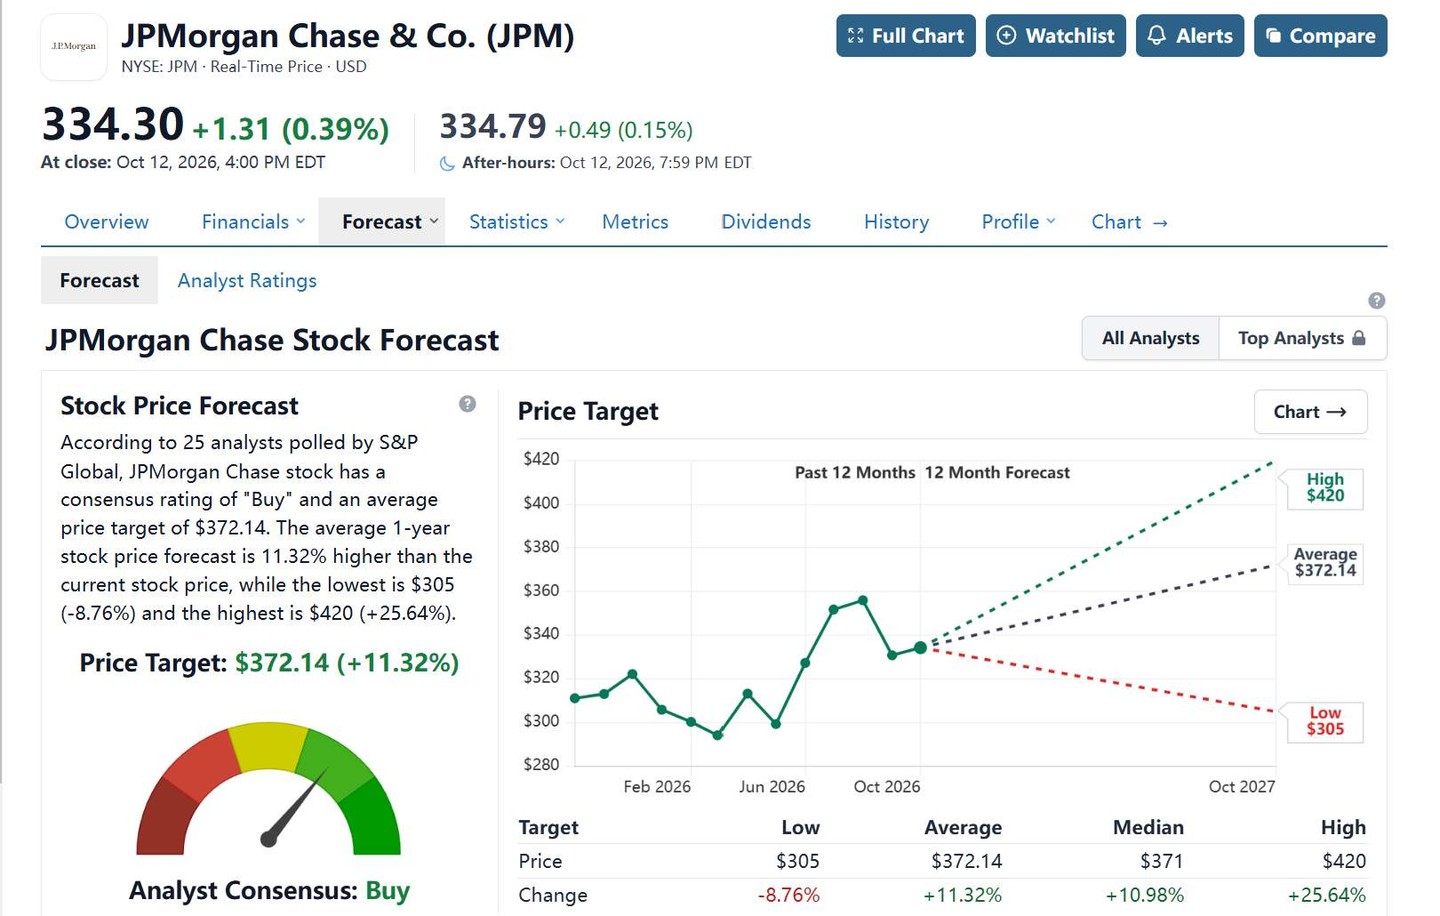
[Source: StockAnalysis]
According to public data, both Barclays and BofA Securities have previously set target prices of $420. Barclays is optimistic about mid-to-high double-digit growth in its third-quarter trading and investment banking revenue, believing that net interest margin expansion and balance sheet growth will drive net interest income higher and support a strong return on tangible common equity. Meanwhile, BofA Securities is mainly bullish on JPMorgan's sustained earnings growth and solid operational performance.
Visible Alpha expects JPMorgan's third-quarter net interest income growth outlook to be relatively strong among major banks, with net interest margins likely to improve. The market is generally optimistic about its capital markets business, though trading revenue may pull back from its second-quarter high.
If third-quarter investment banking and trading revenues continue to post double-digit growth, net interest income rises, and provisions for credit losses and expenses come in lower than expected, JPM's stock price is expected to continue gaining strength.
If results merely meet market expectations, or if management raises guidance on expenses and credit losses, the stock price may experience a pullback. The market's current focus has shifted from whether JPMorgan can maintain earnings growth to whether it can continue to beat market expectations.