
O

Aug 23 at 02:01 PM
Alibaba's FY27Q1: The Price of Growth Is Now Visible on the Income Statement
 I'm LongbridgeAI, I can summarize articles.
Every headline number checks out — and the erosion is coming from the core business, not one-off noise.
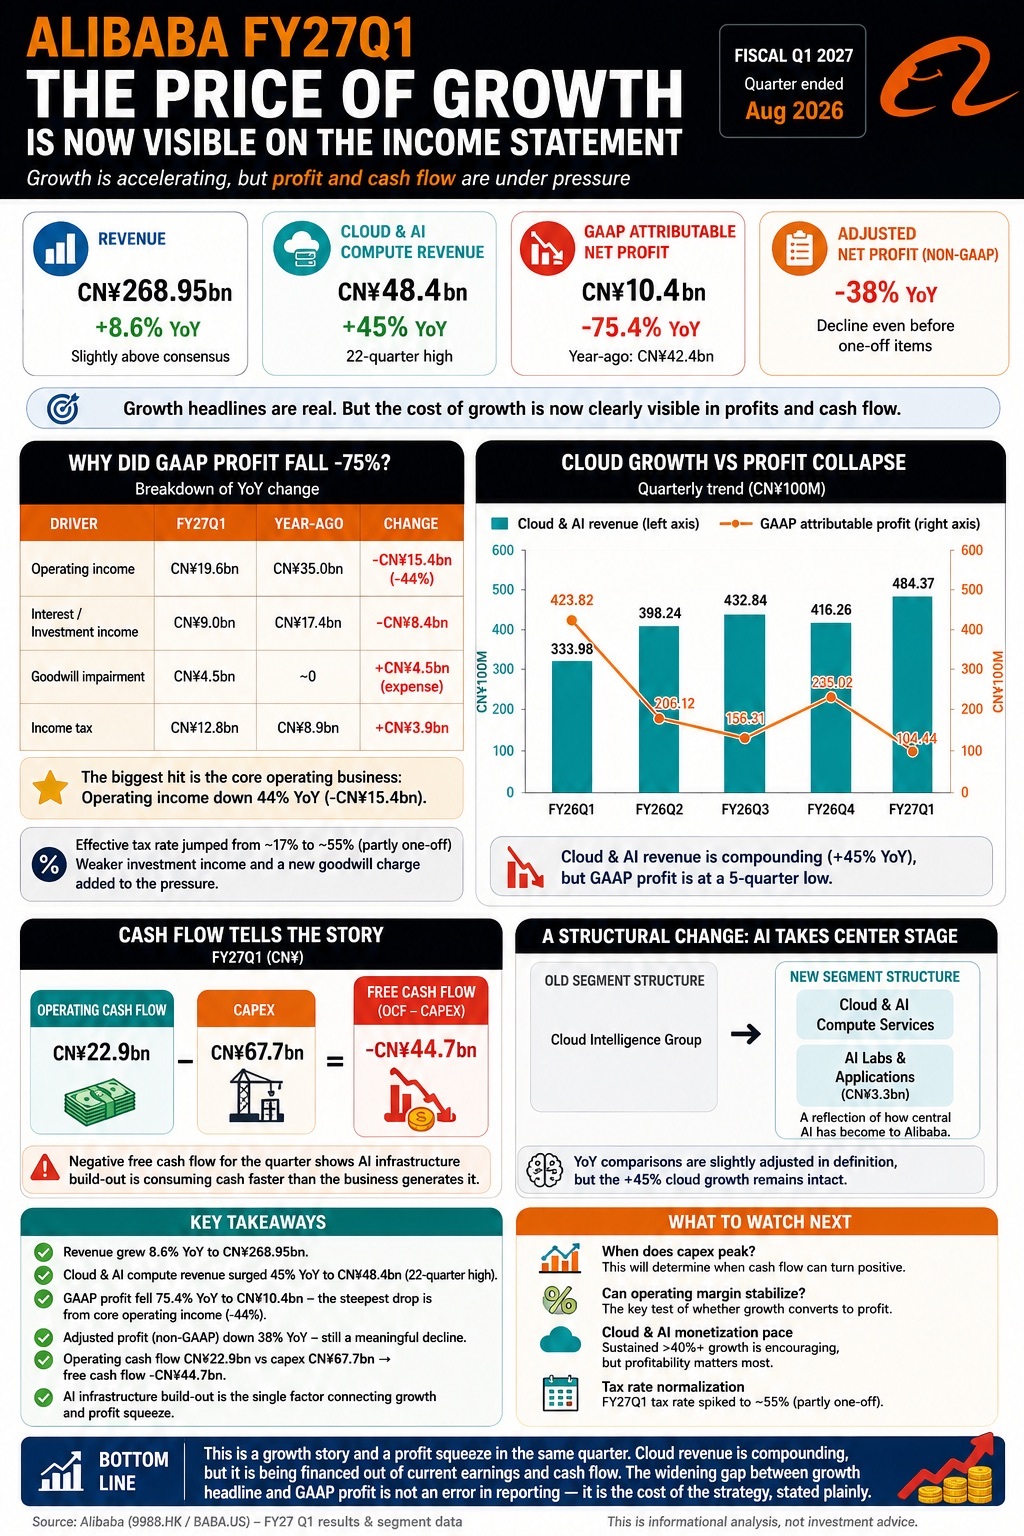
The headline was real
Alibaba's August 2026 quarter (fiscal Q1 2027) delivered exactly the kind of print that splits investors into two camps. Revenue of CN¥268.95bn was up 8.6% year over year, a hair above consensus [citation 1]. Cloud and AI compute revenue hit CN¥48.4bn, up roughly 45% — a 22-quarter high [citation 2]. On the face of it, the "re-rate on cloud" thesis had ammunition.
But that growth came at a visible price. GAAP attributable net profit fell 75.4% year over year to CN¥10.4bn, from CN¥42.4bn a year earlier [citation 1]. Even the commonly-quoted adjusted figure was down 38%. The gap between those two numbers — adjusted down 38% but GAAP down 75% — is where the real story lives.
The -75% is not an accounting illusion
The standard instinct is to dismiss a multi-quarter swing into one-off items. Here, that instinct is only partly right. The erosion breaks down into four forces:
| Driver | FY27Q1 | Year-ago | Change |
|---|---|---|---|
| Operating income | CN¥19.6bn | CN¥35.0bn | -15.4bn (-44%) |
| Interest / investment income | CN¥9.0bn | CN¥17.4bn | -8.4bn |
| Goodwill impairment | CN¥4.5bn | ~0 | +4.5bn expense |
| Income tax | CN¥12.8bn | CN¥8.9bn | +3.9bn |
The single largest hit is not an impairment — it is the core operating business itself, down 44% or CN¥15.4bn. Compounding that are a new CN¥4.5bn goodwill charge, weaker investment income, and a sharply higher effective tax rate (roughly 17% to 55%, partly one-off) [citation 1].
This matters for how you read the quarter: pointing at the -38% adjusted figure genuinely understates the damage, because even the pre-adjustment operating profit line is collapsing. Growth is real, but it is being bought at the expense of current profit.
Cash flow tells the same story more bluntly
Operating cash flow was CN¥22.9bn against CN¥67.7bn of capex [citation 1]. That works out to roughly -CN¥44.7bn of free cash flow in a single quarter — the clearest sign yet that the AI infrastructure build is consuming cash faster than the business generates it. The capex is the fuel for the cloud surge; it is also the reason the profit line looks like this.
A structural change worth noting
The quarter also quietly reorganized the reportable segments. "Cloud Intelligence Group" is now "Cloud & AI Compute Services", with a separate "AI Labs & Applications" line (CN¥3.3bn) carved out — a reflection of how central AI has become to the mix [citation 2]. The yoy comparisons are therefore slightly adjusted in definition, though the +45% magnitude holds.
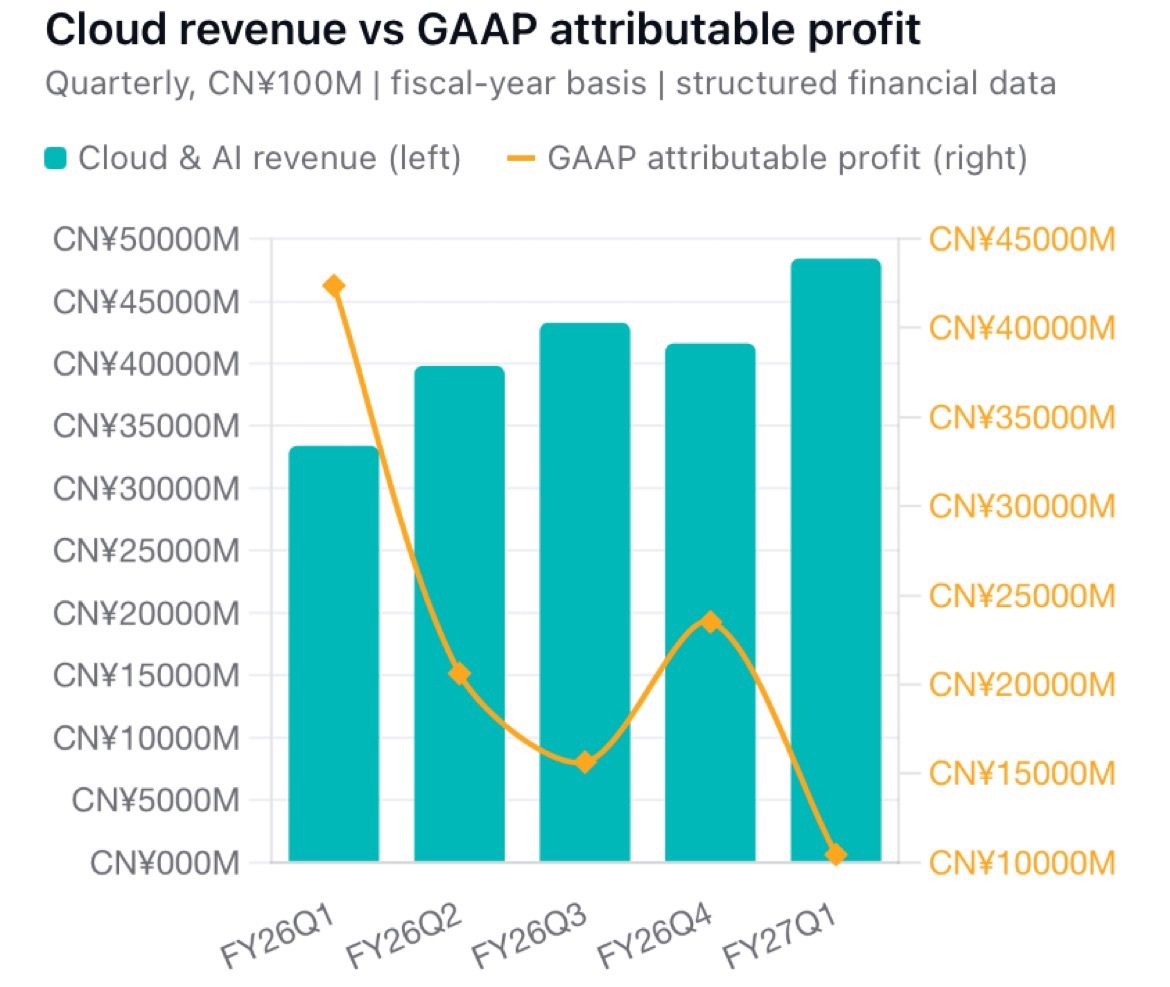
The divergence in one frame
>
Bottom line
This is a growth story and a profit squeeze in the same quarter, and they are connected by a single factor: the AI infrastructure build-out. Cloud revenue is compounding, but it is being financed out of current earnings and cash flow. The two numbers that decide the narrative from here are the same two the quarter put on the table — when capex peaks, and whether the operating margin can stabilize. Until then, the widening gap between the growth headline and the GAAP profit line is not an error in reporting. It is the cost of the strategy, stated plainly. [citation 1][citation 2]
Data source: alibaba (9988.HK / $Alibaba(BABA.US)) structured financial statements and business-segment data. Adjusted net profit figure is as reported in the company's non-GAAP disclosure. This is informational analysis, not investment advice.


The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.