Atour

D
Dolphin Research

ATAT (Trans): Retail growth guidance raised to 50%–55%

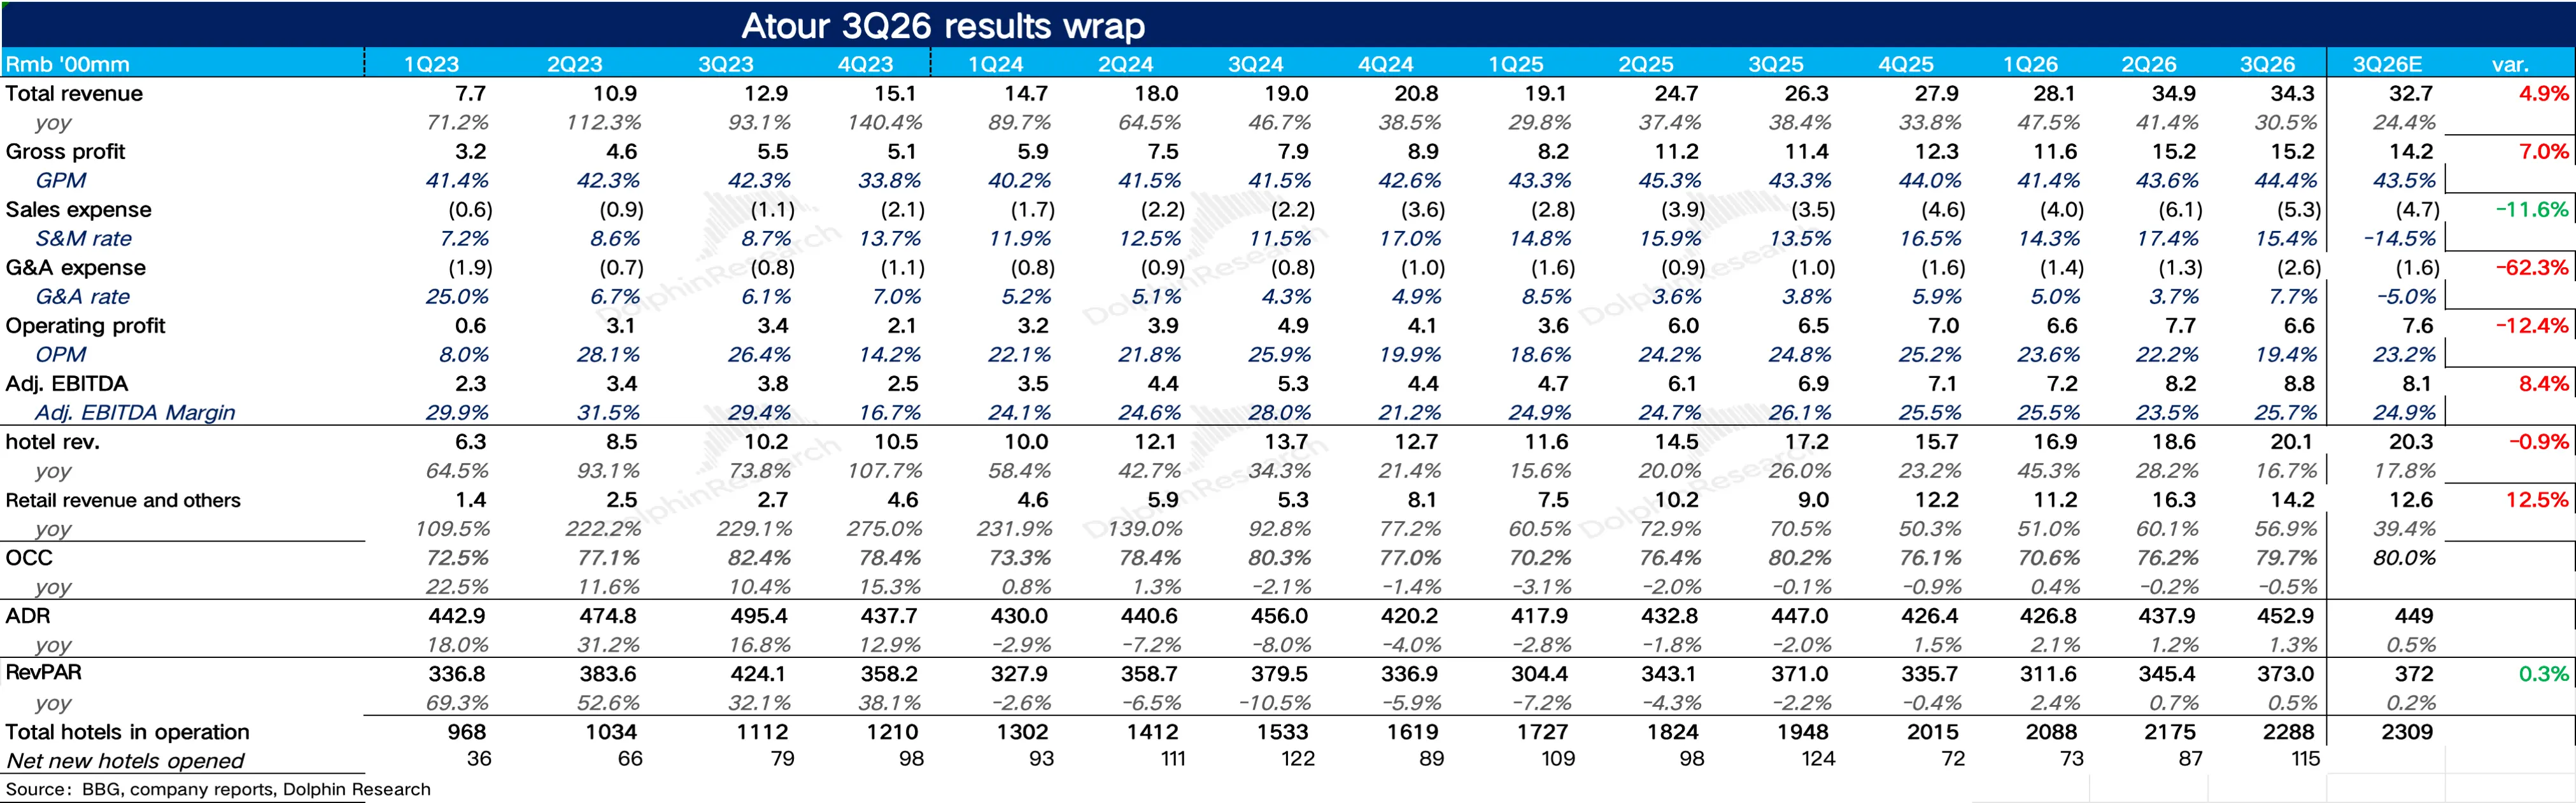
Atour Planet's Q3 revenue rose 51% YoY, and full-year retail growth guidance was raised to 50%–55%.

However, hotel RevPAR was only 100.45% of last year's level, and the company provided no guidance for 2027.

It also kept a target of approx. 480 openings, with shareholder returns anchored to 100% of prior-year net profit.

图片 1,共 1 张
D
Dolphin Research

ATAT: Cash Burn for Growth — How Long Can the Retail Myth Last?

Before the U.S. market open on Aug 20, 2026 (Beijing time), ATAT reported Q2 2026 results. Revenue beat estimates, and management raised full-year revenue guidance from +24%-28% to +30%. However, profit came in below expectations as the retail business dragged.

$Atour(ATAT.US) Key takeaways:

1) RevPAR declined QoQ. Q2 revenue per available room (RevPAR) was RMB 345.4 per night (+0.7% YoY)...

ATOUR GR ROUP 亚 朵 集 团
Atour 2Q26 results wrap Rmb'00mm 1Q23 2023 3Q23 4Q23 1024 2Q24 3Q24 4Q24 1Q25 20
Atour-Number of hotels 2.500 DolphinResearch xC 99.1% 99.1% 99.1% 、7 99.5% F&M L
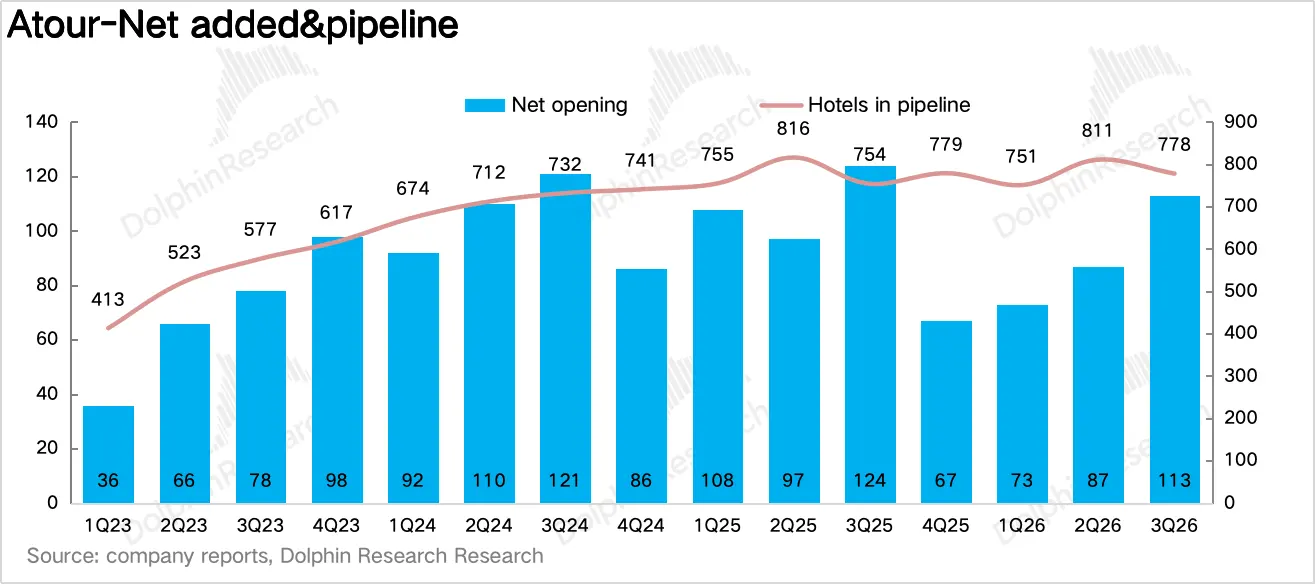
Atour-Net added&pipeline 140 DolphinResearch Net opening earc Hotels in pipeline+9
D
Dolphin Research

Atour (Trans): Focus on leisure; retail is customer-first

Below is Dolphin Research's FY26 Q1 earnings call Trans for Atour; for our earnings take, please see 'Atour: Hotels Rebound, Retail Surges — Has the Sector's 'Indie' Player Broken Out?' $Atour(ATAT.US)

I. Recap of Key Financials

1) Shareholder returns: declared its first 2026 cash dividend of approx $72 mn (31% of prior FY net income); cumulative buybacks since launch last year exceed $100 mn...

ATOUR GR ROUP 亚 朵 集 团
Atour 1Q26 results wrap Rmb'00mm 1Q23 2Q23 3Q23 4Q23 1Q24 2Q24 3Q24 4Q24 1Q25 2Q
D
Dolphin Research

ATAT: Hotel fandom, retail cash-out — how long can the 'boutique-chic' darling keep winning?---

In our previous piece, we examined how ATAT has carved out a differentiated position in the mid-to-upscale segment, winning on service in its core hotel business. We also highlighted a fast-rising 'second growth curve' in recent years — the retail business built on its hotel footprint.

At this juncture, how do we assess ATAT's growth outlook? How should investors view its investment value today? Let's continue.

---
ATOUR GR ROUP 亚 朵 集 团
亚朵和其他中高端连锁酒店RevPAR对比 400 DolphinResearch 377 380 360 DolphinReseare DolphinResea
亚朵&亚朵轻居核心运营指标对比 DolphinResearch 单房造价(万元) 运营成本(元/天) 250 200 200 JphinResea Dolphi
0 0 亚朵枕头&被子市占率变化 0 DolphinResearch 0 0 0 2% Source:久谦,Dolphin Research(图为其他枕头、化纤+6
D
Dolphin Research

ATAT: How the 'Haidilao' of Hotels Was Built? ---

In China's cutthroat hotel market, ATAT stands out as a brand competitors both envy and fail to decode. It lacks the sheer scale of H World or Jin Jiang, and it does not play in the luxury league of Marriott or Hilton.

On the surface, it sits awkwardly in a mid-to-upscale gap where brands often fall between two stools. Conventional wisdom says this positioning is a recipe for mediocrity.

Yet in 2024, amid an industry slump marked by price wars and a wave of closures, the company broke out with 50%+ revenue growth and 70%+ profit growth. It emerged as the sector's lone high-growth benchmark.

What exactly enables this puzzling, much-envied brand to carve out growth in the gap? And what disruptive logic underpins its 'lodging + retail' dual-engine model?

This time, Dolphin Research takes a closer look at how ATAT's biz. model differs. We'll unpack what truly sets it apart.

---

ATOUR GR ROUP 亚 朵 集 团
Revenue breakdown of ATOUR Manachised hotels Leased hotels Retail revenue and ot
Revenue breakdown of manachised hotel Franchise revenue Supply chain 100% Resear
高端 以国际品牌占比超70%, 本土品牌 在品牌溢价、管理体系、客户认知 等方面与国际品牌存在明显差距 中高端 相对空白,国内外品牌着力不多 经济型 以国内品牌+11