I'm LongbridgeAI, I can summarize articles.
Goldman Sachs expects S&P 500 third-quarter earnings per share (EPS) to rise 27% year-over-year, with Micron contributing 19% and NVIDIA 15%. The top ten companies are projected to account for 68% of the earnings growth. Meanwhile, the median S&P 500 company's earnings growth has slowed significantly to 9%, down from 14% in the second quarter, indicating that market earnings and performance are increasingly concentrated among a few AI and energy leaders
The US stock market's third-quarter earnings season is set to fully kick off next week. Although the S&P 500's earnings growth rate may hit its highest level since 2021, this growth is highly concentrated among a few tech and energy giants. Earnings momentum is weakening for small- and mid-cap stocks and most other industries, further exacerbating the divergence between index performance and individual stock returns.
According to Goldman Sachs' latest forecast, the S&P 500's third-quarter EPS year-over-year growth rate is expected to reach 27%, the highest since 2021. However, this growth relies heavily on a handful of companies: memory chipmaker Micron and NVIDIA are expected to collectively contribute about one-third of the index's earnings growth. In contrast, the median EPS growth rate for S&P 500 constituents is just 9%, a further decline from 14% in the second quarter.
Earnings concentration and narrowing market breadth are becoming core risks monitored by investment banks. Goldman Sachs points out that market breadth has fallen to its lowest level since the dot-com bubble. While the S&P 500 is only 2% away from its historical high, the median stock has fallen an average of 17% from its respective peak.
Morgan Stanley strategist Mike Wilson believes that the divergence between the index nearing historical highs and a large number of individual stocks experiencing bear-market-level drawdowns "will eventually converge in some way," with bond market volatility potentially serving as the final "arbiter."
Earnings Growth Increasingly Reliant on a Few Stocks
Data from Goldman Sachs' latest report shows that Micron is expected to contribute 19% of the S&P 500's third-quarter earnings growth, while NVIDIA contributes 15%. The incremental earnings from these two companies alone are roughly equivalent to the total contribution from the remaining 490 constituents.
Other major contributors include Meta, Alphabet, and Broadcom, contributing 7%, 6%, and 5%, respectively. ExxonMobil, Chevron, and Marathon Petroleum have benefited from rising oil prices driven by tensions in the Strait of Hormuz, with Boeing also ranking among the top ten. The top ten contributors are expected to account for 68% of third-quarter earnings growth, significantly higher than the 47% in the first quarter and 48% in the second quarter.
In terms of themes, AI infrastructure is the primary driver of earnings growth. Goldman Sachs estimates that "AI infrastructure (excluding hyperscale cloud providers)" will contribute 54% of third-quarter earnings growth, with hyperscale cloud providers contributing another 19%. Together, they account for approximately three-quarters of the S&P 500's earnings growth.
Sector divergence is also evident. Influenced by tensions in the Strait of Hormuz and rising oil prices, the energy sector's third-quarter EPS is expected to grow by 109%. The information technology sector is projected to grow by 64%. Combined, these two sectors contribute about 80% of the quarterly earnings growth. In contrast, the consumer discretionary sector is expected to see virtually zero earnings growth, while the consumer staples sector is projected to experience negative growth.
Goldman Sachs also notes that analysts expect earnings growth to slow sequentially in nearly all sectors, with information technology and communication services being the only exceptions. Since the start of the third quarter, margin expectations for the median S&P 500 company have been lowered by 11 basis points, with downward revisions seen across all industries except information technology.
Micron Reports First: Market Focuses on Sustainability Beyond High Growth
Micron was the first to release its financial results on September 30, delivering strong performance: adjusted EPS came in at $33.42, beating the market expectation of $31.83; adjusted revenue increased from $11.2 billion in the same period last year to $54.2 billion; and gross margin reached 87%, significantly higher than the 45.7% recorded a year ago. The company's revenue guidance for the next quarter is between $60 billion and $63 billion, also well above the market consensus estimate of $56.77 billion.
However, the substantial beat did not lead to a synchronous surge in the stock price, as the market had already priced in higher growth expectations. Morgan Stanley analyst Joe Moore pointed out before the earnings release that market discussion around Micron has "shifted significantly from 'how good can it get' to 'how long can this momentum last'."
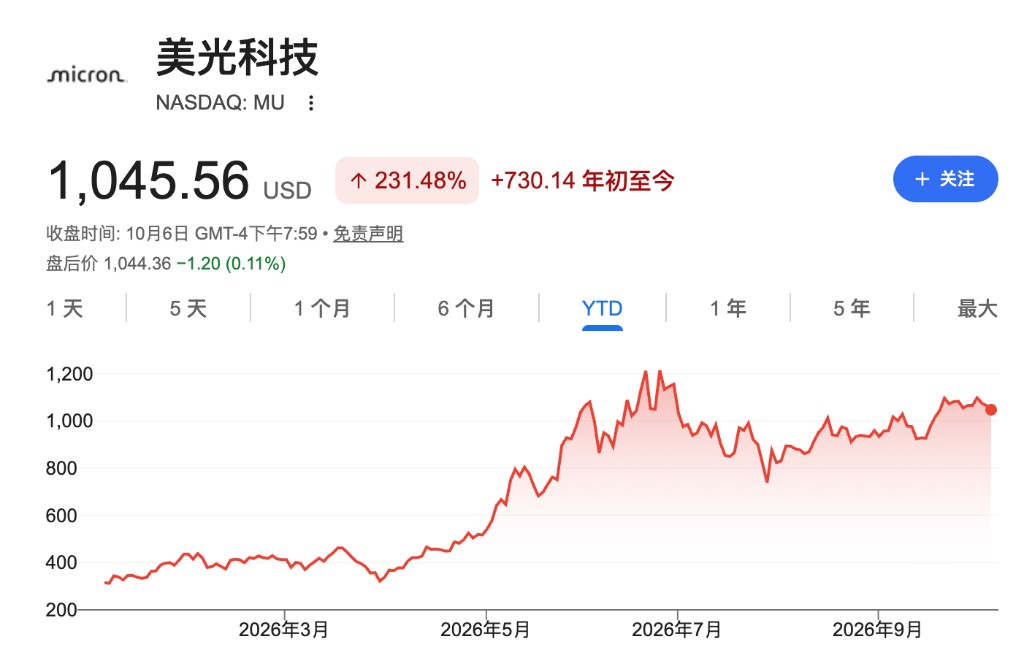
Year-to-date, Micron's stock price has risen by over 231%, making it one of the best-performing stocks in the Philadelphia Semiconductor Index. With significant increases in both earnings and stock price, market attention has shifted from whether short-term results will exceed expectations to whether AI memory demand and high profitability levels can be sustained.
Hyperscale Cloud Providers Increase Capex; Market Expectations May Still Be Low
The core support for earnings growth in AI-related companies is the continued increase in capital expenditure by hyperscale cloud providers. The market expects these companies' third-quarter capex to rise by 116% year-over-year, up from 87% in the second quarter. Goldman Sachs predicts that capex growth will exceed 50% by 2027, with the total scale surpassing the current market consensus estimate of approximately $1.1 trillion.
Historical experience shows that market forecasts for hyperscale cloud providers' capex have consistently lagged behind actual growth rates: in early 2024, the market expected full-year growth of 19%, but actual growth reached 54%; in early 2025, the expectation was 22%, while actual growth was 73%; earlier this year, the forecast was 36%, with the current actual growth rate approaching 96%. Therefore, Goldman Sachs believes that the market's expectation of 37% capex growth for 2027 may also be too low.
Accelerating cloud business revenue is also supporting this round of capital expenditure. Cloud revenue growth for hyperscale cloud providers such as Amazon, Google, Microsoft, and Oracle accelerated to 48% in the second quarter, and Goldman Sachs expects it to rise further to 55% in the third quarter. Among them, the total backlog of cloud business contracts for Amazon, Google, and Microsoft has approached $1.7 trillion.
However, the rapid expansion of AI capital expenditure is accompanied by higher financing needs, a significant portion of which is being funded through debt. Additionally, two accounting factors boosted corporate earnings in the first half of this year: gains from marking-to-market equity stakes in private AI companies held by large tech firms, and tariffs refunded by the US Treasury.
Goldman Sachs estimates that gains from the revaluation of equity stakes in private AI companies by large tech firms amounted to approximately $150 billion in the second quarter, equivalent to 12% of the S&P 500's EPS. The approximately $69 billion in tariffs refunded by the US Treasury in the third quarter is equivalent to about 6% of pre-tax profits for US corporations. Goldman Sachs has excluded the former from its year-over-year quarterly comparisons and does not expect similar-scale gains to recur in the third quarter.
Index Nears Historical Highs as Market Breadth Continues to Narrow
Beyond earnings concentration, market performance also exhibits rare high concentration. The top ten constituents of the S&P 500 currently account for about 40% of the index's market capitalization and 37% of expected earnings. Goldman Sachs data shows that the average realized correlation coefficient among S&P 500 constituents has dropped to 0.06, the lowest level in the bank's ten years of data, implying that the overall index performance is increasingly dependent on a few AI and energy leaders.
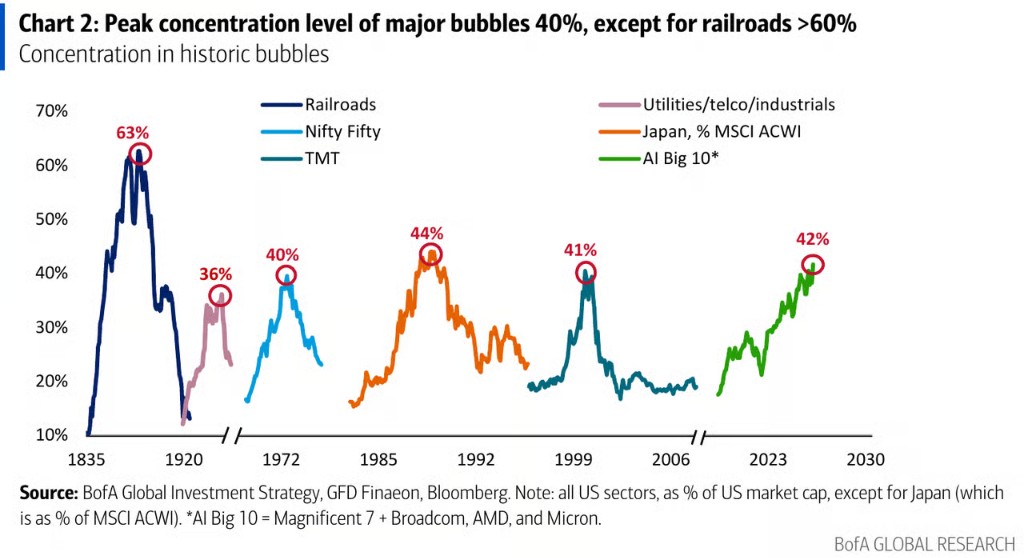
Bank of America Merrill Lynch strategist Michael Hartnett also pointed out that currently, about 400 S&P 500 constituents have fallen below their 50-day moving averages, and about 300 have dropped below their 200-day moving averages. He calculated that the market capitalization concentration of the "AI Big 10"—the Mag 7 plus Broadcom, AMD, and Micron—has reached 42%, exceeding the 40% during the "Nifty Fifty" era, the 41% during the TMT bubble, and the 36% in the 1920s. In comparable historical cases, only Japan's market at 44% and US railroad stocks in 1881 at 63% were higher than this level.
Nevertheless, investment banks remain relatively optimistic about overall third-quarter results. JPMorgan's market intelligence division adjusted its market rating to "tactically bullish" in its Q3 earnings preview report, suggesting that after second-quarter earnings growth reached 52%, the market's expectation of approximately 29% earnings growth for the third quarter may still be conservative. It expects revenue and earnings growth across all 11 sectors.
FactSet data shows that if expectations are met, the S&P 500 will achieve year-over-year revenue growth of over 10% and earnings growth of over 25% for the third consecutive quarter, with profit margins reaching the second-highest level in history.
Goldman Sachs currently expects the S&P 500's EPS to reach $375 in 2026, a 36% year-over-year increase, and to rise further to $415 in 2027. It sets a year-end target of 8,000 points and a 12-month forward target of 8,700 points.
As the largest weighted stock in the S&P 500 and the second-largest contributor to third-quarter earnings growth, NVIDIA is scheduled to release its earnings in the third week of November. In the current environment of highly concentrated earnings, its results and guidance on future AI capital expenditure and demand may become a key node in determining whether this round of US stock earnings momentum can continue to advance.