
 I'm LongbridgeAI. Here is the key information I extracted
- Bernstein highlights that Apple maintains lower capital expenditures at roughly 2% of revenue and robust shareholder returns, including $102 billion returned in fiscal 2026.…
TradingKey - On November 12, Eastern Time, Apple (AAPL) shares rose to $359.3, hitting another record high. Amid a sell-off in AI concept stocks, lower capital expenditures, steady cash flow, and continuous share repurchases have made Apple a choice for capital seeking defensive tech allocations. Bernstein believes the market is pricing Apple like a high-quality consumer company.
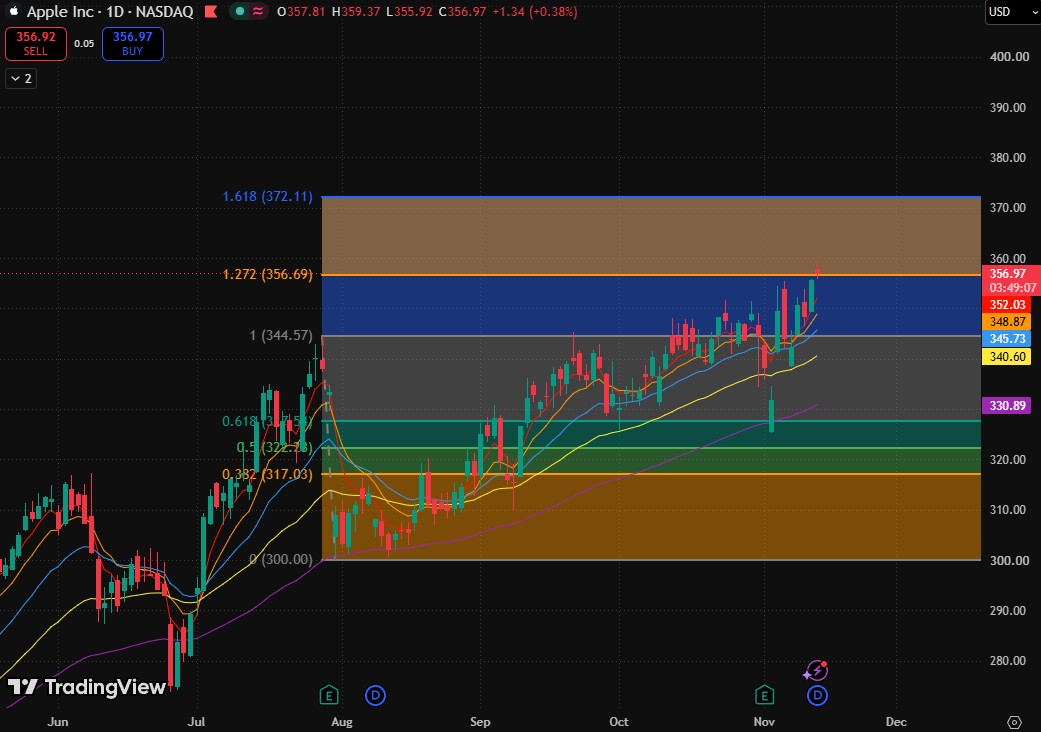
Apple stock price chart, Source: TradingView
Apple’s Cash Flow Advantage in Focus Amid Lighter AI Capex Burden
Bernstein noted that Apple's capital expenditures account for approximately 2% of revenue. By partnering with Google (GOOGL) and running certain AI models on-device, the company has reduced its reliance on expensive AI servers.
This leaves Apple less exposed to the cash flow squeeze from massive data center construction. When investors begin to worry about returns on AI investments, financing costs, and the sustainability of equipment procurement, Apple's appeal stems from a different logic: participating in AI applications while retaining more capital for shareholder returns.
In fiscal 2026, Apple returned approximately $102 billion to shareholders through buybacks and dividends. Bernstein expects the company will still have the capacity to repurchase shares equivalent to approximately 3.0% and 3.3% of its market capitalization in fiscal 2027 and 2028, respectively. Sustained buybacks reduce share count, helping support earnings per share while bolstering investor confidence in its earnings stability.
Apple's P/E Hits Record 37x: Why Is the Market Willing to Pay a Premium?
Apple currently trades at roughly 37 times expected calendar year 2027 earnings per share, with its relative forward P/E reaching twice that of the S&P 500, leaving both metrics at historical highs.
This premium does not stem from industry-leading growth. Bernstein noted that while Apple's growth does not stand out among megacap tech companies, its revenue streams are more predictable: roughly 1.4 billion active iPhone users generate continuous upgrade demand, and the services business contributes about 40% of gross profit, further strengthening earnings durability.
Customer loyalty and pricing power also support this view. Citing surveys, Bernstein noted that iPhone brand retention is around 90%, with price sensitivity lower than that of other mainstream smartphones. This means the company is better positioned to defend its customer base and product margins.
The firm therefore believes Apple is better compared with high-quality consumer companies such as Costco (COST) and Walmart (WMT). With the two trading at forward P/E ratios of roughly 46 times and 39 times, respectively, Apple's 37-times valuation does not stand out in this group.
The stock reaching a new high reflects the market's willingness to pay a premium for cash flow and earnings visibility. However, record-high valuations also mean that Apple must continue to deliver on upgrade demand, services growth, and share repurchases going forward so that EPS growth keeps pace with the stock price, rather than relying on safe-haven inflows to continuously lift multiples.
Find out more