
longbridgelongbridge
  • Platform Features
    Features
    Investment ProductsPrivate Wealth ManagementTrading ToolsMarket Data ServicesAnalysis ToolsNews ServicesFor Developers
    Account Types
    For IndividualsFor Institutions
  • Café
longbridge
© 2026 Longbridge|Terms of ServicePrivacy Policy
TheInvestingIguana

TheInvestingIguana

AssetsTop 1%ReturnsTop 17%

The Investing Iguana breaks down SGX dividends and CPF/SRS retirement planning in plain English, so you can invest calmly toward retirement

The Investing Iguana breaks down SGX dividends and CPF/SRS retirement planning in plain English, so you can invest calmly toward retirement

AJBURate Of Return
1Following133Followers308Likes & Bookmarks
TheInvestingIguana
TheInvestingIguana
ArticlesOriginalFollowingFollowersStocks mentioned

Who to follow

T
TheInvestingIguana6 hours ago
Featured

Anthropic Lost $42 Billion. Only About $8 Billion Came From Running the Business.

Wed 30 Sep 2026 | Evening

The Numbers

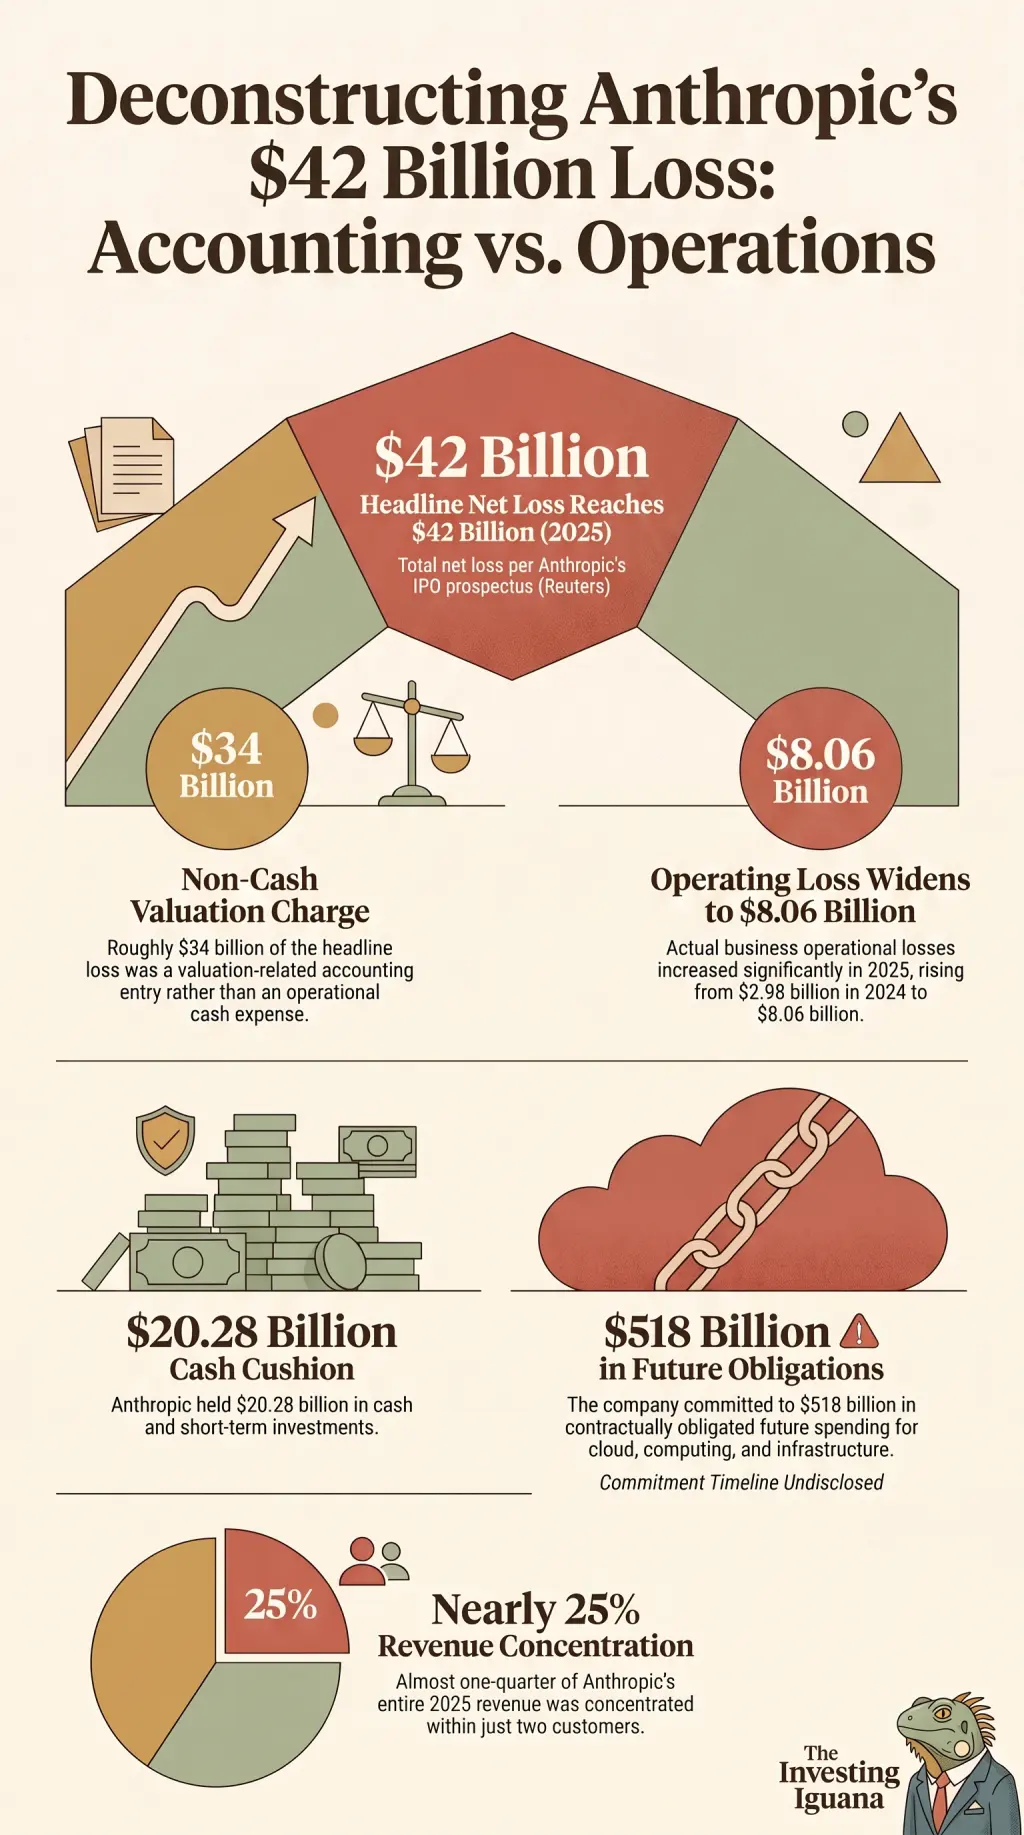
Reuters reports, citing Anthropic's IPO prospectus, a net loss of nearly US$42 billion in 2025. Roughly US$34 billion of that was a valuation-related accounting charge. The operating loss still widened to US$8.06 billion from US$2.98 billion in 2024. Anthropic had US$20.28 billion in cash and short-term investments against US$518 billion of future cloud, computing and infrastructure obligations, and nearly a quarter of 2025 revenue came from two customers. Today's video asks which of those figures is firmest: the loss, the obligations, or the customers.

My Personal Take

My first reaction to US$42 billion was that it had to mean the business was failing. What I almost missed is that US$34 billion of it is an accounting charge tied to valuation, which leaves an operating loss of US$8.06 billion. This morning I wrote about giving CDL credit for cash that has not arrived. The same discipline applies here, in reverse: the US$518 billion is the contracted side of this story, and the customer spending behind it is the side I cannot see. I do not know the period those obligations run over, so I cannot say how large they are in any one year. A disclosed schedule by year would change how I read this. 🦖

📺 Free YouTube: https://youtu.be/nY5UelMXUvU

⭐ Members Edition YouTube: https://youtu.be/kB1All2xb2Q

📩 Substack: https://investingiguana.com/p/anthropic-lost-42-billion-only-about

Not financial advice. Iggy's Forensic Compliance Standards apply.

- YouTube

- YouTube

YouTube 上盡享你喜愛的影片和音樂、上載原創內容,並與親友和世界各地的人分享。

youtu.be
图片 1,共 1 张Long image
Anthropic Grew Revenue 12x And Lost $42B
T
TheInvestingIguana14 hours ago
Featured

Maybank Reiterates BUY on CSE Global at S$2.25 After S$190.5 Million of US Contracts

Wed 30 Sep 2026 | Analyst Update

$CSE Global(544.SG) 

The Numbers

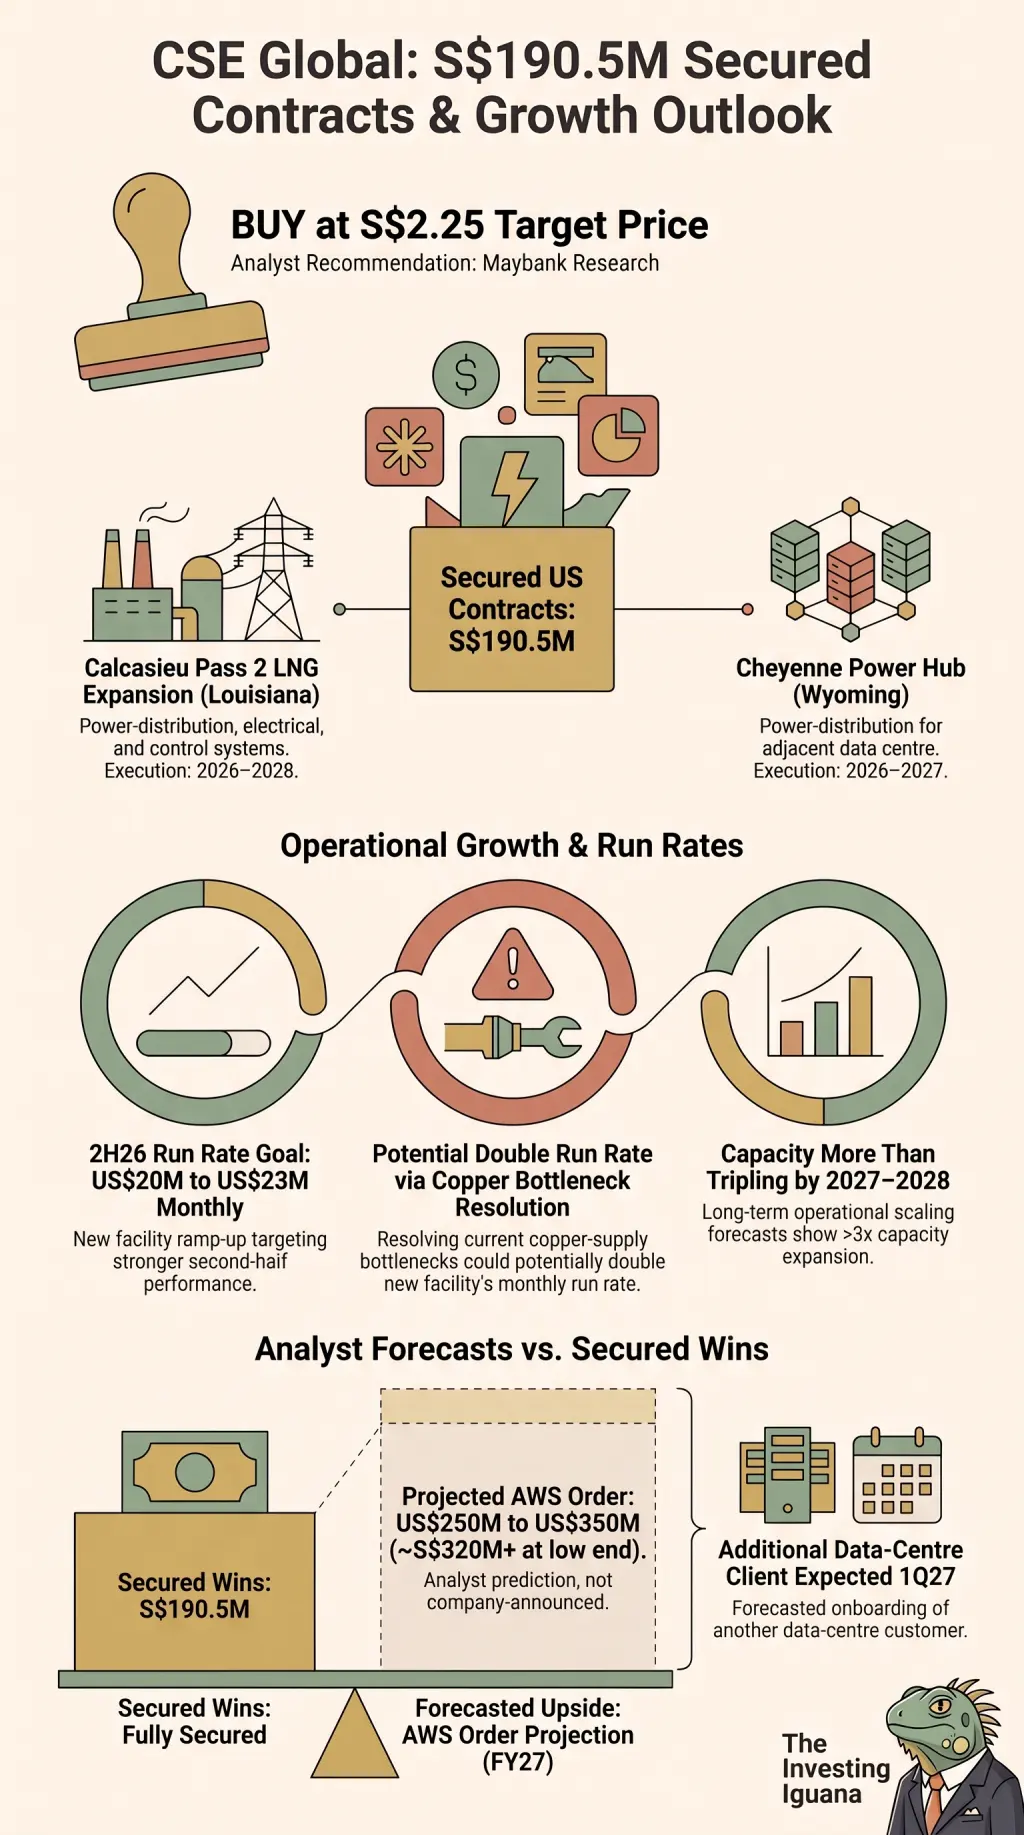
Maybank Research reiterated its BUY on CSE Global with a S$2.25 target price after two new US contracts worth a combined S$190.5 million. The first covers power-distribution centres and integrated electrical and control systems for the Calcasieu Pass 2 LNG expansion in Louisiana, executed from 2026 to 2028. The second is a follow-on for the Cheyenne Power Hub in Wyoming, supplying power-distribution infrastructure for an adjacent data centre in 2026 to 2027.

Maybank expects a stronger 2H26 as CSE's new facility reaches a monthly run rate of US$20 million to US$23 million, and says resolving the copper-supply bottleneck could potentially double that run rate. It also forecasts capacity more than tripling by 2027 to 2028, another data-centre customer by 1Q27, and an AWS order of roughly US$250 million to US$350 million for FY27, which it expects could arrive by December. The contracts are secured. The AWS order and the new client are Maybank forecasts, not company-announced orders.

My Personal Take

My first reaction to S$190.5 million was that it was the news. What I almost missed is that the forecast in the same note is larger: the low end of Maybank's AWS range, US$250 million, is about S$320 million at Tuesday's 1.2780 USD/SGD, and no company has announced it. It took me a while to keep the signed and the forecast apart in my head, because both sit under one BUY. A company announcement of the AWS order would change how I weigh this, and so would December passing without one. 🦖

Not financial advice. Iggy's Forensic Compliance Standards apply.
图片 1,共 1 张Long image
CSE Global

CSE Global

SG544

T
TheInvestingIguana14 hours ago

US 30-Year Yield at Its Highest Since 2002, and MAS Names Five Managers

Wed 30 Sep 2026 | Morning

The Numbers

Overnight in the US, the Dow closed at 51,349.92 (-0.26%), the S&P 500 at 7,670.84 (-0.17%) and the Nasdaq at 26,797.54 (-0.09%). The VIX eased to 16.04. FXCM ties the Dow's decline to Boeing falling to its lowest level of 2026 after the FAA held up the 737 Max 10, and to caution ahead of Core PCE data forecast at 3.4% year-on-year. Brent closed at US$102.59 (-2.6%). BT reports the US 30-year Treasury yield rose to its highest since 2002. USD/SGD is 1.2780. The STI closed Tuesday at 5,715 (-0.25%), and SGX opens at 9am on the last trading day of September.

In Singapore, MAS placed S$1.45 billion with five asset managers in the third EQDP batch, taking commitments to S$5.4 billion across 14 managers. BT also carries the SGX chairman calling the number of listed companies an "outdated metric" of the market's success, and a proposal from Zheneng Jinjiang Environment to take the company private at S$0.70 a share or issue new shares.

My Personal Take

My first reaction to the 30-year headline was that it was a US story. What I almost missed is where it meets today's Singapore news: MAS is placing S$1.45 billion with equity managers while the SGX chairman argues the count of listed companies is the wrong measure. I have been treating SGS yields as the local channel for US yields, and I do not yet have a Singapore print showing this move arriving. A rise in SGS yields at the open would tell me it is. A flat curve would tell me it is not. 🦖

Not financial advice. Iggy's Forensic Compliance Standards apply.
图片 1,共 1 张Long image
T
TheInvestingIguana1 day ago, 05:23 AM
Featured

MAS S$20 Million for Market Makers, Explained

Tue 29 Sep 2026 | Midday

The Numbers

MAS announced S$1.45 billion for fund managers and S$20 million for market makers today. Only the smaller number reaches your trading account. The S$20 million pays firms to quote tighter bid-ask spreads on around 80 small and mid-cap stocks until 31 December 2028. The spread is a cost on every trade: a 2% gap on a S$10,000 purchase costs about S$200 round-trip, against S$100 at 1%. Today's episode covers what the grant does to that gap, and why it is not a price safety net under those stocks.

My Personal Take

My first reaction to the S$1.45 billion was that it was the headline and the S$20 million was a footnote. What I almost missed is that the footnote is the only line that touches a retail trading screen. It took me a while to connect a grant paid to firms with a cost I pay myself, because the spread does not show up as a fee. I keep coming back to the S$200 on a S$10,000 purchase, since a gap like that sits unnoticed. A published figure for how much the spreads actually narrow would change how I read this. 🦖

📺 YouTube: https://youtu.be/yKTYlyKw59Y

📩 Substack: https://investingiguana.com/p/how-mas-wants-small-cap-trading-to

Not financial advice. Iggy's Forensic Compliance Standards apply.

- YouTube

- YouTube

YouTube 上盡享你喜愛的影片和音樂、上載原創內容,並與親友和世界各地的人分享。

youtu.be
图片 1,共 1 张Long image
T
TheInvestingIguana1 day ago, 12:46 AM
Featured

US Yields Near 5.23%, Brent Above US$105, and CDL's Three-Year Plan

Tue 29 Sep 2026 | Morning

The Numbers

Overnight in the US, the Dow closed at 51,481.51 (-0.67%), the S&P 500 at 7,683.69 (-0.77%) and the Nasdaq at 26,820.38 (-0.92%). The VIX rose 8.07% to 16.07. Kiplinger attributes the slide to the US-Iran war, bond yield pressure and AI anxiety, with the 10-year Treasury near 5.22% to 5.23%. Brent settled at US$105.29 (+0.93%), and BT reports the US and Iran will hold separate talks with mediators, both pessimistic about a deal before the midterms. USD/SGD is 1.2774. The STI closed Monday at 5,729.02 (+0.31%), and SGX opens at 9am.

$CityDev(C09.SG) 

Two Singapore items I'm reading against the balance sheet. City Developments (CDL) is Zone 5, Red Zone: interest coverage of 0.99x on the headline reading (my own calculation gives 0.84x) against a 4.0x floor, net gearing of 69% (FY24) against a 35% ceiling, and 15.7x net debt/EBITDA against my 10x red flag. BT ran Sherman Kwek's three-year plan for CDL, plus a report that CDL will hire a dedicated CEO for fund management. Separately, Mapletree Industrial Trust is selling a Minnesota data centre property for US$9.8 million.

My Personal Take

My first reaction to the CDL headlines was that a plan to drive returns sounded like an answer to the numbers above. It took me a while to see that a fund management push is fee income, which is not the same thing as lower debt. The test I set for the 28 September review was signed, priced asset transactions, and the headlines describe a plan and a hire, not a priced deal. With the 10-year near 5.23%, higher rates weigh more on a company covering interest less than once. A stated debt reduction figure would change how I read it. 🦖

Not financial advice. Iggy's Forensic Compliance Standards apply.

图片 1,共 1 张Long image
CityDev

CityDev

SGC09

T
TheInvestingIguana2 days ago, 08:23 AM

FeaturedWhere to Park Your Cash for Higher Yield: T-Bills vs Fixed Deposits vs SSB

Where to Park Your Cash for Higher Yield: T-Bills vs Fixed Deposits vs SSB (Updated for 1.92% T-Bill Yields) Fixed deposits haven’t kept pace. Here’s where $10k to $100k actually earns the most right n...

Where to Park Your Cash for Higher Yield T-Bills vs Fixed Deposits vs SSB - upda
加坡AULAISINGAP The Rate Gap Is Real 6-MonthT-Bill Most Fixed Deposits N DOLLARS N
Why This Comparison Matters Now The gap between the lazy default and the actuall
2 In hThis Article+14
UOB

UOB

SGU11

Retire Well Now
T
TheInvestingIguana2 days ago, 08:20 AM
Featured

Where to Park Your Cash for Higher Yield: T-Bills vs Fixed Deposits vs SSB (Updated for 1.92% T-Bill Yields)

Mon 28 Sep 2026 | Daily Long-Form

Today's long-form is the ⭐ Members Edition, made free for everyone.

The Numbers

The 6-month T-bill just cleared at 1.92%, its highest print this year. Most fixed deposits are still under 1.70%. CPF OA pays 2.5% for October to December 2026, but that money cannot be touched in an emergency. At S$100,000, DBS balance bands can cut the effective FD rate on anything above S$20,000. Syfe Cash+ Enhanced shows a 3.0% projected return, but the data behind it is dated 17 November 2025, so I treat that figure as stale.(Correct me here if you have updated data, so that we can share with the community). 

My Personal Take

My first reaction to 1.92% was to compare it with the fixed deposit rates I keep seeing advertised. What I almost missed is that the headline rate is not what decides this. Your balance band and how soon you might need the cash do. It took me a while to connect the CPF OA 2.5% to the T-bill number, because they answer different questions: one pays more but is locked, the other pays less but you can reach it. That split between cash you may need soon and cash you can leave alone is where the full piece spends its time. Let the numbers speak, kopi-o in hand. 🦖

⭐ Members Edition YouTube: https://youtu.be/3bDVf2mOiBE

📩 Substack: https://investingiguana.com/p/where-to-park-your-cash-for-higher-d75

Not financial advice. Iggy's Forensic Compliance Standards apply.

- YouTube

- YouTube

YouTube 上盡享你喜愛的影片和音樂、上載原創內容,並與親友和世界各地的人分享。

youtu.be
图片 1,共 1 张Long image
T
TheInvestingIguana2 days ago, 03:30 AM
Featured

Iggy's Journal: Four New SGX ETFs, But Are They Really Local?

28 September 2026, Morning

Podcast

This morning I flagged the Xtrackers expansion as a genuinely useful addition to SGX's lineup. Sitting with it a bit longer, I think there's a sharper question underneath the good news.

The Numbers

Does trading a fund in Singapore dollars make the investment itself Singaporean? I don't think it does, and I don't want to confuse the exchange where a fund trades with the actual markets where the underlying companies operate. These four new ETFs, tracking the S&P 500, Nasdaq 100, and MSCI World, are genuinely easier to access now, dual-currency, local trading hours, no need to route through a US broker. But the overseas exposure underneath them hasn't changed at all. The headline fee range runs from 0.03 to 0.20 percent a year, which sounds like the whole cost story, but it isn't. Brokerage charges, bid-ask spreads, trading volume, index tracking accuracy, distribution treatment, and foreign-currency movements all sit on top of that headline number and shape your actual outcome.

My Personal Take

For a CPF or SRS investor, the distinction between these three funds matters more than the shared "easier access" headline suggests. MSCI World isn't the same bet as the S&P 500, one is global developed markets, the other is US-only. The Nasdaq 100 is a much more concentrated technology and growth tilt than either of the other two, and concentration cuts both ways. None of that changes because the ticker now trades on SGX instead of a US exchange. I'd rather people pick based on what they're actually exposed to than on the comfort of seeing it priced in Singapore dollars. Full breakdown of how these four funds actually differ, and what the real all-in cost looks like beyond the headline fee, is in today's episode.

📺 YouTube: https://youtu.be/6ZlceCMeoyk

📩 Substack: https://investingiguana.com/p/four-new-etfs-land-on-sgx-in-october

- YouTube

- YouTube

YouTube 上盡享你喜愛的影片和音樂、上載原創內容,並與親友和世界各地的人分享。

youtu.be
图片 1,共 1 张Long image
T
TheInvestingIguana2 days ago, 12:49 AM
Featured

Iggy's Journal: US Treasury Yields Hit a 2007 High. Singapore's Own Bonds Just Followed.

28 September 2026, Morning

Yesterday's video asked why a US Treasury shock barely touched CPF and T-bills. This morning there's a more direct answer sitting in the data: Singapore Government Securities did move, just not through the channel most people check first.

The Numbers

Wall Street closed Friday's session with a genuine tech-led rally, Dow up 0.93 percent to 51,828.62, S&P 500 up 0.51 percent to 7,743.41, Nasdaq up 0.48 percent to 27,068.72, driven by gains in Microsoft, Qualcomm, and Dell as crude oil eased and Treasury yields pulled back slightly from their 2007-era peak. Brent fell 2.14 percent to $104.32 on signs of a possible compromise over Middle East maritime transit. USD/SGD sits at 1.2771. Back home, the actual transmission channel showed up in the SGS curve for the week: the 2-year yield rose 11 basis points to 1.93 percent, the 5-year climbed 5 basis points to 2.21 percent, the 10-year added 4 basis points to 2.47 percent, and 3-month SORA OIS repriced to 1.59 percent, all moving in response to global bond pressure and August's core inflation print of 2.2 percent. Separately, MAS is reviewing its stance on cross-border stablecoins under its Payment Services Act consultation, considering tokens co-issued by a domestic and international operator, and DWS expanded its Xtrackers ETF lineup on SGX to include direct, dual-currency access to the S&P 500, Nasdaq 100, and MSCI World.

(more in comment; out of space)

图片 1,共 1 张Long image
T
TheInvestingIguanaSep 27 at 08:06 AM
Featured

Iggy's Journal: US Treasury Yields Just Hit Their Highest Level Since 2007. Your CPF Statement Won't Show It.

27 September 2026, Evening

Video Release

The question I kept coming back to this week wasn't why US Treasury yields reached 5.22 percent. It was why my own CPF statement barely reacted to something that size. That gap is the whole story.

The Numbers

This is a genuine global bond shock, the kind of move that reprices risk everywhere it touches. But Singapore's transmission mechanism runs differently, CPF Ordinary Account still sits at its guaranteed 2.50 percent regardless of what Washington's bond market does, and this week's 6-month T-bills yielded between 1.70 and 1.92 percent, both untouched by the headline number. The risk hasn't vanished just because your statement looks calm, it's moved somewhere else, into the balance sheets of specific REITs that actually have to refinance debt in this environment. Sector medians currently sit at 39.6 percent gearing and 3.3 times interest coverage, numbers that describe an entire sector's cushion, not any one name's.

My Personal Take

I don't want anyone reading a US Treasury headline and assuming their own portfolio absorbed the same shock, because it didn't, not directly, and not evenly. CPF's guarantee doesn't move with a foreign bond market, and neither does a T-bill you've already locked in. What actually moves is a REIT's refinancing cost the next time its debt comes due, and that's a company-by-company question, not a headline-level one. A sector median tells you the general cushion, it doesn't tell you whether the specific REIT sitting in your own portfolio is closer to the healthy end of that range or closer to the edge. I wouldn't let a dramatic number out of Washington replace an actual forensic check of the names you're holding. Full breakdown of which structural factors actually matter for refinancing risk is in today's video.

Not financial advice. Iggy's Forensic Compliance Standards apply

图片 1,共 1 张Long image
T
TheInvestingIguanaSep 27 at 03:38 AM

Iggy's Journal: A Week of Small Numbers Adding Up to One Story

27 September 2026, Morning

Looking back at the week, I don't think any single piece was the story. The story was underneath all of them, and I only really saw it in hindsight, once I lined the numbers up next to each other.

The Numbers

It started quietly with a fee comparison, ETFs costing 0.03 percent against unit trusts front-loading 5 percent in upfront charges. That felt like a standalone piece at the time. Then the T-bill auctions started climbing, 1.60 percent, then 1.70 percent, then 1.92 percent, three prints in two weeks, each one a little sharper than the last. By midweek the 10-year US Treasury was retesting a 2007 high, and the Fed, ECB, and BOJ were all hiking while the UK, India, and China held. Singapore's own core inflation ticked up for a third straight month to 2.2 percent, its highest reading in two years. None of these happened in isolation, they were the same pressure showing up in five different places.

What struck me by the end of the week was how differently individual names handled that same pressure. City Developments couldn't absorb it at all, 0.99 times interest coverage means its operating profit doesn't even cover the interest bill, landing it in Zone 5. Singtel's headline yield looked fine at 4.3 percent until you stripped out a one-off dividend and found 3.08 percent underneath, a real number wearing a flattering one. The REIT sector's 0.77 times book value discount turned out to be a structural problem, not a temporary one, external managers earning fees on size have no reason to fix a discount that a merger would erase. Meanwhile DBS's lot-size cut and the retirement math piece, S$711,000 versus the naive S$1.8 million figure, were reminders that not everything this week was about stress, some of it was about access and about correcting a distorted comparison.

(2000 character limit so I will post the rest in the comments lol)

图片 1,共 1 张Long image
T
TheInvestingIguanaSep 26 at 04:01 AM

Iggy's Journal: From October, DBS Gets Ten Times Cheaper to Buy Into. Here's What Lower Lot Sizes Actually Do to Trading Volume.

26 September 2026, Morning

Podcast

SGX just cut the minimum lot size from 100 shares to 10 for 11 blue chips, DBS among them. The affordability headline is real, but I don't think it's actually the interesting part of this story.

The Numbers

Those 11 names already drive roughly 35 percent of all trading on the exchange. That matters because the liquidity premium from a smaller lot size is mostly earned at the illiquid end of the market, where a high minimum ticket genuinely keeps people out. Making an already-liquid stock slightly easier to enter doesn't create the same effect. If DBS sits near S$75, your minimum ticket drops from about S$7,500 to about S$750 once the change takes effect on 5 October, letting you scale into a position in smaller steps instead of committing everything at once. Existing odd-lot holders benefit too, a 40-share holding becomes four clean 10-share lots under the new structure, though 41 shares still leaves one lone share sitting outside any lot.

My Personal Take

This is a market-structure change, not a valuation signal, and I want to be direct about that because 5 October is exactly the kind of date that gets treated as a catalyst when it isn't one. Nothing about DBS's business, its balance sheet, or its dividend changes because the lot size did. What actually changes is who can enter and how gradually, and that's a genuinely useful shift for anyone building a position slowly rather than dropping a lump sum in one go. But don't confuse easier access with a reason to expect a price move, those are two completely different things, and mixing them up is how people end up reading a plumbing fix as a market signal. 

📺 YouTube: https://youtu.be/rLIPHq-E6aU

📩 Substack: https://investingiguana.com/p/dbs-gets-ten-times-cheaper-from-october

- YouTube

- YouTube

YouTube 上盡享你喜愛的影片和音樂、上載原創內容,並與親友和世界各地的人分享。

youtu.be
图片 1,共 1 张Long image
T
TheInvestingIguanaSep 26 at 03:30 AM

Iggy's Journal: The STI Just Closed Its Best Week in a While. The Tug of War Underneath It Isn't Over.

26 September 2026, Morning

Markets are closed for the weekend, so no new session to open into today. Worth pausing on how the week actually closed, because Friday's rally papered over a tension that hasn't gone anywhere.

The Numbers

Wall Street snapped a three-day decline on Friday. The Dow rose 0.93 percent to 51,828.62, the S&P 500 gained 0.51 percent to 7,743.41, and the Nasdaq added 0.48 percent to 27,068.72, driven by Treasury yields pulling back from their 2007-era peak and Brent crude easing 2.14 percent to $104.32 on signs of a possible compromise over Middle East maritime transit. The STI followed with its own 0.5 percent gain to close the week at 5,711.12, up 1.0 percent over the five sessions, led by the banking trio: OCBC up 1.3 percent to $32.01, DBS up 0.7 percent to $78.00, and UOB up 0.2 percent to $42.57. Separately, MAS and the Institute of Banking and Finance announced that 23 financial institutions have pledged to train more than 80,000 Singapore-based employees in AI skills by 2028. And HSBC's own read on the region this week called rising yields and oil prices a genuine "tug of war" against the ongoing AI investment boom, not a settled fight either way.

My Personal Take

A good week doesn't mean the underlying tension resolved, it means the two forces pulling against each other happened to net out in equities' favour for five days. Yields easing and oil pulling back both helped, but neither move undoes the structural story I've been tracking all week: a 10-year Treasury retesting a 2007 high and a T-bill auction that jumped 22 basis points in two weeks are not artifacts of one bad Wednesday, they're signals of where the floor under short-term cash may be settling. HSBC calling it a tug of war is the right frame, not a resolved story 

Not financial advice. Iggy's Forensic Compliance Standards apply.

图片 1,共 1 张Long image
T
TheInvestingIguanaSep 25 at 02:57 PM

$Sasseur Reit(CRPU.SG)Added on Confirmation, Not on a Dip


Context: I don't add to a position because the story sounds good, I go back through the numbers first. Gearing's still comfortably inside where I'm willing to hold leverage, coverage clears with real room to spare, and the cost of debt has been trending down, not up, on refinancing. That's the kind of confirmation I actually wait for before sizing up.


My take: this wasn't buy the dip, it was the gates are still clean so I'm comfortable adding. Averaging in on confirmation rather than hope is the discipline I'm trying to hold myself to, regardless of where the price sits on a given day.


Not financial advice, just my own process. 


Cheers, Iggy 🦖

trade showcase
T
TheInvestingIguanaSep 25 at 11:56 AM

Iggy's Journal: UOB Kay Hian Puts an $11.85 Target on City Developments. Its Operating Profit Doesn't Cover the Interest Bill.

25 September 2026, Evening

Video Release

I keep coming back to one number on this one: 0.99 times interest coverage. CDL's RNAV story may well be real, but paper asset value doesn't pay an interest bill, and that's the gap between the target price and what the balance sheet is actually telling me right now.

The Numbers

UOB Kay Hian's $11.85 target depends on actual, fairly priced disposals happening, not simply on a strategic review headline being announced. The numbers underneath tell a harder story. Gearing sits at 69 percent, nearly double the 35 percent ceiling I use as a hard gate. Net debt to EBITDA is at 15.7 times, well past the 10 times mark I treat as a red flag. Interest coverage is 0.99 times, meaning operating profit doesn't fully cover the interest bill, and that's been compounded by two consecutive years of negative operating cash flow. The 3.83 percent yield clears my 3.2 percent forensic floor, but it misses the 4.7 percent hurdle by a meaningful margin.

My Personal Take

For a CPF, SRS, or dividend portfolio, this is exactly the kind of setup where a genuinely compelling growth story and a genuinely concerning balance sheet can both be true at the same time, and the second one doesn't go away just because the first one gets more airtime. The number I actually want to see next isn't another target price, it's the first signed disposal price measured against book value. That's the figure that tells you whether the RNAV story is real money or still just a plan. Full breakdown of how I'm weighing the target against the balance sheet is in today's video.

📺 Free YouTube: https://youtu.be/ELPnYvPW4no

⭐ Members Edition YouTube: https://youtu.be/IrpM6d-lRfA

📩 Substack: https://investingiguana.com/p/uob-kay-hian-puts-an-1185-target

Not financial advice. Iggy's Forensic Compliance Standards apply.

- YouTube

- YouTube

YouTube 上盡享你喜愛的影片和音樂、上載原創內容,並與親友和世界各地的人分享。

youtu.be
UOB KAY HIAN'S $11.85 TARGET VS. INTEREST BILL 25 SEPTEMBER 2026 $11.85 个 INTERE
T
TheInvestingIguanaSep 25 at 05:58 AM
Featured

Iggy's Journal: T-Bills Jump to 1.92%. What It Means for Your CPF and SRS Cash.

25 September 2026, Afternoon

Podcast

The surprising part of this auction wasn't simply that yields rose again. It's that they rose despite genuinely strong demand, which is usually the thing that's supposed to hold a cut-off down, not push it up.

The Numbers

The auction drew S$15.8 billion in applications, real demand, plenty of investors competing for allocation, and the cut-off still jumped 22 basis points in two weeks to 1.92 percent. That combination tells me the auction is clearing at a genuinely higher price for short-term cash right now, not just drifting because supply happened to be thin. For CPF Ordinary Account money, the comparison is straightforward: 1.92 percent still sits about 60 basis points below the 2.5 percent OA rate, so this auction doesn't change that calculus. For SRS funds or cash sitting outside CPF, the real question is different, whether a modestly higher rate than a fixed deposit is worth giving up the flexibility a Savings Bond gives you, since a T-bill locks your money away for the full six months either way.

My Personal Take

Strong demand and a rising yield happening at the same time is the detail I keep coming back to. It means the market isn't just accepting a higher rate because it has no choice, it's actively bidding for exposure at that higher rate, which says something about where people expect this trend to go next. For CPF OA money, this one's easy, the OA rate still wins and nothing here changes that. For your SRS or spare cash, the honest answer is it depends on whether you value the extra yield over the ability to get your money back before six months is up, and that's a personal call, not a forensic verdict. Full breakdown of how I'm reading this auction against the last two is in today's episode.

📺 YouTube: https://youtu.be/f67O32UvX0k

📩 Substack: https://investingiguana.com/p/the-t-bill-auction-just-had-its-biggest

Not financial advice.

- YouTube

- YouTube

YouTube 上盡享你喜愛的影片和音樂、上載原創內容,並與親友和世界各地的人分享。

youtu.be
图片 1,共 1 张
T
TheInvestingIguanaSep 25 at 12:23 AM
Featured

Iggy's Journal: The 10-Year Treasury Just Pushed Past a 2007 High. Singapore's Banks Felt It the Next Morning.

25 September 2026, Morning

Wall Street's overnight session looked calm on the surface, three flat-to-slightly-down index moves. The bond market underneath it wasn't calm at all.

The Numbers

The Dow fell 0.31 percent to 51,349.98, the S&P 500 was essentially flat, down 0.02 percent to 7,704.13, and the Nasdaq actually closed up 0.01 percent at 26,939.37. None of that tells the real story. The 10-year US Treasury yield pushed past 5.11 percent and touched 5.20, retesting a level not seen since 2007, while Brent crude extended its rise for a second straight session, up 3.56 percent to $106.75, on the same Strait of Hormuz tension that pushed it through $103 the day before. USD/SGD sits at 1.2796. Back home, the STI closed Thursday's session down 0.5 percent at 5,683.37, on turnover of S$1.8 billion, dragged specifically by the banking trio: DBS down 0.3 percent to $77.48, OCBC down 0.2 percent to $31.59, and UOB down 0.8 percent to $42.50. Separately, StarHub and Keppel confirmed they've entered preliminary talks over a potential consolidation involving M1, still talks, no terms disclosed yet.

My Personal Take

A calm-looking index number can hide a genuinely unsettled bond market, and that's exactly what happened overnight. When the 10-year yield retests a level from 2007, every income asset back home gets repriced against that number whether the headline mentions it or not, and Singapore's own banks led the STI lower the very next session. That's not proof of causation on its own, but it's the kind of alignment worth watching rather than dismissing as coincidence. Oil rising two sessions running on the same geopolitical story is the other thread I'm not done with yet, one day of a move is noise, two is starting to look like a pattern.  


Not financial advice. Iggy's Forensic Compliance Standards apply.

图片 1,共 1 张
T
TheInvestingIguanaSep 24 at 12:09 PM

Iggy's Journal: T-Bill Season Is Back. The 6-Month Cut-Off Just Jumped to 1.92%.

24 September 2026, Evening

I'd mostly stopped actively covering T-bills the last few months. They'd settled into a quiet, boring range, and boring doesn't need a weekly update. That changed today, and not gradually.

The Numbers

Today's 6 month Singapore T-bill auction, BS26119F, closed at a cut-off yield of 1.92 percent per annum, issue date 29 September. That's up from 1.70 percent at the BS26118E auction two weeks earlier, on 15 September, which itself was up from 1.60 percent at the BS26117A auction on 27 August. The first move was 10 basis points. This one was 22, more than double the prior jump.

My Personal Take

An accelerating move is a different story than a steady one, and this is now the second kind. I flagged back in July that MAS's tightening would eventually show up as a real, checkable number rather than a macro talking point, and this is that number arriving faster than the earlier prints suggested it might. I put in a sizable non-competitive bid on this auction myself and got the full allocation, which tells me demand hadn't caught up to the yield jump yet, not by the time this one closed anyway. I'm restarting regular T-bill coverage here because a range that moves 22 basis points in two weeks isn't something you check on quarterly anymore. If you've got a renewal coming up, this is the actual, current alternative your cash is competing against, not a forecast of one, and it's worth watching whether the next auction confirms the acceleration or the yield jump finally pulls in enough demand to get rationed

图片 1,共 1 张
T
TheInvestingIguanaSep 24 at 09:09 AM
Featured

Iggy's Journal: The Real Price of a Debt-Free $4,500 a Month in Retirement Is $711,000, Not $1.8 Million.

25 September 2026, Evening

Video Release

The biggest distortion I found in this comparison wasn't the retirement target itself. It was treating CPF as though it contributes nothing, then asking a portfolio to fund the entire S$4,500 a month alone.

The Numbers

Once CPF LIFE is actually counted, the FRS to ERS tranche produces an estimated 9.04 percent annual payout ratio, a genuinely strong number, but it comes with a real cost: that money stops being liquid capital the moment it goes in. At the Enhanced Retirement Sum, the remaining portfolio gap falls to S$1,060 a month, which requires S$270,638 at my 4.7 percent yield hurdle. Add that to the ERS itself and you land at roughly S$711,000, a long way from the S$1.8 million figure you get if you strip CPF out of the picture entirely and ask a portfolio to cover the full S$4,500 on its own.

My Personal Take

This is the forensic tension underneath the headline number. CPF gives you stronger guaranteed lifetime income, a dividend portfolio gives you access to capital for medical bills, family needs, and the unexpected. Neither one is the correct answer on its own, and most retirement content I see picks a side and pretends the other doesn't exist. The honest version of this conversation isn't CPF versus portfolio, it's how much of each you actually need. Full breakdown of how I built the S$711,000 figure, tranche by tranche, is in today's video.

📺 Free YouTube: https://youtu.be/EiM0Vc66nD4

⭐ Members Edition YouTube: https://youtu.be/DhuWkhbwHRM

📩 Substack: https://investingiguana.com/p/the-real-price-of-a-debt-free-4500

Get everything, full-length videos and full Substack analysis on both platforms, full Red Zone watchlist, forensic cheatsheets, with the YouTube/Substack Combo, S$12/month.

Not financial advice. Iggy's Forensic Compliance Standards apply.

- YouTube

- YouTube

YouTube 上盡享你喜愛的影片和音樂、上載原創內容,並與親友和世界各地的人分享。

youtu.be
Iggy's Journal: The Real Price of a Debt-Free $4,500 a Month in Retirement Is $7
T
TheInvestingIguanaSep 24 at 07:45 AM
Featured

Iggy's Journal: Three Out of Four Singapore REITs Trade Below Book Value. Here's Why Almost Nobody Is Merging Them.

24 September 2026, Afternoon

Podcast

The average S-REIT trades at 0.77 times book value. If markets worked the way textbooks say they should, that gap alone would trigger a wave of mergers. It hasn't. The count sits stuck at 39.

The Numbers

External managers earn fees on the size of the REIT they run, so a merger that fixes the discount also erases someone's income. That's why consolidation only happens within the same sponsor's stable, fees never actually leave the building, they just move from one entity to another under the same roof. The pressure on the sector isn't easing either. DBS just cut target prices by 9.6 percent after the Fed hiked to 3.75 to 4 percent, adding another headwind to a sector already trading at a structural discount nobody managing it is incentivised to close.

My Personal Take

If you're holding a small, externally managed REIT for the yield, this is the actual mechanism keeping your distributions flatter than they need to be, and it has nothing to do with whether the underlying properties are any good. Nobody at the manager gets a bonus for shrinking their own fee base, so the discount just sits there, year after year, quietly costing unitholders while the manager's income stays exactly the same size. That's not a scandal, it's just an incentive structure working precisely as designed, for the people it was designed for. Full breakdown of which REITs actually have a sponsor path to consolidation, and which ones are structurally stuck, is in today's episode.

📺 YouTube: https://youtu.be/fhAFb_gtiHU

📩 Substack: https://investingiguana.com/p/three-out-of-four-singapore-reits


Not financial advice. Iggy's Forensic Compliance Standards apply.

- YouTube

- YouTube

YouTube 上盡享你喜愛的影片和音樂、上載原創內容,並與親友和世界各地的人分享。

youtu.be
S-REIT Mergers: The Structural Incentive Gap |24 September 2026 THE 0.77x BOOK V
T
TheInvestingIguanaSep 24 at 12:40 AM
Featured

Iggy's Journal: Wall Street Fell on a Yield Not Seen Since 2007. Singapore's T-Bill Just Printed at 1.70%.

24 September 2026, Morning

I'm writing this one from an airport, one more flight before I'm actually home, so bear with me if it reads a touch leaner than usual. Wall Street had a rough overnight session, and the number underneath the headline drop is worth more of your attention than the drop itself.


The Numbers

The Dow fell 0.68 percent to 51,511.59, the S&P 500 dropped 0.75 percent to 7,706.03, and the Nasdaq led the slide, down 1.13 percent to 26,936.04. The driver was the bond market: the 10 year US Treasury yield pushed toward its highest level since 2007 after a stronger than expected September business survey reinforced bets on further Fed hikes, and Brent crude jumped over 4 percent past $103 a barrel on renewed Strait of Hormuz worries. Back home, the STI's last official close was 5,710.00 on 23 September, down 0.24 percent, as Singapore's own core inflation accelerated to 2.2 percent for a third straight month, the highest reading since September 2024. USD/SGD sits at 1.2797. 

MAS's scheduled six month T-bill auction this morning cut off around 1.70 percent, the first genuinely clean rate figure I've had in hand all week, worth comparing against your own last renewal. 


My Personal Take

Rising global yields and a domestic inflation print landing on the same news cycle is really one story wearing two costumes. Every income asset on this board now has to justify itself against a higher hurdle, not because anything changed at the company level, but because the alternative your money could sit in instead just got more expensive. I'm also keeping half an eye on the Trump-Xi state visit kicking off in Washington today. A two month trade truce extension is the kind of headline that moves sentiment fast without changing a single Singapore balance sheet. What would change my view here is a number or a term sheet, not a headline.

Not financial advice.

WALL STREET YIELDS HIT 2007 LEVELS 24 SEPTEMBER 2026 WALL STREET & YIELDS SINGAP
T
TheInvestingIguanaSep 23 at 10:50 AM
Featured

Iggy's Journal: Inflation Ticks Up for a Third Straight Month. The STI Barely Noticed.

23 September 2026, Evening

(No infographic for this post; I'm on a plane right now) 


The STI closed at 5,709.9, down 13.85 points, a quiet 0.24 percent day. Underneath that quiet, Singapore just posted its highest core inflation reading in two years, and the room is genuinely split on what MAS does about it in October.


The Numbers

Core inflation rose to 2.2 percent in August from 2 percent in July, the third straight monthly increase, while headline inflation, which includes accommodation and private transport, ticked up to 2.3 percent. Airline ticket costs jumped 12.9 percent, the sharpest rise in nearly four years, and services inflation climbed to 2 percent from 1.7 percent the month before. MAS already tightened the SGD NEER slope twice this year, in April and again in July, and economists are now split on whether October brings another small tightening or a hold. DBS's Chua Han Teng summed up the tension in four words, inflation "firmed but not accelerating."  

My Personal Take

Barclays called this data "more benign" than what MAS was pricing in back in July, and I think that's the real story hiding under a boring index day. The central bank tightened twice this year on the expectation that growth would eventually show up as inflation. Now the inflation is showing up, just slower and milder than the move that was meant to get ahead of it. That's not a policy mistake, it's a central bank managing a moving target in real time, but it does mean the case for October restraint gets a little stronger with every print like this one. If your T-bill or fixed deposit is coming up for renewal around then, this is exactly the kind of data that decides whether your next rate looks better or worse than the last one.


Cheers, Iggy

T
TheInvestingIguanaSep 23 at 05:06 AM

Iggy's Journal: The Fed, the ECB, and the Bank of Japan Are All Raising Rates. The UK, India, and China Are Not. Here's What That Means for Your CPF and SRS.

23 September 2026, Morning

Podcast

Everyone assumed hiking banks are the hawks and holding banks are the doves. That's the wrong frame entirely, and it took me a minute to see it too.

The Numbers

The BOJ hiked to 1.25% even though Japan carries one of the most indebted governments in the world, while China held for a sixteenth straight month despite industrial production actually strengthening. The real split isn't hawkish versus dovish. It's whose demand needs restraining versus whose credit demand is too weak to justify tightening at all. MAS doesn't set a policy rate the way the Fed or ECB does, but SORA mortgages, T-bill yields, and fixed deposit renewals all move with this global tug of war anyway, and UK 30-year gilt yields sitting near 5.7 to 5.9 percent this week show just how far that pressure is reaching.

My Personal Take

Your CPF Special Account keeps its government-guaranteed four percent floor no matter what any of these central banks decide this month, that part isn't moving. What's moving is what your surplus cash outside CPF competes against. If your next T-bill or fixed deposit comes up for renewal soon, the question I'd actually be asking isn't whether the new rate looks better or worse than last time. It's whether the reason behind that repricing is something likely to persist for a while, or something likely to pass in a quarter or two. That distinction is the whole episode.

📺 YouTube: https://youtu.be/nCfThkQ3MPU

📩 Substack: https://investingiguana.com/p/the-fed-the-ecb-and-the-bank-of-japan

Not financial advice. Iggy's Forensic Compliance Standards apply.

- YouTube

- YouTube

YouTube 上盡享你喜愛的影片和音樂、上載原創內容,並與親友和世界各地的人分享。

youtu.be
Global Rates Split: Hiking vs. Holding l Banks 23 September 2026,Morning HIKING
T
TheInvestingIguanaSep 22 at 08:07 AM

Iggy's Journal: EP1828 - Singtel's Yield Looks Like 4.3%. Strip Out the One-Off Dividend and It's 3.1%.

22 September 2026, Evening

Video Release

UOB Kay Hian's $5.50 target and my 4.3% yield reading aren't actually disagreeing with each other. One is pricing a Nxera transaction that hasn't happened yet. The other is measuring the cash Singtel is paying out right now.

The Numbers

A stock can clear the first test and fail the second at the same time, and that's exactly what I found when I ran the current numbers. Strip out the one-off Value Realisation Dividend and Singtel's core yield drops to 3.08%, below what CPF Special Account already pays with zero equity risk attached. The balance sheet itself isn't the issue. Gearing sits at 23.3% and interest coverage at 19.0x, both clearing with wide margin.

My Personal Take

This isn't a quality problem, it's an income problem, and that distinction matters if you're holding Singtel for the yield rather than the balance sheet. Iggy's Forensic Zone on this one is Zone 4, Caution Plus, not because the company is shaky, but because once you strip out a one-time payout, the yield you're actually being paid is doing less for you than a CPF contribution with no equity risk at all. Full breakdown of how I separated the one-off from the recurring number is in today's video.

📺 Free YouTube: https://youtu.be/mnlbZ9Ski8w

⭐ Members Edition YouTube: https://youtu.be/GC8YJtuRlLw

📩 Substack: https://investingiguana.com/p/singtels-yield-looks-like-43-strip

Get everything, full-length videos and full Substack analysis on both platforms, full Red Zone watchlist, forensic cheatsheets, with the YouTube/Substack Combo, S$12/month.

Not financial advice. Iggy's Forensic Compliance Standards apply.

- YouTube

- YouTube

YouTube 上盡享你喜愛的影片和音樂、上載原創內容,並與親友和世界各地的人分享。

youtu.be
图片 1,共 1 张