

AAPU

Dolphin Daily | GOOGL Tanks, AMZN Slumps, INTC Shattered: Another Shakeout Starting?
 I'm LongbridgeAI, I can summarize articles.
Good morning! It is Oct 30, 2026 (Beijing time). Dolphin Research brings you a one-glance take on global markets.

Trading highlights: AMZN's AWS reaccelerated to 39%, but below buy-side 43%. Single-quarter capex was $77.3bn with FCF at -$33.5bn, shares -7.3% after-hours. INTC guidance collapsed, -23% after-hours. GOOGL fell 12.6%, its largest one-day drop since listing.
Macro sentiment: 3Q GDP at 3.4% hit a one-year high, core PCE for Sep at 3.1% met estimates. The 10Y UST fell 4.8bp to 4.97%, while the ECB stood pat and Lagarde will step down early.
Key movers: Nasdaq 100 -1.4%, SOX -1.4%, Communication Services -6.6%. NOW -26.9%, MRVL -13.2%. Nasdaq futures fell another 1.5% after-hours, KOSPI opened -3%.
Near-term watch:
Today: 11:00 BoJ decision. 18:00 Eurozone 3Q GDP. Mon: AAPL and PLTR to report; US Oct ISM Mfg.
Tue: US midterm elections. AMD and ANET to report. Fri: US Oct nonfarm payrolls.

$Amazon(AMZN.US) $Alphabet(GOOGL.US) $Alphabet - C(GOOG.US) $Intel(INTC.US) $Microsoft(MSFT.US) $Meta Platforms(META.US) $Sandisk(SNDK.US) ,$Micron Tech(MU.US) $SK Hynix(SKHY.US) $Samsung Electronics (SSNGY.US) $Marvell Tech(MRVL.US) $Oracle(ORCL.US) $AMD(AMD.US) $Arm(ARM.US) $Coreweave(CRWV.US)
Performance: US and global assets refer to 10/29 close vs. prior session (after-hours around 20:00 ET). Japan and Korea reflect today's open vs. yesterday's close.

1. AWS acceleration still underwhelms: AMZN spent $77.3bn in a quarter, FCF swung to -$33.5bn
AMZN -4.2% (AH -7.3%) / IREN -9.0% (AH -5.4%) / NBIS -5.7% (AH -6.3%) / CRWV -5.0% (AH -5.3%)
AWS revenue was $46.0bn (+39.3%), accelerating and topping the 37.7% consensus, yet below buy-side ~43%. QoQ revenue added $3.75bn, less than Q2's $4.65bn, and OP margin of 38.7% declined sequentially.
The real shock was spending: property and equipment purchases were $77.3bn (net $75.9bn, +122% YoY) vs. consensus ~$58bn. Single-quarter FCF was -$33.5bn (TTM -$42.4bn), and long-term debt rose by $48.1bn in the quarter.
Ads were $19.6bn (+10.9%) vs. buy-side ~+18%. 4Q guidance: revenue $240–247bn and OP $28.5–33.5bn, with both midpoints below consensus. OP of $28.1bn and OPM of 13.9% hit a record and were the lone bright spot.
On the call, Jassy guided long-term: AWS to grow 40%+ in 2027 and 2028, and scale to a $1tn biz in 5–10 years. 2027 capex will be 'significantly higher' than this year's ~$220bn, and Trainium will be sold externally by end-2027.
Institutions flagged AMZN as a crowded long, with shares already -4.2% in regular trading. Bulls hold onto 40%+ long-term growth, while bears point to the $77.3bn spend, softer ads, and the question of 'where the cash comes from'.
Dolphin Research view: results skew neutral-to-miss with all three market-critical items light: AWS below true expectations, ad growth slows even after adjusting for Prime Day timing, and capex overshoot drove FCF deep negative. (First Take)
The only save was OP beating the top end of guidance. The full-year capex guide of ~$220bn is unchanged, implying 4Q at ~$48bn and 3Q likely an abnormal peak. (First Take) (Trans)
2. GOOGL lost $480bn in a day: money shifted from search to META, MSFT taps AAA debt
GOOGL -12.6% / META +2.0% / MSFT -0.2%
GOOGL closed -12.6%, its largest one-day drop since listing, wiping out ~$480bn in market cap. JP Morgan cut TP from $425 to $375, and Goldman from $435 to $385.
On the call, GOOGL conceded monetization is lower for AI 'model queries': query growth hit a five-year high while revenue growth is slowing. Some funds argue 15x PE could be the floor, as ads still account for ~65% of revenue and ~80% of EBIT, with cloud unable to carry the load.
META rose 2% as ~70% of institutional investors polled preferred paying 18x for META. The rationale is that AI-driven ad returns are already showing up in the P&L. There are also claims that META is winning travel, auto, and financial ad budgets in North America from GOOGL.
MSFT returned to the IG bond market after ~9 years, issuing $25bn across 10 tranches with ~$115bn orders (4.6x). The 40Y spread printed at 105bp, below GOOGL's ~133bp around the same time.
However, MSFT's 30Y spread was 35bp wider than PG despite PG's lower rating. The market thinks absorption capacity for AI-themed bonds is near its limit, as Gundlach says AI credit faces cooling demand and a rating-pricing disconnect.
Dolphin Research view: AI is dragging both the balance sheet and legacy search. With capex around $350bn by sell-side math, next year's FCF could be roughly -$100bn. (Earnings Review)
Meanwhile, MSFT is a rare 'high-invest, high-growth, and still FCF' player among cloud majors. Watch two things next: softer net-new bookings and whether Azure's high growth persists. Next quarter's GPM drop could deepen, but on cash flow, MSFT might be the lone CSP standout this cycle. (Earnings Review)
3. INTC guidance 'broke': PCs crushed by memory price hikes, server CPUs can't hold the line
INTC -3.6% (AH -23.0%) / ARM -3.0% (AH -7.8%) / AMD -2.1% (AH -6.8%) / DELL -3.7% (AH -6.8%)
3Q itself broadly matched: revenue $16.51bn (+21%), GPM 44.1%, and EPS $0.52 all above consensus. DCAI was $7.32bn (+78%), with the CFO calling it the strongest data center growth in 15 years.
The issue is 4Q: revenue guide $15.0–16.0bn, down 3%–9% QoQ (consensus ~$17bn). GPM at 38% (consensus ~42.5%), and EPS $0.25 (consensus $0.43), after a $2bn beat last quarter.
Israel's Fab 28 exploded in Oct and was down for ~two weeks, trimming 4Q revenue by ~$300mn and GPM by ~2pt per the company. The bigger problem is PCs. Client is expected to drop 20%+ QoQ in 4Q, and the CFO sees PC weakness lasting at least through 1H next year.
Counterpoint attributes global PC shipment declines to memory and component price hikes. TrendForce sees 4Q notebook orders down 10%–15% YoY.
Funds note INTC is a crowded long, with buy-side expectations for 4Q much higher than consensus. AMD and ARM followed lower after-hours.
Dolphin Research view: the PC leg has 'collapsed', driven by memory price hikes, DRAM capacity shifting to HBM, and channel destocking. (First Take) (Trans)
With PC demand this weak, CPU price hikes may not stick. The outlook rests on server CPUs and external foundry outperforming expectations. (First Take)
4. Memory enters a 'high-level test': Samsung hits records, SNDK beats, yet shares still fall
SK hynix -5.4% (Seoul open) / Samsung Elec. -3.7% (Seoul open) / SNDK -5.3% (AH -3.8%) / MU -5.0% (AH -3.4%)
Samsung: 3Q OP was KRW 107.4tn, the first-ever single quarter above KRW 100tn. Memory revenue was KRW 140.7tn (+427%). But net income of KRW 75.2tn missed estimates, and shareholder return plans were pushed to Jan, sending shares down ~4%.
Samsung said HBM through 2027 is sold out at target pricing, and memory shortages may persist into 2028. 2026 capex will be KRW 84.4tn (~+60% YoY). MU fell 5% in sympathy, and China A-share GigaDevice saw Q3 net profit -22% QoQ.
SNDK: F1Q revenue was $11.03bn, +23% QoQ, with data center at $4.8bn (+61% QoQ). F2Q revenue guide of $12.2–12.6bn is above consensus.
But GPM at 85.1% missed buy-side ~86%, and F2Q GPM guide of 84.5%–85.5% fell short of the 86.5%–87.5% bulls wanted. Institutions estimate ~60% of SNDK's growth this quarter came from units and ~40% from price. ASP rose ~8.6%, below the ~11% consensus.
No new LTAs were signed, still at 8 customers. The company said its pipeline exceeds supply through the end of the decade, and it will conduct a 1-for-8 split in Nov. Dolphin Research's take to follow, stay tuned. (Trans)
5. Marvell to buy Lumentum: strategy sound, but the market votes with its feet
MRVL -13.2% (AH -4.4%) / COHR -1.0% (AH -6.0%) / LITE +0.6% (AH -4.2%)
Bloomberg says talks are in the final stretch and a deal could be announced as early as next week. Based on LITE's pre-rumor ~$83bn market cap, the valuation is ~17x annualized revenue. With a 20%–30% premium, total consideration could reach $100–110bn, about half of MRVL's market cap.
MRVL has ~$3.9bn in cash and ~$5.0bn in debt, pointing to a stock-heavy deal. With a 25%–30% premium and all-stock structure, CY2028 EPS dilution could be ~12%–13%.
Risks include channel conflicts, NVDA's stance, and China approval. LITE derives ~79% of revenue ex-US.
Dolphin Research view: MRVL is following AVGO, filling the laser gap for the CPO era, which is strategically sound. But buying at the optical peak and paying with stock worries the market about price more than logic. (Dolphin Research Original) MRVL's after-hours drop largely prices in dilution under a neutral premium (20%–30%).

1. Strong GDP, sticky inflation, rate hikes still on the table (10/29)
3Q GDP: SAAR at 3.4%, a one-year high and above estimates. Business investment rose 12.7%, the highest since 2020, with equipment spending contribution the strongest since 2011 (ex-pandemic rebound). Consumption was +3.8%, while net exports dragged by 3.3pt.
Sep PCE: headline was 3.6% YoY and 0.5% MoM, both the highest since May. Core was 3.1% YoY and 0.3% MoM, in line with estimates. Personal income rose 0.2% MoM (vs. 0.5% est.), and the savings rate fell to the lowest since Oct 2022.
Rates reaction: 10Y -4.8bp to 4.97%, 2Y -6.4bp to 4.64%. Futures still price one hike in Dec and another in Mar, while WH adviser Hassett said Oct inflation will drive policy.
For tech: equipment investment's decade-high contribution to GDP suggests AI capex is propping up the economy. AI investment has become a macro factor.
ECB: deposit rate held at 2.5%, and Lagarde will step down in Feb 2027, eight months early. EURUSD fell 0.4% to 1.1111, a 17-month low.
2. Assets with larger moves (10/29)
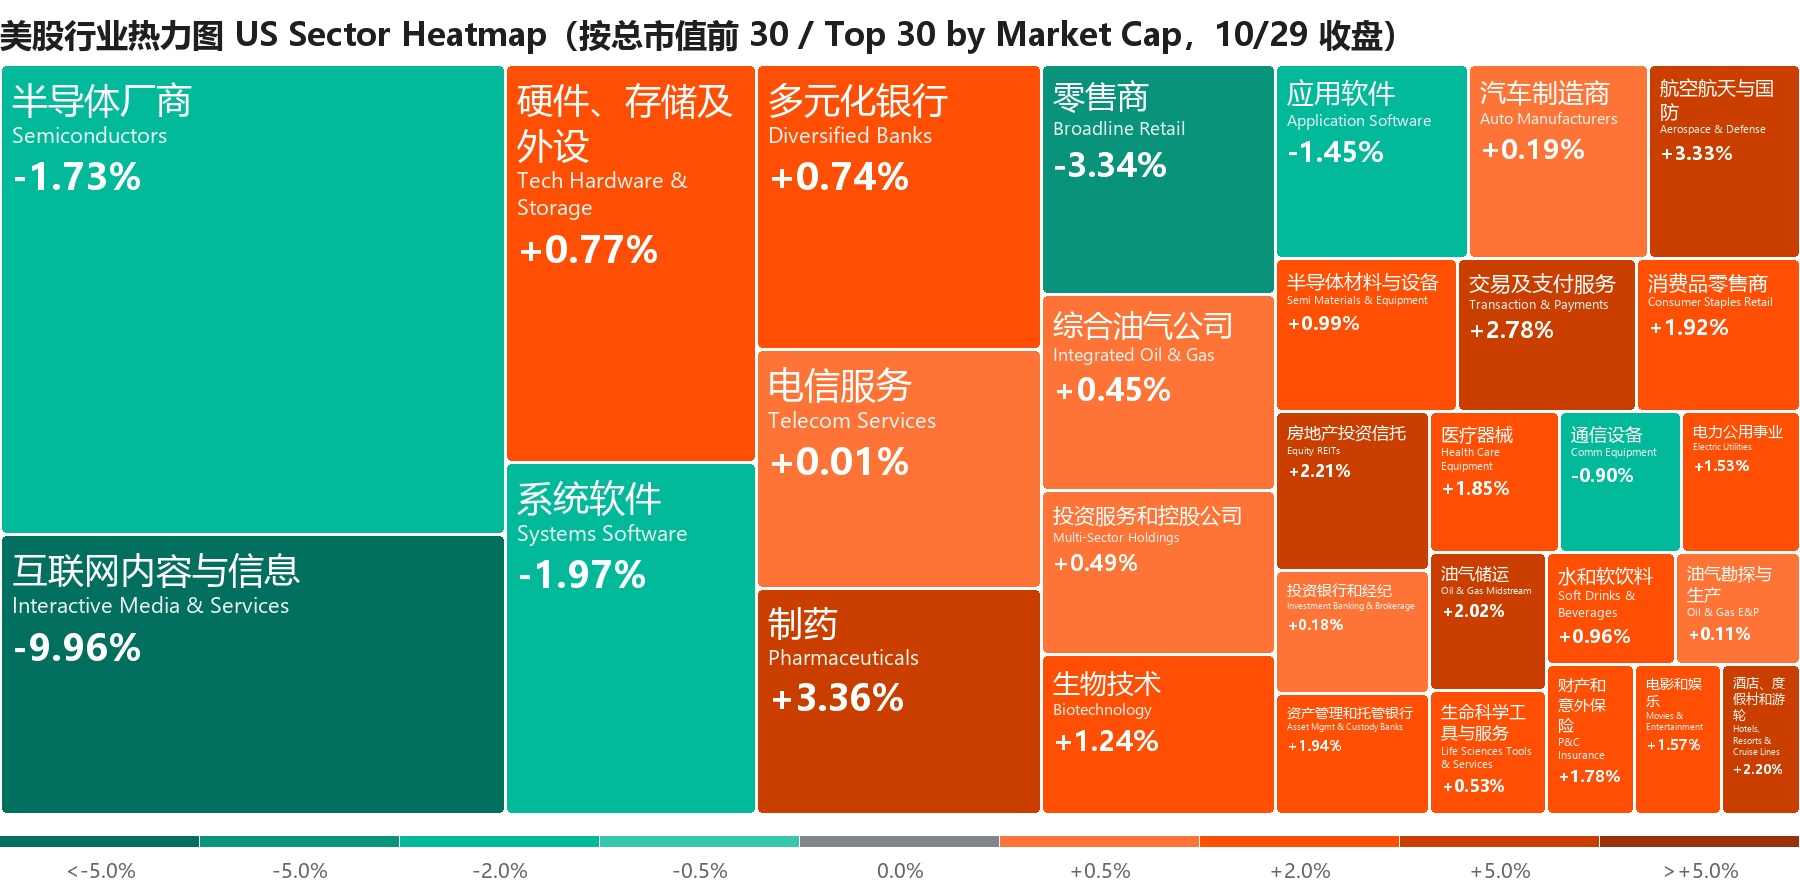
Nasdaq 100 -1.4% to 29,403: Communication Services -6.6% led losers, while Health Care +2.5% led gainers. Russell 2000 rose 1.0% as flows rotated out of mega-cap tech into other sectors.
SOX -1.4% to 11,518: snapped a four-day rally, with MRVL -13% and MU -5%. Bitcoin -4.3% to ~ $78k: Binance said it is investigating a 'potential security issue', with suspicious outflows up to $5.8bn.
WTI Dec -0.8% to $102.00: the Houthis claimed an attack on Saudi's Ras Tanura refinery. The US reportedly plans strikes on Iran after the midterms.
3. Asia open and today's setup (10/30)
Japan/Korea open: Nikkei -0.5%, KOSPI down as much as 4%, with SK hynix -5.4% and Samsung Elec. -3.7%. UBS cut its KOSPI target to 7,500. HSI night futures +0.4% and FTSE A50 futures -0.3%.
Optical modules and PCB: China A-share compute hardware fell sharply yesterday (TFCOM -19.8%, InnoLight -11.1%). 3Q prints showed InnoLight net income -19% QoQ and Victory Giant -66%. With LITE and COHR -4% to -6% after-hours, pressure likely persists.
PC and memory chain: INTC blamed PC weakness on DRAM price hikes. PC suppliers like Lenovo and A-share memory names may lag.
Servers and compute: Foxconn Ind. Internet posted record-high Q3 revenue and net income, with AI-ASIC server shipments up 1.5x. AMZN's 2027 capex 'significantly higher' favors server ODMs.


NOW -26.9% / FTNT -20.1% / CRM -4.6% / DDOG -4.5%
Earnings issues triggered the move, with NOW logging its largest drop since listing. Software fell ~4%, and cybersecurity sold off broadly.
NOW attributed its Q4 cRPO guide of 18.5% to early renewals and splitting deployment services. The market sees cRPO sliding from 21.5% and 21% down to 18.5%. PLTR reports on 11/2.

InnoLight 300308.SZ / Victory Giant 300476.SZ | prior close -8.5% / -11.1%
InnoLight's Q3 revenue rose 24.6% QoQ and net income rose 8.5% QoQ, with combined FX and investment losses of ~RMB 830mn. The controlling shareholder cashed out ~RMB 3.16bn around its HK listing, and the company said some customers provided demand outlooks through 2028.
Peer InnoLight (Eoptolink) saw Q3 net income -19% QoQ, with inventory up 141% vs. start of year. Victory Giant's Q3 net income fell 66% QoQ, mainly due to ~RMB 690mn in fair value losses, while ex-non items rose 16% YoY.

NVDA | $5.16tn | -0.8% (AH -1.7%)
The Information: NVDA is in talks to provide multi-billion-dollar credit guarantees for the new cloud 'Nscale', funding a 460MW data center planned for Anthropic. Reports also say Taiwan tester KYE plans a Texas plant with $1.1bn prepayment from NVDA.
TSM | $2.24tn | -1.8% (AH -2.9%)
It bought two AUO panel fabs in Taichung for TWD 38.8bn (~$1.2bn). About 5.9mn sq ft of floor area will be converted into CoWoS advanced packaging capacity.
AVGO | $1.65tn | -1.9% (AH -2.8%)
CDS for AVGO and SPCX recently hit record highs, signaling diverging AI credit. Shares retraced after-hours along with the AI complex.

SPCX | $1.95tn | -0.9% (AH -2.4%)
Bloomberg: SPCX filings show Anthropic as 'Customer B', accounting for 34.5% of its 3Q revenue, surpassing the US Gov. as the largest single customer.
SanHua Intelligent Controls 002050.SZ | $21.8bn | prior close -3.2%
Q3 revenue was RMB 8.37bn (+7.8%), below the RMB 8.55bn estimate. Attributable net income fell 9.6% YoY and was ~15% below consensus, with ex-non also -5%. Liquid cooling revenue was RMB 1.8–2.1bn for the first three quarters, tracking +50% for the year, with 50%–100% eyed next year.
Dolphin Research view: results remain muted, with core OP up just 3%. The new five-year plan targets 15%–20% annual growth for auto parts, notably higher than the past two years. The stock is driven more by optionality in liquid cooling and robotics. (Earnings Review) (Trans)
BYD Co. 1211.HK | prior close -2.6%
Q3 attributable net income was RMB 10.0bn, ~17% below the RMB 12.1bn estimate. Revenue per vehicle was ~RMB 133k, far below the ~RMB 153k estimate, with auto GPM at ~21.5%, down 1.5pt QoQ.
From Apr 2027, export VAT rebates will be cut from 13% to 9%, reducing net profit per exported car by ~RMB 5k. EU hybrid quotas reportedly take effect from Dec 1.
Dolphin Research view: overseas scaling is stalling, shifting profit repair from 'mix + scale' to 'cost control + non-operating gains'. The short-term thesis has broken. (First Take)

RDDT | -3.8% (AH -18.2%)
Q3 revenue was $895mn (+53%), but US DAUq fell by 2.5mn QoQ to 50.7mn. Q4 revenue guidance of $1.0–1.03bn is below the $1.044bn consensus. The company said search referral traffic is declining faster, and Q4 DAUq could fall double digits from the 130mn base, with 'login-only' tests outside the US. (Trans)
COIN | -1.1% (AH -4.8%)
Q3 revenue was $1.22bn (-35% YoY), in line with estimates. Net income of $719mn was mainly from unrealized crypto gains. It projects market annualized revenue topping $200mn, with derivatives plus cash trading at ~25% of trading revenue. (Trans)

Tencent 0700.HK | $433.4bn | prior close -2.6%
At the 10/29 Global Digital Ecosystem Conf., Tencent said the Hy4 stable release is imminent, and Hy4 flash will be launched soon. It reports on 11/18.
BABA | $247.6bn | -1.4% (Alibaba 9988.HK prior close -2.8%)
Attendees relayed that Alibaba Cloud's CTO said Qwen4 will be released next week with 1M context support.

Eastroc Beverage 605499.SH | $11.3bn | prior close -1.3%
Q3 revenue was RMB 6.15bn (+0.8%), the slowest since listing. Attributable net income was RMB 1.28bn (-7.7%). Energy drinks fell 8.6%, the first single-quarter decline since listing.
Dolphin Research view: the special drinks slowdown is a ceiling, not weather, and the category likely enters a 'zero-to-slightly-negative growth' maturity stage. (First Take) (Earnings Review)
At ~RMB 75bn market cap and ~RMB 4.8bn full-year net income, the multiple is ~16x, near the soft drink sector's ~15x average. (Earnings Review)
SBUX | +2.2% (AH -1.8%)
US same-store growth held about flat vs. last quarter, but the driver shifted from traffic to ticket, with the company for the first time listing price increases as a ticket driver. Intl nearly stalled with traffic turning negative.
Store opex ratio fell materially, with Q4 OPM up 450bp to ~14%. FY27 North America same-store is guided to ~4%, with margins around Q4 levels. (Trans)
Dolphin Research view: margins look fine and FY27 EPS guide is slightly above estimates. But revenue was a touch light and traffic slowed sharply, so EPS growth relies more on margin and buybacks. (First Take)


| Date | Event | Focus |
| 10/30 11:00; 18:00 | BoJ rate decision; Eurozone 3Q GDP flash | Expected to hold at 1.25%, watch rate-path stance; QoQ expected to slow from 0.6% to 0.2% |
| 10/31 | A-share Q3 reporting deadline | Compute hardware earnings diverge |
| 11/2 AH; 23:00 | AAPL, PLTR earnings | See previews below |
| 11/3 | US midterms; AMD, ANET earnings | ME geopolitics post-election; AMD preview below |
| 11/4 | ARM, QCOM, DDOG, COHR earnings | AI CPUs, smartphones, optics |
| 11/5 | LITE, IREN, AAOI earnings | M&A talks and new cloud financing |
| 11/6 21:30 | US Oct nonfarm | Dec hike or not |

AAPL | 11/2 AH
Watch: iPhone Duo sold out and full-year shipment target raised. The key risk is storage-driven pressure on hardware GPM, with INTC just blaming PC weakness on DRAM price hikes.
Dolphin Research focus: iPhone revenue and Dec-quarter guide, GPM, and Services growth.
PLTR | 11/2 AH
Watch: after NOW's plunge, the market wants to see if the AI software leader can keep accelerating. The stock's premium makes it sensitive to any slowdown.
Dolphin Research focus: US commercial growth, remaining contract value, and the magnitude of full-year guide raise.
AMD | 11/3 AH
Watch: INTC's broken guide pulled AMD down 6.8% after-hours. Bulls focus on server CPU share and MI450 ramp, while bears worry about PC drag.
Dolphin Research focus: data center revenue (EPYC and Instinct), MI450 cadence, and GPM.
Recent daily recaps
2026-10-29: Dolphin Daily | Punish Google, reward Microsoft? Results rule
2026-10-28: Dolphin Daily | AI prospectus rescues AI trades, 'growth' memory loses believers
<End here>
Risk disclosure and statement: Dolphin Research Disclaimer and General Disclosure
Microsoft
USMSFT
Alphabet - C
USGOOG
Amazon
USAMZN
Alphabet
USGOOGL
Goldman Sachs
USGS
Alphabet Inc Pref Shares GOOGN 6.25 05/15/2029
USGOOGN
GOLDMAN SACHS GROUP INC DEP SHR REP 1/1000TH PFD SER A
USGS-A
GOLDMAN SACHS GROUP INC DEP SHS REPSTG 1/1000TH PRF SER C
USGS-C
GOLDMAN SACHS GROUP INC DEP REP 1/1000TH PRF D
USGS-D
Intel
USINTC
04335
HK04335
META
USMETA
AMD
USAMD
AAPL
USAAPL
NOW
USNOW
SNDK
USSNDK
MRVL
USMRVL
ARM
USARM
MU
USMU
SKHY
USSKHY
UNXD
SGUNXD
The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.