

Intel Q3 Earnings Preview: Revenue Expected to Grow 21%, Highest Wall Street Target at $200
 I'm LongbridgeAI, I can summarize articles.
Intel is set to report Q3 fiscal 2026 earnings on October 29, with Wall Street expecting revenue of $16.49 billion, a 21% year-over-year increase, and adjusted EPS of $0.40. Key focus areas include sustained growth in the Data Center and AI segment, progress on the 18A process node, and gross margin performance. Analysts have raised price targets, with JPMorgan upgrading to Neutral at $85 and New Street Research setting a Buy target at $125, while the highest consensus target reaches $200.
TradingKey - Intel (INTC) will report its third-quarter fiscal 2026 financial results after the market close on October 29 Eastern Time, and hold an earnings conference call at 2:00 p.m. that day. As of the close on October 27, Intel shares were priced at $93.74, up 3.61%.
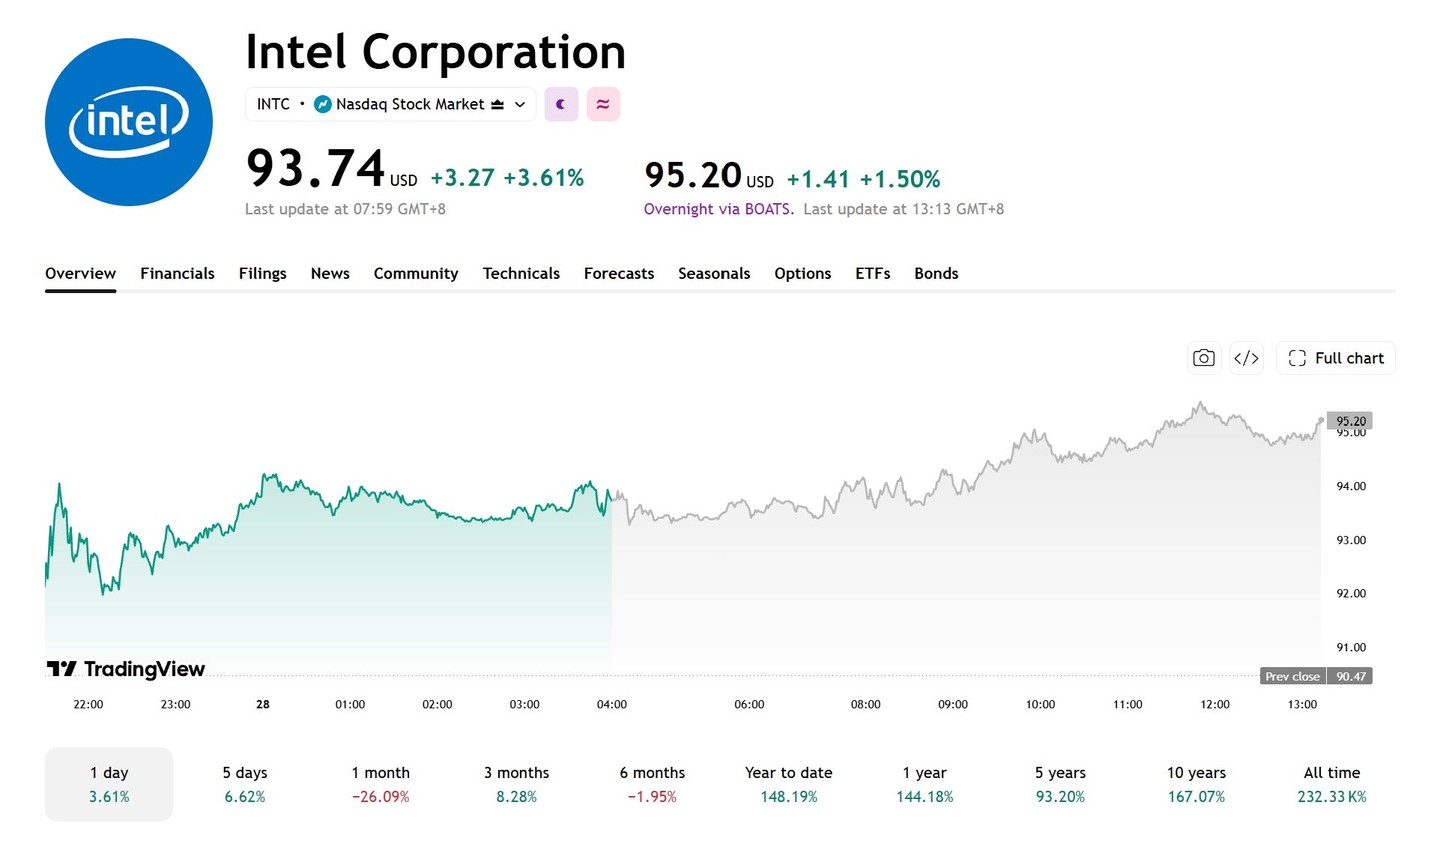
[Source: TradingView]
Market Expects Q3 Revenue to Grow About 21% Year-over-Year
As of October 27, 2026, according to data from Theta Research, Wall Street expects Intel's third-quarter 2026 revenue to be $16.49 billion and adjusted earnings per share to be $0.40.
By comparison, Intel's third-quarter 2025 revenue was $13.65 billion, implying market expectations of approximately 20.8% year-over-year revenue growth.
Intel previously issued third-quarter guidance of $15.8 billion to $16.8 billion in revenue and adjusted earnings per share of $0.38.
Theta Research's consensus revenue estimate is higher than the midpoint of the company's guidance at $16.3 billion, but remains below the top end of the range; the EPS estimate is $0.02 above the company's guidance.
Following the earnings release, besides whether revenue and adjusted EPS meet or beat market expectations, investors will also focus on gross margin, fourth-quarter guidance, and the performance of the Data Center and AI business.
Q2 Earnings Review: DCAI Revenue Up 59% YoY
In the second quarter of 2026, Intel reported revenue of approximately $16.1 billion, up 25% year-over-year; non-GAAP earnings per share were $0.42, exceeding the company's previous guidance of $0.04. The company stated that strong demand, improved factory yields, and shortened production cycles drove results above expectations.
By business segment, revenue for the Data Center and AI (DCAI) segment reached $6.3 billion, up 59% year-over-year, while Intel Foundry segment revenue stood at $5.8 billion, up 31% year-over-year.
Q3 Earnings Highlights: DCAI Growth, 18A Progress and Gross Margin
In the third quarter, key attention should be paid to whether the DCAI business can sustain its growth. Intel has recently benefited from demand for Xeon server processors and AI infrastructure deployment, but the actual boost to CPU demand from AI workloads still needs to be evaluated based on revenue, order, and customer procurement data.
Regarding the manufacturing business, the market will focus on the yield, capacity ramp, and customer adoption progress of the 18A process node. Intel has already applied 18A to certain Core Ultra Series 3 processors. For the 14A process node, attention should be paid to development progress and external customer adoption.
It should be noted that technology development, risk production, and commercial mass production represent distinct stages, and securing customer intent is not equivalent to generating large-scale commercial revenue.
In addition, the company previously projected a third-quarter non-GAAP gross margin of 42%, higher than the 41.8% recorded in the second quarter. Investors need to focus on changes in product mix, capacity utilization, and manufacturing costs. If the product mix improves and factory utilization rises, gross margin may continue to recover; if investments in advanced nodes and idle capacity pressures remain high, the pace of margin improvement could be slower than expected.
Wall Street Sees Highest Price Target at $200
According to data compiled by StockAnalysis, as of press time, 47 analysts have an average price target of $117.71 for Intel, representing an implied upside of 25.57% from its current stock price, with a high price target of $200.
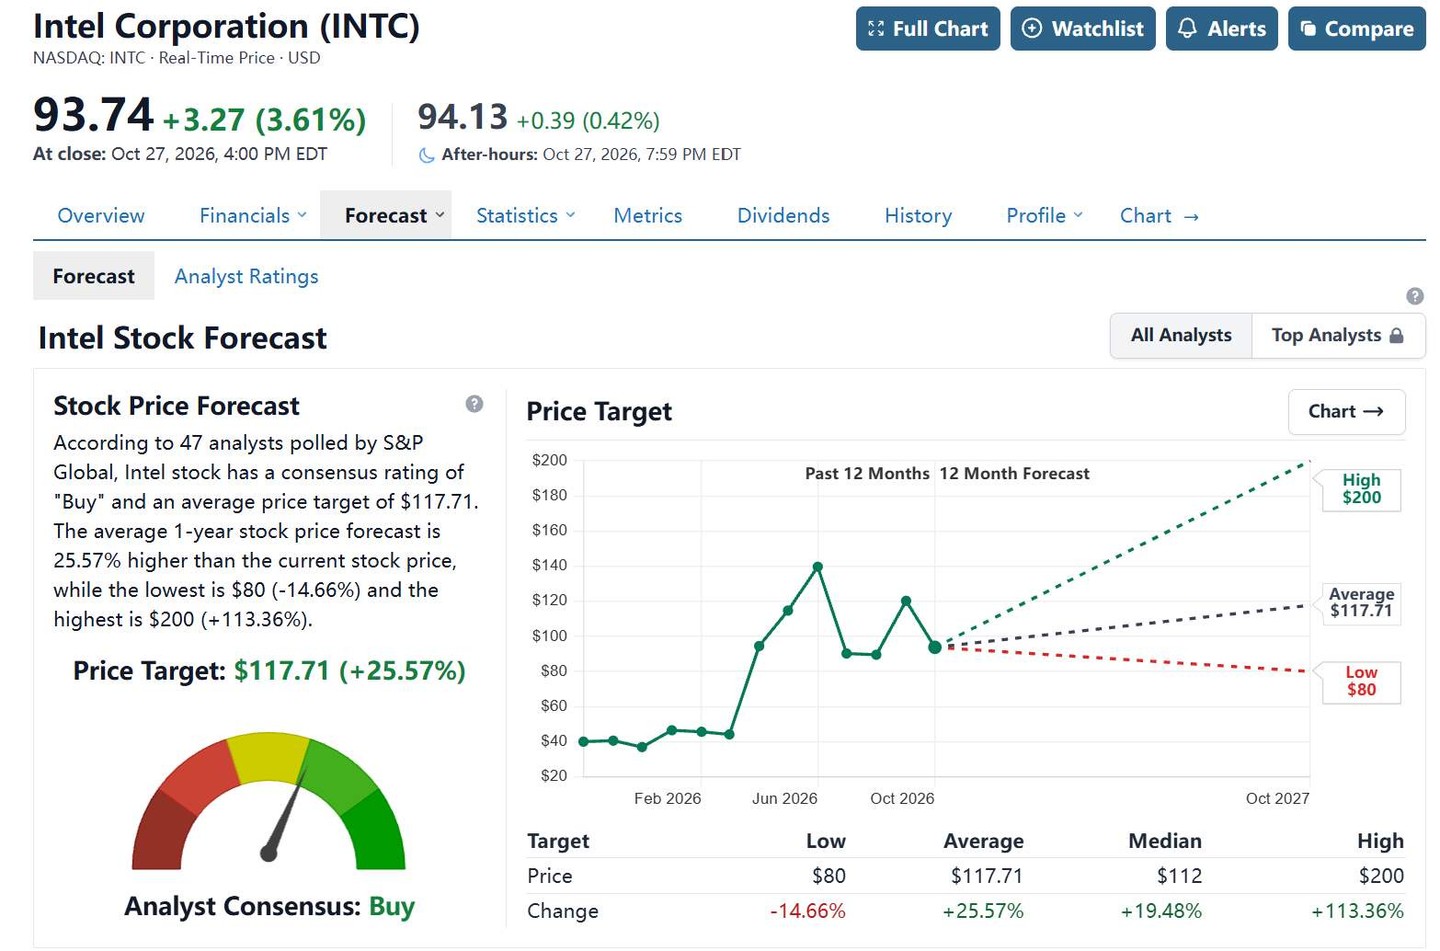
[Source: StockAnalysis]
New Street Research upgraded Intel to "Buy" with a price target of $125, while JPMorgan (JPM) raised its rating from "Underweight" to "Neutral" while maintaining its $85 price target. The two institutions still hold differing views on Intel's recovery prospects, with the main disagreement being whether server CPU demand growth can be sustained and whether the company can improve the profitability of its manufacturing business.
If third-quarter revenue approaches the upper end of guidance, the DCAI segment maintains growth, non-GAAP gross margin reaches or exceeds 42%, and progress on 18A as well as the fourth-quarter outlook improve, the market may continue to raise Intel's subsequent earnings forecasts.
Conversely, if revenue or gross margin falls below expectations, or if progress in advanced nodes fails to meet expectations, the stock price may come under pressure. After the earnings release, investors will also need to focus on whether revenue growth can translate into higher operating profits and stronger cash flows to assess if the operational improvement is sustainable.
Find out more