

Wuliangye's Q3 report "bombshell"! Liquor stocks rise against the trend, is it time to position?
 I'm LongbridgeAI, I can summarize articles.
In recent years, the baijiu industry has entered a period of dual overlap between the macroeconomic cycle and the industrial adjustment cycle, resulting in a relatively sluggish performance. After entering 2025, the development of the baijiu industry remains pessimistic, with the stock competition situation continuing to evolve and market competition becoming increasingly fierce.
According to the "2025 China Baijiu Market Mid-Term Research Report" jointly released by the China Alcoholic Drinks Association and KPMG, in the first quarter of this year, national baijiu production was 1.032 million kiloliters, a year-on-year decrease of 7.2%, continuing the downward trend in production.
Against this backdrop, the market had already anticipated poor performance from baijiu stocks, but $WLY(000858.SZ)'s third-quarter report still caught some investors off guard.
Wuliangye's Latest Quarterly Performance Plummets
After the market closed on October 30, Wuliangye released its third-quarter report for 2025.
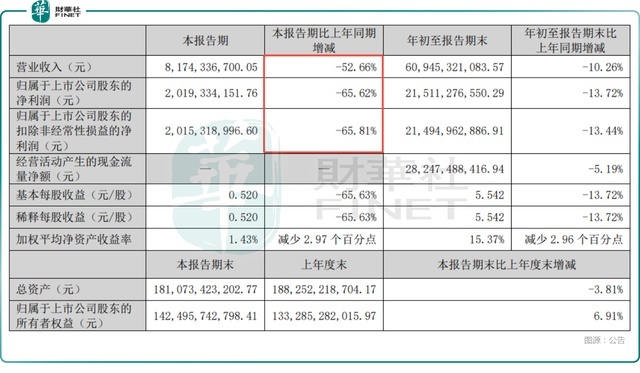
The data shows that in the first three quarters of 2025, Wuliangye achieved total operating revenue of 60.945 billion yuan (RMB, same below), a year-on-year decrease of 10.3%; net profit attributable to the parent company was 21.511 billion yuan, a year-on-year decrease of 13.7%; non-GAAP net profit attributable to the parent company was 21.495 billion yuan, a year-on-year decrease of 13.4%.
In particular, in the third quarter, Wuliangye achieved total operating revenue of 8.174 billion yuan, a year-on-year decrease of 52.7% and a quarter-on-quarter decrease of 48.4%; net profit attributable to the parent company was 2.019 billion yuan, a sharp year-on-year decline of 65.6% and a quarter-on-quarter decrease of 56.4%; non-GAAP net profit attributable to the parent company was 2.015 billion yuan, a sharp year-on-year decline of 65.8% and a quarter-on-quarter decrease of 56.4%.
Additionally, in the third quarter, Wuliangye's gross profit margin fell by 13.53 percentage points year-on-year to 62.6%, and the net profit margin attributable to the parent company fell by 9.31 percentage points year-on-year to 24.7%.
On the cost side, Wuliangye has clearly "tightened its belt." The data shows that in the first three quarters of 2025, Wuliangye's sales expenses were 6.630 billion yuan, a year-on-year decrease of 14.9%; management expenses were 2.299 billion yuan, a year-on-year decrease of 5.5%.
In particular, in the third quarter, Wuliangye's sales expenses were 1.234 billion yuan, a sharp reduction of nearly 50% compared to 2.423 billion yuan in the same period last year, effectively halving sales expenses.
In another announcement released at the same time, Wuliangye also announced its 2025 interim dividend plan—a cash dividend of 25.78 yuan per 10 shares (including tax), with a total proposed cash dividend of 10.007 billion yuan (including tax).
It is not hard to see that Wuliangye's overall performance in the first three quarters of this year has declined, with the third quarter being particularly "miserable." Some investors even believe that Wuliangye's third-quarter report was a "bomb."
How Are Other Baijiu Stocks Performing?
It is worth noting that Wuliangye is not the only baijiu stock to experience a decline in performance this year.
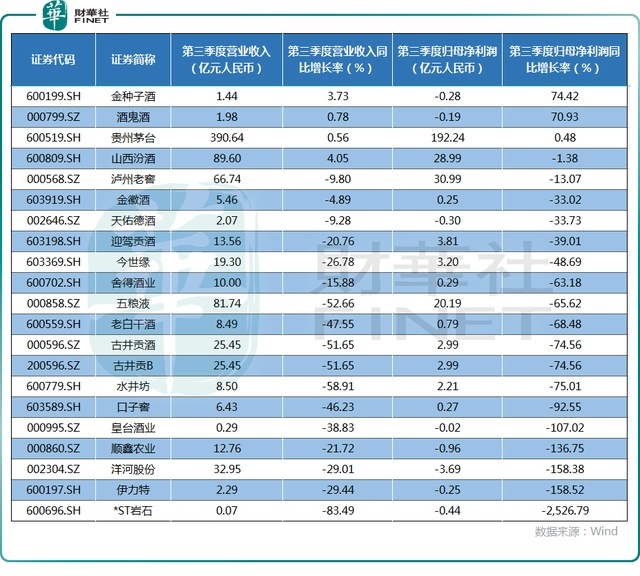
Taking the third-quarter performance as an example: on the revenue side, only $SHANXI FEN WINE(600809.SH), Jinzhongzi Liquor, Jiuguijiu, and $Moutai(600519.SH) saw revenue growth in the third quarter, with the best performer, Shanxi Xinghuacun Fen Wine, achieving only a 4.1% year-on-year growth rate.
On the profit side, 13 companies reported profits in the third quarter, while 8 reported losses, with $Yanghe(002304.SZ) recording a single-quarter loss of 369 million yuan, ranking at the bottom of the list.
In terms of marginal changes, only Jinzhongzi Liquor, Jiuguijiu, and Kweichow Moutai saw year-on-year growth in net profit attributable to the parent company in the third quarter, with growth rates of 74.4%, 70.9%, and 0.5%, respectively.
The net profit attributable to the parent company of all other liquor companies declined in the third quarter. Among them, 16 liquor companies saw a year-on-year decline of more than 30% in net profit attributable to the parent company in the third quarter, including Wuliangye, Yanghe Brewery, and $King’s Luck(603369.SH).
In addition to baijiu stocks in the A-share market, there is also a leading baijiu stock in the Hong Kong stock market—Zhenjiu Lidu (06979.HK).
As of October 31, 2025, Zhenjiu Lidu has not disclosed its third-quarter report. However, based on its interim results, in the first half of the year, the company's revenue fell by 39.6% year-on-year to 2.497 billion yuan, and net profit attributable to the parent company fell by 23.5% year-on-year to 575 million yuan, while adjusted net profit fell by 39.8% year-on-year to 613 million yuan.
Judging from the first-half performance alone, Zhenjiu Lidu has also failed to escape the impact of the industry, with its performance also declining.
Baijiu Stocks Show Strong Performance Today
Against the backdrop of industry downturn and poor performance, the stock prices of baijiu companies have generally been weak this year.
Data shows that in the A-share market, as of October 31, only Jiuguijiu, Luzhou Laojiao, Shanxi Xinghuacun Fen Wine, and Jinhuijiu recorded gains, with stock price increases of 15.59%, 12.82%, 6.93%, and 4.08%, respectively.
All other baijiu stocks have declined this year, with seven falling by more than 15%. Jinzhongzi Liquor and *ST Yanshi performed the worst, with year-to-date declines of 21.88% and 53.58%, respectively.
Meanwhile, Zhenjiu Lidu in the Hong Kong stock market has performed relatively strongly, rising nearly 33% year-to-date, outperforming baijiu stocks in the A-share market.
It is worth mentioning that although the overall trend of baijiu stocks has been weak this year, the baijiu sector unexpectedly showed strong performance on October 31.
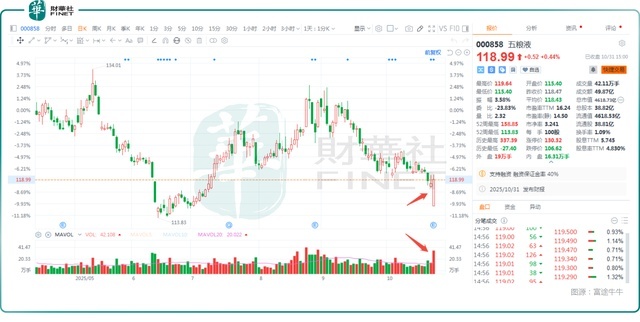
In particular, after Wuliangye disclosed its "bomb" performance, its stock price quickly rebounded after opening 2.6% lower, eventually closing up 0.44% on heavy volume, showing relative strength.
In addition, in the A-share market, Gujing Gongjiu, Yingjia Gongjiu, and Shede Jiuye all rose more than 5%, while Luzhou Laojiao, Shuijingfang, and others also recorded gains. In the Hong Kong stock market, Zhenjiu Lidu rose more than 2%, with only Yanghe Brewery falling slightly by 0.03%.
Today, both the Hong Kong and A-share markets fell, but baijiu stocks managed to rise against the trend, showing strong performance.
What Do Institutions Think About the Future Market?
As a star industry in the market, the baijiu sector and its leading companies, despite the widespread decline in performance, remain highly favored by institutions.
Regarding Wuliangye, CITIC Securities stated in its latest research report that, looking ahead to the fourth quarter, the baijiu industry's sales momentum remains under pressure, with Wuliangye's wholesale price hovering between 820-830 yuan. The company is expected to continue adjusting its market strategy, actively shedding burdens to clear its books. In the short term, 2025 is the company's "Marketing Execution Enhancement Year," with plans to strengthen product sales, optimize channels, and enhance service capabilities to boost brand value and market share. For the Wuliangye main brand, the eighth-generation Wuliangye will prioritize price over volume, improve cost control and efficiency, optimize incentive payouts, and increase support for key and weak markets, while strengthening tactical coordination between 39-degree Wuliangye, Wuliangye 1618, and the eighth-generation Wuliangye. The restructuring of Wuliangye's strong-flavor products is gradually showing results, and growth is expected to improve amid favorable sales momentum in the mass market. At the channel level, the company will implement a "one place, one policy; one merchant, one policy" strategy, with tiered, classified, and graded management for high-ground, key, weak, and untapped markets. It will continue to advance the "three stores, one home" initiative, optimize incentive payouts and market order control, and further enhance channel strength. In the long term, the company's brand power continues to rise, with strong consumer loyalty. By optimizing channel organization and dealer profitability, greater market momentum can be unleashed, and growth prospects remain promising.
For baijiu stocks, Guosen Securities believes that the sector's valuation recovery will occur in two stages. 1) Combined with the Mid-Autumn Festival and National Day sales, industry demand is expected to recover sequentially. The market has largely priced in expectations for performance and prices, and valuations will recover as demand improves, with greater sensitivity to policy expectations and liquidity improvements. This constitutes the first stage, driven by dividend yield pricing, with Kweichow Moutai's PE expected to recover from 20x to 25x, corresponding to a dividend yield of about 3%. 2) Looking ahead to the second stage of valuation recovery, when industry supply-demand dynamics improve and indicators such as prices and performance materialize, the market's "long-duration faith" in baijiu assets will return. Kweichow Moutai will meet the conditions for DCF valuation, and the sector's PE midpoint is expected to reach 30x, with the earliest possible occurrence in the fourth quarter of 2026.
Guosen Securities believes that signs of industry bottoming are increasing, and the sector is entering a phase for strategic positioning. It recommends buying high-quality blue-chip stocks with relatively stable performance and current product and channel strategies that offer greater long-term growth potential, while also suggesting attention to distressed companies that may rebound after risk clearance.
CITIC Securities stated in a recent research report that the performance of the 2025 Autumn Sugar and Wine Fair met expectations, with the industry actively embracing the consumer end to expand market demand. Looking ahead, the firm believes the industry's fundamental bottom is likely to appear in the third quarter of 2025, with the third quarter of this year expected to be the most challenging period for sales momentum, prices, and market confidence. It is anticipated that the second half of this year will be the most pressured period for baijiu-listed companies' financial performance. Given the clear recovery trend thereafter, the firm is optimistic about bottom-fishing opportunities in the baijiu industry.
Soochow Securities' research report stated, "Baijiu is accelerating its bottoming process, with expectations leading the way. Market pessimism has already been reflected, and the accelerated bottoming aligns with expectations. As such, we recommend focusing on the timing of 'left-side positioning.'"
Author: Ming Xi


The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.