
longbridgelongbridge
  • Platform Features
    Features
    Investment ProductsPrivate Wealth ManagementTrading ToolsMarket Data ServicesAnalysis ToolsNews ServicesFor Developers
    Account Types
    For IndividualsFor Institutions
  • Café
longbridge
© 2026 Longbridge|Terms of ServicePrivacy Policy
Shyon

Shyon

AssetsTop 18%ReturnsTop 36%

Mechanical engineer who loves technical trades

Mechanical engineer who loves technical trades

Total AssetsRate Of ReturnGo Beyond!
8Following28Followers170Likes & Bookmarks
Shyon
Shyon
ArticlesOriginalFollowingFollowersStocks mentioned

Who to follow

S
Shyon1 day ago, 08:56 AM

🚨 Higher for Longer? Why I'm NOT Waiting for a Market Crash (And How I'd Invest $10,000 Today)

The Four Most Dangerous Words in Investing: “I’ll Wait for a Better Entry” What if the biggest risk in a higher-interest-rate environment isn't the market?What if it's doing nothing?For the past few ye...

HIGHER FOR DISCIPLINE MARKETS PEOPLE DIVERSIFICATION IDEAS COMPOUNDING A BETTER
40% U.S.TECHNOLOGY LEADERS Building 9 PEOPLE IDEAS W Brighter TECHNOLOGY FUTURIS
20% Financials & Re People Dividend Stocks Protection Prosperity STABLE·INCOME ·
INFLATION GEOPOLITICAL STORMS MARKET VOLATILITY RISING PRICES WARS & CONFLICTS C+6
My Investment Diary
S
Shyon1 day ago, 08:38 AM

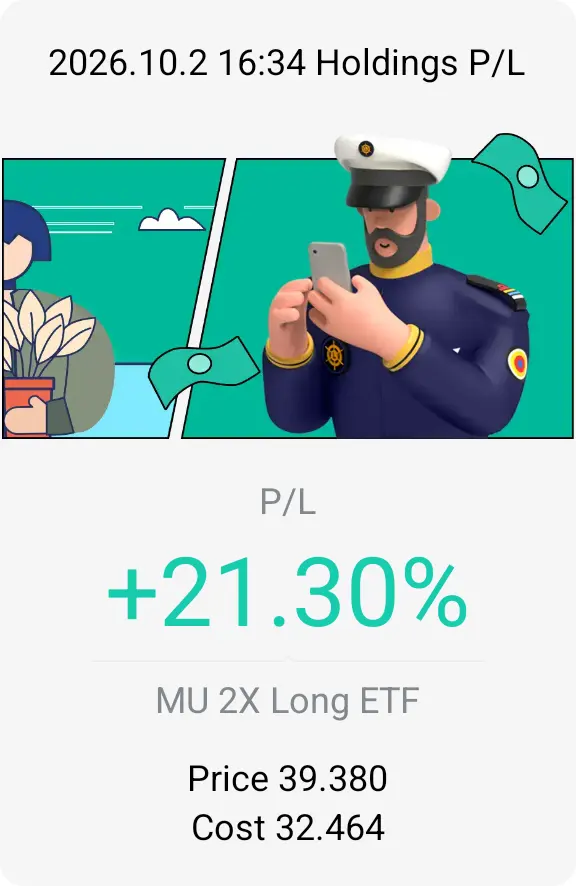
MUU Paper Profit Jumps to 21% After Micron Earnings

$MU 2X Long ETF(MUU.US) Strong Earnings, Stronger Follow-ThroughMy MUU position just got another boost. My paper profit has jumped from around 13% to 21% following the positive move in Micron after it...

2026.10.2 16:34 Holdings P/L P/L +21.30% MU 2X Long ETF Price 39.380 Cost 32.464
MU 2X Long ETF

MU 2X Long ETF

USMUU

Trade Showcase: Trade, Show & Earn Rewards!
S
Shyon1 day ago, 04:58 AM

For me, I am more interested in the memory trade than SG banks right now. $Micron Tech(MU.US) saying more than 75% of its 2027 output is already committed gives me more confidence that the memory cycle is being supported by real AI infrastructure demand, rather than just short-term excitement. With MU and MUU already in my portfolio, I am looking for the follow-through to continue, but I still prefer adding on pullbacks instead of chasing a strong move.

At the same time, tonight’s payroll report could bring another layer of volatility, especially with Treasury yields still elevated. I would rather see how yields and the broader market react first before adding aggressively. For me, the plan remains simple: stay patient, collect quality semiconductor exposure on weakness, and avoid letting one strong session push me into FOMO.

C
Captain's Watch
☕️ [Task Coins Giveaway] Daily Market Talk — Micron's 2027 Is 75% Sold

Micron says more than 75% of its 2027 output is already committed, and memory names followed through overnight. The 10-year touched its highest since 2002 before pulling back. At home, SGX is down abo...

Micron Tech

Micron Tech

USMU

S
Shyon2 days ago, 02:45 AM

FeaturedMicron Just Delivered a Monster Earnings — So Why Is My MUU Still Flat?

I am currently sitting on around a 13.5% paper gain in my $MU 2X Long ETF(MUU.US)  position, so naturally I was looking forward to Micron’s earnings last night. I was expecting another strong report t...

图片 1,共 1 张
MU 2X Long ETF

MU 2X Long ETF

USMUU

Trade Showcase: Trade, Show & Earn Rewards!
S
Shyon2 days ago, 02:37 AM

I think the $Micron Tech(MU.US) reaction is a good reminder that strong earnings do not always mean an immediate stock rally. The numbers were impressive, but expectations were already extremely high, so even a major beat can be largely priced in. For me, the more important question is whether AI-driven memory demand can keep accelerating into the next few quarters, especially with HBM and data-center demand supporting pricing. I would rather watch the next guidance updates and demand visibility than chase the initial earnings reaction.

I am still constructive on the longer-term AI memory cycle, but I would not assume every strong result will translate into an instant upside move. With Treasury yields still above 5.2%, valuation and macro conditions can easily offset good company-specific news. I see this as a situation where patience matters: if the fundamentals continue improving while the stock consolidates, I would be more comfortable accumulating gradually rather than chasing a flat or sudden breakout.

C
Captain's Watch
☕️ [Task Coins Giveaway] Daily Market Talk — Micron Beats Big, Stock Shrugs

Micron printed a record $54.2B quarter, guided to $61.5B, and the stock closed flat. A cooler PCE pushed October hike odds below a coin flip, but the 10-year still climbed above 5.2%. Let's dig in 👇💬 ...

Micron Tech

Micron Tech

USMU

S
ShyonSep 30 at 04:06 AM

Featured🚀 Micron’s Trillion-Dollar Moment: Will This Earnings Report Ignite the Next AI Supercycle?

The semiconductor industry has become the beating heart of the AI revolution, and few companies are benefiting more than$Micron Tech(MU.US). Once viewed as a cyclical memory-chip manufacturer, Micron ...

图片 1,共 8 张
图片 2,共 8 张
图片 3,共 8 张
图片 4,共 8 张+4
Micron Tech

Micron Tech

USMU

Micron Guides $61.5B After A $54B Beat
S
ShyonSep 30 at 03:39 AM

For me, $Micron Tech(MU.US) guidance matters more this week. The memory cycle is becoming much more than a traditional cycle story, with strong AI server demand, tight DRAM supply and growing HBM demand supporting the longer-term outlook. I am especially watching whether Micron can raise its revenue, margin and HBM outlook rather than simply beat the current quarter.

PCE still matters because a hotter inflation print could keep Treasury yields elevated and pressure high-growth tech stocks. But for my portfolio, I think Micron’s forward guidance could have a more direct impact on the semiconductor names I am holding and watching. I would rather focus on the fundamentals and demand outlook than chase the immediate post-earnings move.

C
Captain's Watch
Featured☕️ [Task Coins Giveaway] Daily Market Talk — PCE Tests the Fed, Micron Tests the Memory Boom

Fed's Williams saw "no need for urgency" on the next hike, cutting October odds to a coin flip ahead of tonight's PCE. Then Micron reports before dawn Thursday, with Street targets from $1,100 to $2,0...

Micron Tech

Micron Tech

USMU

S
ShyonSep 29 at 01:59 PM

My vote is Up 4.3% to 8.6%. I am moderately bullish because $Micron Tech(MU.US) enters earnings with strong AI-driven memory demand, tight supply and solid pricing power. I will be watching DRAM/NAND pricing, HBM demand and FY2027 guidance more than the headline EPS beat.

The risk is that MU has already rallied sharply this year, so expectations are high and a “sell the news” reaction is possible. Still, if Micron confirms strong HBM demand, improving margins and continued memory tightness, I think the stock can deliver a positive move within my +4.3% to +8.6% range.

C
Captain's Watch
Micron Earnings Challenge — Guess the close and win cash!

$Micron Tech(MU.US) reports Q4 FY2026 after the US close, Wednesday 30 September — the numbers land around 04:00 SGT Thursday morning, with the call at 05:00. ⏰📊 Where Micron Stands Going InOptions ma...

EARNINGS PREVIEW ·US 1 LONGBRIDGE The print that became a market event Micron Te
图片 2,共 2 张
Micron Tech

Micron Tech

USMU

S
ShyonSep 29 at 03:19 AM

I would not rush into an Anthropic IPO at a $2 trillion valuation. The revenue growth is impressive, with 2025 revenue reaching nearly $4.6 billion, but the scale of spending is what makes me cautious. Reuters reports that the $42 billion net loss included about $34 billion of accounting charges, so it is not the same as burning $42 billion of cash, but the company still had more than $8 billion in operating losses and plans around $518 billion in future cloud, computing and infrastructure commitments.

For me, this is a case where I would rather watch first than chase the IPO on day one. I am bullish on the long-term AI infrastructure theme, but a $2 trillion valuation already prices in an enormous amount of future growth. I would want to see how quickly Anthropic can turn its explosive revenue growth into sustainable margins and cash flow before building a meaningful position. At this valuation, patience matters more than FOMO for me.

C
Captain's Watch
Featured☕️ [Task Coins Giveaway] Daily Market Talk — Anthropic's IPO Filing Reveals a $42B Loss

Reuters got a first look at Anthropic's IPO prospectus: revenue up 12-fold, a $42 billion net loss, and a $2 trillion valuation target. Meanwhile Treasury yields hit fresh multi-decade highs and gold ...

S
ShyonSep 28 at 03:13 AM

For me, I am watching $Micron Tech(MU.US) most closely this week ahead of the September 30 earnings. The recent strength in AI infrastructure continues to support the memory cycle, but I do not want to chase the stock purely on expectations. I am looking for evidence that HBM, DRAM and NAND demand remains strong, while pricing and margins continue to improve. Earnings guidance will be especially important because it can tell us whether the current AI memory demand is sustainable or already priced in.

I am still comfortable holding and gradually adding on pullbacks rather than making a large move before earnings. With Treasury yields staying elevated and October hike expectations still in focus, volatility could remain high even if Micron delivers solid numbers. My approach is simple: follow the fundamentals, respect the technical levels, and let the earnings confirm the thesis instead of chasing the excitement.

C
Captain's Watch
Featured☕️ [Task Coins Giveaway] Daily Market Talk — Trump Rejects Iran Deal, Oil Rebounds

Wall Street closed its first up-week in three, then Trump rejected Iran's seven-day Hormuz offer over the weekend, sending Brent higher again and US futures lower into Monday. Microsoft led the week's...

Micron Tech

Micron Tech

USMU

S
ShyonSep 25 at 03:53 AM

For me, the Anthropic-Akamai deal is another reminder that AI infrastructure spending is still expanding even as the cost of capital rises. I am still constructive on the long-term AI story, especially semiconductors and compute infrastructure, but I am becoming more selective about valuation and leverage. A 5.5% 30-year Treasury yield changes the opportunity cost significantly, so I would rather accumulate quality AI names gradually on pullbacks than chase a strong move after the headlines.

I am also watching PCE and the jobs report closely because higher-for-longer rates could create more volatility for growth stocks and REITs. I would not rush to make a major portfolio shift based on one rate move. My approach remains simple: keep some cash available, continue DCA into companies I understand, and use weakness to build positions instead of FOMO buying strength. AI demand can remain strong while multiples still compress, so I think both the growth story and the cost of money need to be respected.

C
Captain's Watch
☕️ [Task Coins Giveaway] Daily Market Talk — Akamai Jumps 21% on Anthropic

Anthropic's $11.6B compute deal sent Akamai up ~21% after hours, even as the 30-year yield hit a 2004 high of 5.5% and Williams called another hike "reasonable" — AI keeps spending while money gets pricier.

S
ShyonSep 25 at 02:20 AM

Featured🚀 My Nebius Position Is Finally Paying Off — But Is NBIS Getting Too Hot?

$Nebius(NBIS.US) 📈 From Paper Loss to Around +12%Nebius has become one of the more interesting AI infrastructure positions in my portfolio. I am currently sitting at approximately a 12% paper gain, an...

2026.9.25 10:16 Holdings P/L P/L +12.20% Nebius Price 242.360 Cost 216.000
Nebius

Nebius

USNBIS

Trade Showcase: Trade, Show & Earn Rewards!
S
ShyonSep 24 at 01:56 PM

For me, this looks like more than a short-term rotation. With the 10-year Treasury above 5%, investors are becoming more selective toward companies with heavy capex and distant cash flows. That explains why semiconductors can face pressure even while long-term AI demand remains strong.

I also think software deserves more attention as AI monetization becomes easier to measure. Companies like PLTR and MSFT can potentially turn AI into higher revenue and free cash flow without the same infrastructure burden. The key question is shifting from whether AI makes money to which part of the AI stack captures the profits.

Personally, I would not simply sell SOXX and buy IGV after one sharp move. I still believe chips are essential to AI, so I prefer accumulating quality names gradually while watching rates, credit spreads, and earnings. For me, cash flow will increasingly separate the winners from the stories.

C
Captain's Compass
🎁[Reward] Higher Yields, Wider Divide: Stricter On Hardware Stocks?

The 10-year Treasury yield briefly topped 5%, the highest since 2007. The Fed is hiking again, oil is above $105, and AI infrastructure companies are borrowing heavily — competing with Treasuries for ...

Spread vs. Us Benchmark Bond-10 Year ICE BofA US High Yield (Right) 一 350 340 33
Average annual infrastructure spending as a percentage of GDP Telecom Canals Rai
图片 3,共 3 张
S
ShyonSep 24 at 03:58 AM

I would not rush to trim growth stocks just because the 10-year yield moved above 5%. Higher yields clearly put pressure on high-valuation growth stocks, but I see this more as a reason to be selective and manage position sizes rather than exit the AI trade completely.

For me, a sharp pullback can actually create better opportunities to DCA into companies where the long-term fundamentals remain strong. I would rather buy gradually on weakness than chase when prices are running, while keeping enough cash to handle further volatility. The key is whether earnings and AI demand continue to justify the valuations.

C
Captain's Watch
Featured☕️ [Task Coins Giveaway] Daily Market Talk — 10-Year Yield Tops 5%, Highest Since 2007

A blowout US PMI pushed the 10-year Treasury yield through 5% to a 19-year high, lifting October hike odds to about 70% and ending the Nasdaq's record run. After the bell, Meta used Connect to push Mu...

S
ShyonSep 23 at 03:10 AM

For me, the $Sandisk(SNDK.US) story is interesting, but I would not chase the stock simply because Wall Street raised the target. AI memory demand is clearly a strong long-term theme, and SanDisk is benefiting from the growth in data-center storage, HBM and AI infrastructure. At the same time, memory is still a cyclical business, so a very high price target also comes with very high expectations. I would rather watch earnings, pricing and demand trends than follow a target price blindly.

I also understand why Burry is taking the opposite side, especially with memory and semiconductor valuations having moved so strongly. Personally, I am more comfortable staying invested in the semiconductor theme through pullbacks and gradual accumulation rather than trying to predict the exact top. For me, the key question is not whether SanDisk can rally further, but whether AI-driven memory demand can remain strong enough to support the current cycle.

C
Captain's Watch
Featured☕️ [Task Coins Giveaway] Daily Market Talk — SanDisk Rockets to $2,400 Street-High Target as Burry Shorts It

Wall Street just handed SanDisk its highest price target yet, even as Michael Burry doubles down shorting the same chip sector. Meanwhile Alibaba's AI blitz from Apsara is cooling off this morning, an...

Sandisk

Sandisk

USSNDK

S
ShyonSep 23 at 02:55 AM

FeaturedOCBC Correction Almost Over? I Am Ready to Ride the Next 5X Move 🚀

$OCBC 5xLongSG280223(9RWW.SG) I am still holding my OCBC 5X Long DLC (9RWW) $OCBC 5xLongSG280223(9RWW.SG) , and after the recent correction in Singapore banks, I am starting to see this as an interest...

)OCBC $OCBC 5X Long D DLC (9RWW) 9x 9RWW FUNDAMENTAL STRENGTH: SINGAPORE BANKING
OCBC Bank

OCBC Bank

SGO39

Trade Showcase: Trade, Show & Earn Rewards!