

PDD


$BABA-W(09988.HK)Is Alibaba Actually Expensive or Is the Market Betting on Growth?🤔I am a Alibaba shareholder. This is …
$BABA-W(09988.HK)
Is Alibaba Actually Expensive or Is the Market Betting on Growth?🤔
I am a Alibaba shareholder. This is the question i always ask myself.
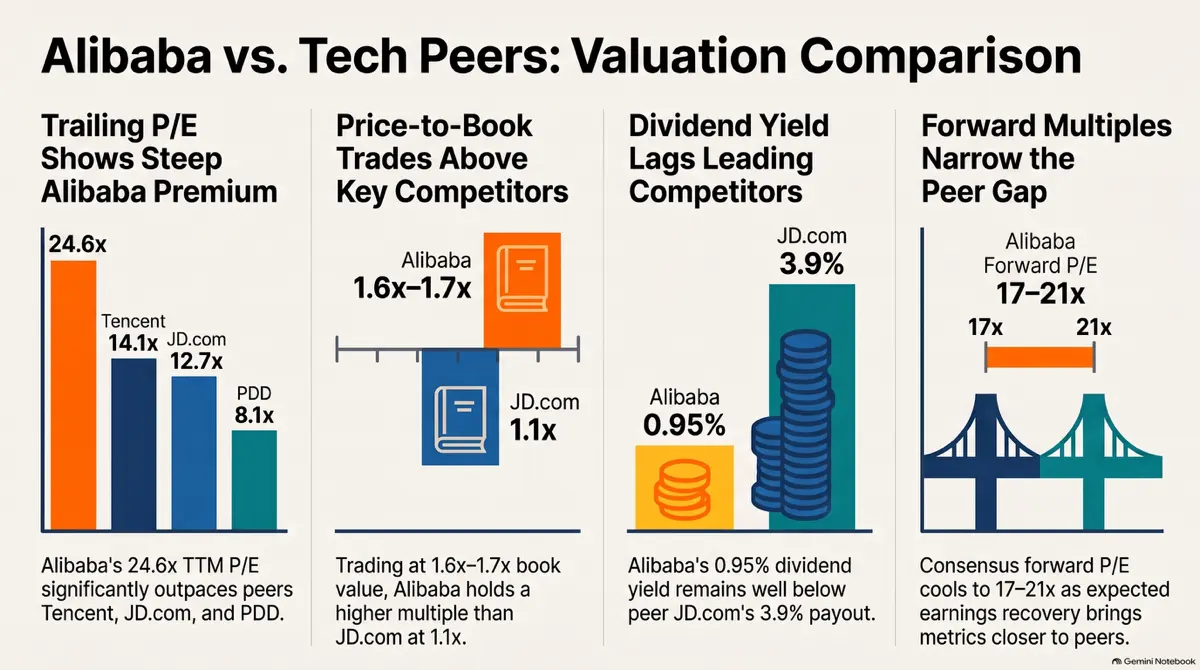
At first glance Alibaba looks pricier than its peers. Its trailing P/E ratio stands at 24.6. That is about 1.7x Tencent at 14.1x. It is nearly 2x JD.com which ranges from 12.7 to 16.2x.
Furthermore, it is roughly 3x PDD Holdings at 8.1x. On price to book(PB Ratio), Alibaba trades at 1.6 to 1.7x compared to JD at 1.1x.
Alibaba also pays a modest dividend yield of 0.95% while JD offers 3.9%.
So why does Alibaba trade at a premium?
The answer lies in how earnings are being calculated. Trailing earnings have been pulled down by fair value losses on investments and heavy spending on AI infrastructure.
In fact net profit dropped 74.2% in the first quarter of FY2027. This makes the trailing P/E look much higher than it really is.
If you look ahead the market expects earnings to bounce back. The forward P/E falls to around 17.3x once earnings normalised.
Revenue growth is projected to pick up to 14.5 percent year on year. Investors are not paying extra for today’s lower profits.
They are betting that Alibaba’s expansion in AI and cloud will drive strong gains in the future.
Do you believe in Alibaba’s AI turnaround? I am with Alibaba. I believe the strategy and the light to the tunnel is coming ☺️
The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.