Fattycat

Fattycat

AssetsTop 6%ReturnsTop 23%

Full Time ACCA CA Accountant with 22 years of trading experience.

30Following1,233Followers3,083Likes & Bookmarks
F
Fattycat

Good afternoon everyone ☺️

I expected PPI to jump following Thursday's CPI figures and it did. The real surprise was gold. It stayed calm and resilient, barely budging. Perhaps the earlier jitters were a false alarm. I am still not fully convinced.

Meanwhile, Hang Seng Tech performed well today. Alibaba up 3.95%, Tencent +1.24%. The HK market looks deeply undervalued to me. It is just a matter of time before funds rotate back here.

Have a good weekend ahead to everyone. Trade safely. Always have your own “Target profit”, stock loss and don’t be greedy ☺️.Cheers

C
Captain's Watch
Featured☕️ [Task Coins Giveaway] Daily Market Talk — Hot PPI Turns Citi and UBS Hawkish

September PPI landed a full point above forecast, and two big banks changed their rate calls. At home, September exports came in at double the forecast. Let's dig in 👇💬 With a December hike priced nea...

F
Fattycat

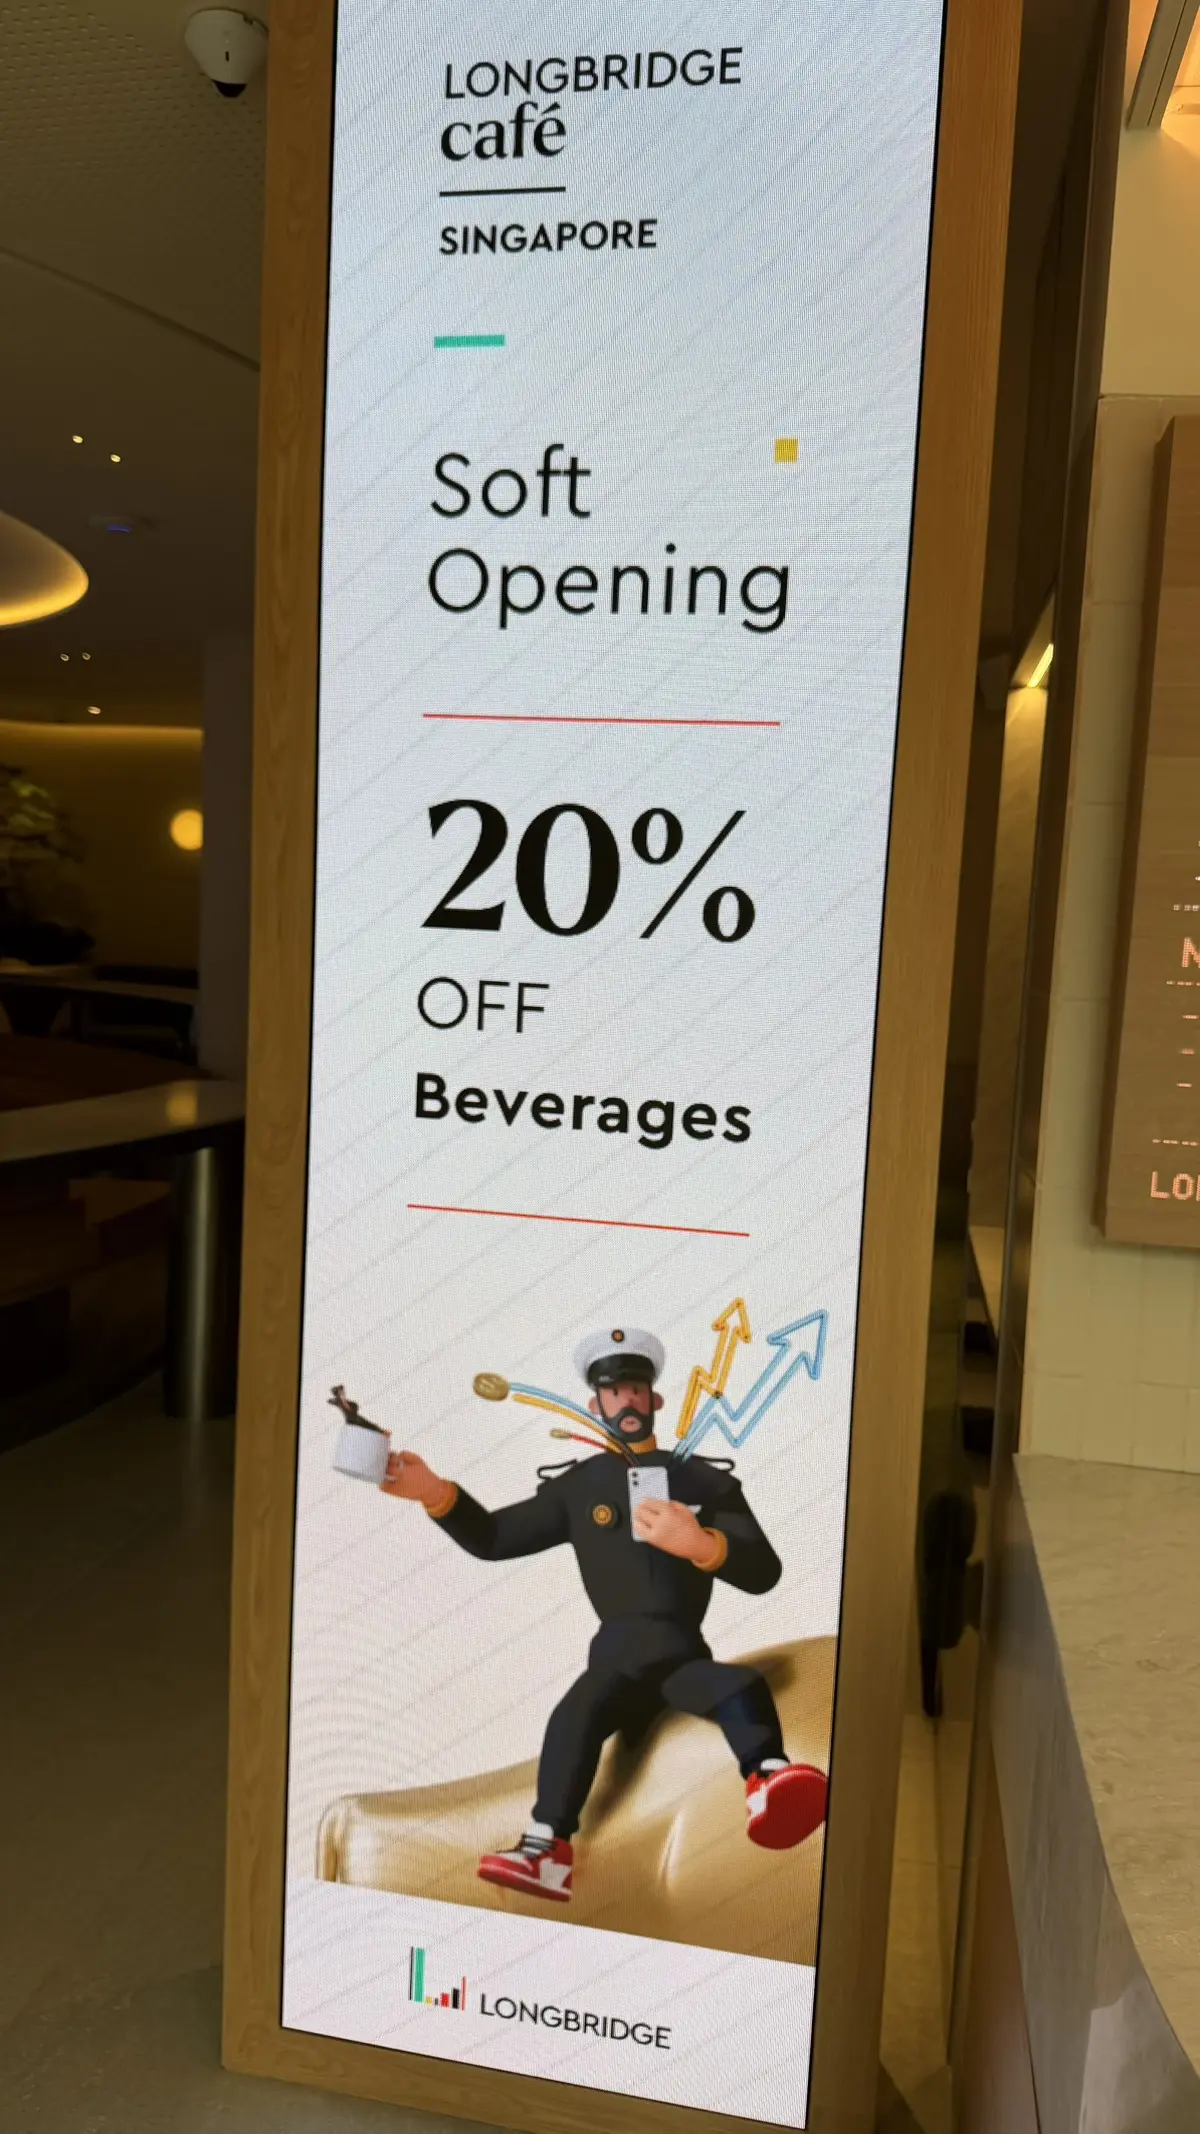
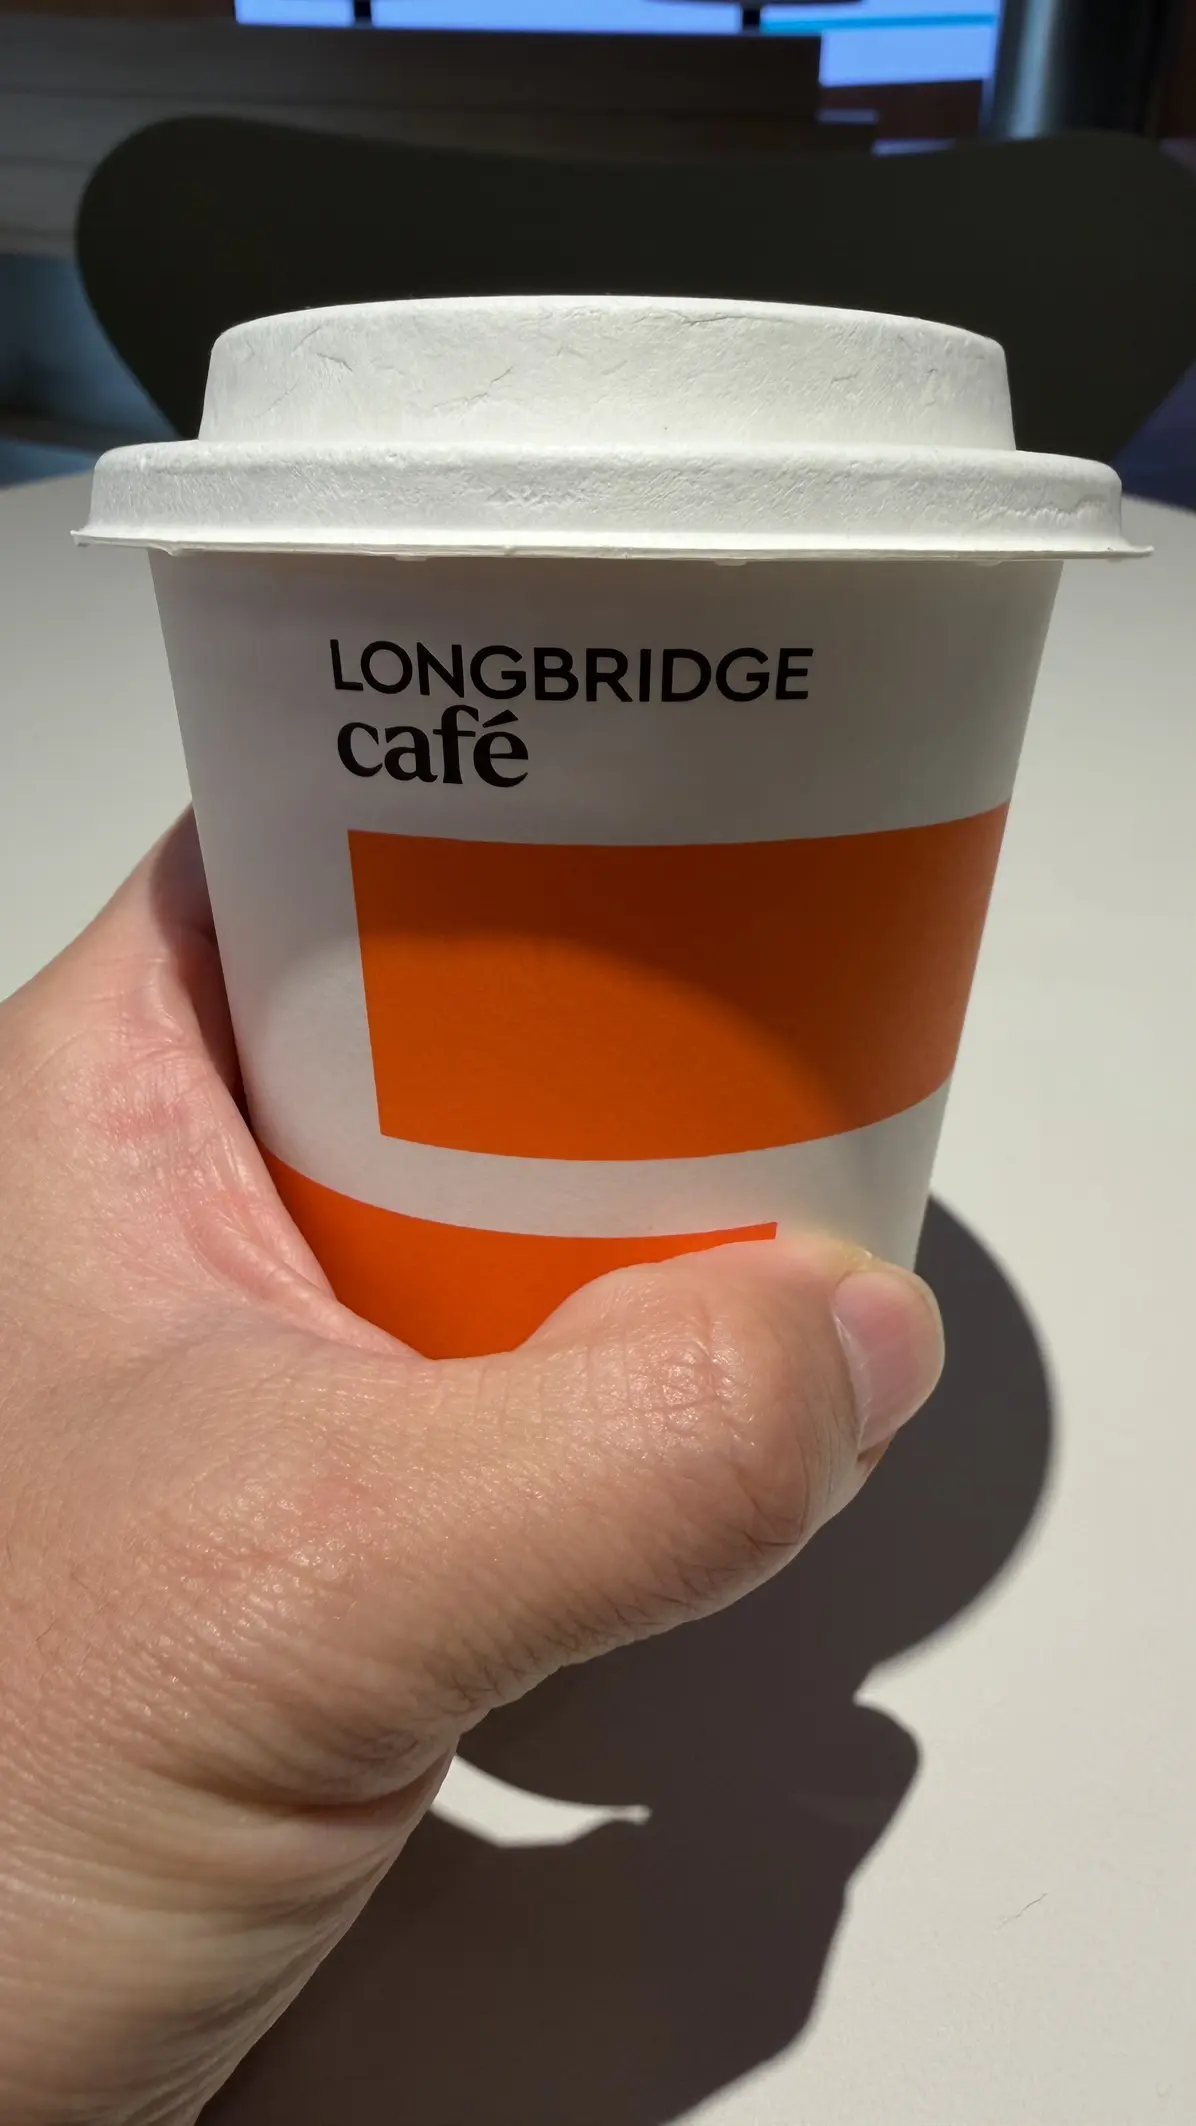
I decided to visit Longbridge Cafe for a hot mocha today. Great atmosphere and no crowds. So relaxing to sit here during lunch. ☕

Come come and use your voucher here 🤣.

LONGBRIDGE cafe
LONGBRIDGE cate SINGAPORE Soft Opening 20° %0 OFF Beverages LO 1 LONGBRIDGE
TAI AUN
LONGBRIDGECafe 包 器 OADGE+1
F
Fattycat

$XIAOMI-W(01810.HK)

🚀 Xiaomi (1810.HK): EV Momentum & Analyst Views

Recently, Xiaomi is drawing plenty of attention! Here is a quick look at what is driving the story and its share price 👇

🚗 Strong EV Momentum

The SkyNomad series secured more than 70,000 firm orders in its first month. Monthly deliveries are rising rapidly to meet strong demand, reflecting fast-growing consumer enthusiasm. This remains Xiaomi’s most exciting growth story right now.

📈 Analyst Ratings & Targets

The consensus is firmly BUY / OUTPERFORM, with an average 12-month target price ranging from HK$34.40 to HK$34.70 — that is over 30% upside from around HK$27 recently.

• Citi: BUY, HK$34.00 target

• Goldman Sachs: BUY, HK$39.00 target

• Bernstein: BUY, HK$35.00 target

• Guosheng Securities: BUY, HK$51.00 target

🔄 More Than Just Cars

Beyond EVs, analysts also highlight Xiaomi’s growing “Human × Car × Home” ecosystem powered by HyperOS, stronger premium smartphone sales, and share buybacks worth over HK$1.27 billion. These all help underpin the company’s long-term value.

Do you share the same view as analysts? Let’s share your thoughts.☺️

📊 See the full picture in our infographic!

Not financial and investment advice. Please do your own due diligence ☺️.

ni XIAOMI CORP(1810.HK) ANALYST COVERAGE & MARKET RATINGS CONSENSUS OUTLOOK LATE
F
Fattycat

$CSE Global(544.SG)

💡 Staying Patient, Seeing Value- My CSE Global Entry

Made an important decision yesterday. Bought 1,200 shares of CSE Global at S$0.92. 😁

The RSI was deep in oversold territory and the price had halved from its highs. To me, this looked less like a failing company and more like a quality business trading at a value discount.

Price is what you pay; value is what you get. The market can be emotional in the short run but over time fundamentals tend to win out.

I don’t expect an instant rebound. Value investing means being patient and comfortable looking a little lonely at times. But I believe in buying when others are fearful, especially when the numbers back it up. 🚀

Let’s see how this unfolds.

Here’s to the quiet confidence of buying value when it goes on sale! 😁

Fattycat 2026-10-1609:45:54 CSE Global 544 P/L% +4.34% Market 0.960 SGD, Cost 0.
< 544 CSE Global Trading 10/16 09:46:22 742 Quotes Related Products Overview Fin
Trade Showcase: Trade, Show & Earn Rewards!
F
Fattycat
Featured

$CSE Global(544.SG)

📉 CSE Global Down 50% — Time to Buy or Stay Away?

Here is our quick look at CSE Global

Price has fallen sharply from its 52-week high of S$1.89 to S$0.930. It is now trading well below its key moving averages. The RSI sits at just 17.35, signalling deeply oversold conditions.

Valuation-wise, the stock is at its lowest point in a year, in the 18.4th percentile and well below its 1-year average P/E of 20.57x.

Meanwhile, the business itself remains resilient. H1 revenue grew a strong 27.35% year-on-year to S$561.47 million, even though margins and profits faced pressure from higher financing costs.

Looking ahead, there are positive catalysts , including S$190.5 million in new US electrification contracts and an ongoing strategic review with Jefferies advising.

Is this steep drop a great buying opportunity or does the market have good reason to be cautious?

See the full technical and valuation breakdown in the infographic on your panel!

Not financial and investment advice. Please do your own due diligence.☺️

CSE Global CSE Global (544.SG): Technical & Valuation Analysis MARKET SNAPSHOT &
CSE CSE Global Limited D SGD~ 0.930-0.090(-8.82%) 1.35 BB 20 SMA close 2 1.30 1.
F
Fattycat

$XIAOMI-W(01810.HK)

My Xiaomi Story - Holding Strong and never give up✊

Currently holding 1,600 Xiaomi-W (01810) shares, average cost HKD 30.135 ☺️

Yes, I am down -11.26% on paper right now but conviction never shaken. 💪

The recent rally is already validating Xiaomi’s bold strategic shift into EVs. The Pengcheng lineup speaks for itself: 70,000+ orders locked in the first month alone, that’s outstanding early demand. 🚀

Furthermore, Xiaomi’s ambitious plan in Europe expansion coming next year. This is just the beginning of the growth story.

Xiaomi is not just a phone brand anymore, it is building a smart energy & mobility ecosystem that will run for decades.

Short-term fluctuations do not change the long-term vision. I strongly believed patience pays off. 😘😍😘

This is not investment or financial advice. It is just my passion sharing about my investment journey and conviction✊✊✊👊🏽.

图片 1,共 2 张
图片 2,共 2 张
Trade Showcase: Trade, Show & Earn Rewards!
F
Fattycat
Featured

📊 US CPI Tonight: Will Gold Shine or Face Pressure? 🥇

All eyes are on tonight’s US CPI release!

The latest inflation numbers will move gold prices, Fed rate expectations, and the US bond market.

Just remember, markets react not only to the figures themselves but also to how they stack up against forecasts.

🔴 Inflation hotter than expected

Gold may come under selling pressure as the US dollar and Treasury yields climb. Markets could price in higher-for-longer interest rates, pushing any rate cuts further out.

🟢 Inflation cooler than expected

Gold could find strong support. A weaker dollar and falling real yields tend to lift gold, while hopes for future rate cuts may rise.

🟡 Headline up, core inflation cools

This one could trigger mixed moves. Energy costs may lift headline CPI on the other hand a softer core numbers signal easing underlying inflation. Gold and bonds may swing both ways initially.

👀 What to watch closely

Focus on monthly core CPI, the US dollar, the 2-year Treasury yield and real yields.

These tell you if the reaction is likely to last.

⚠️ One key note: A single CPI report won’t decide the Fed’s next move. Jobs data, other inflation gauges, and broader economic conditions all matter too.

Will tonight’s numbers surprise us or you have something in mind.

Check out the full infographic for all three scenarios and what they mean for gold, rates, and bonds.

Not financial and investment advice. Do your own due diligence.

图片 1,共 1 张
PPI Ran Hot Too. Is December A Done Deal?
F
Fattycat

Tonight's CPI figures will likely set the tone for trading ahead. Expect volatility. I believe S-REITs are oversold. They do not deserve this pressure since these REITs are backed by real, income-producing assets. I hope inflation comes in as expected so the market can reassess their true value. Please 🙏🏻

C
Captain's Watch
Featured☕️ [Task Coins Giveaway] Daily Market Talk — Tonight’s CPI Decides the Fed’s Next Move

Three Fed officials backed another rate hike on the same day, hours before tonight's CPI. At home, MAS surprised every analyst by holding. Let's dig in 👇💬 If tonight's CPI runs hot, do you add to rate...

F
Fattycat
Featured

🚀 Why Data Centre S-REITs Are Under Pressure - Even With Booming AI Demand

Keppel DC REIT (AJBU) and NTT DC REIT USD (NTDU) are trading near 52-week lows despite strong structural demand.

Here is what is happening 👇

📉 Macro & Interest Rate Headwinds

• Yield competition: Higher US Treasury yields mean risk-free bonds look more attractive, pulling capital away from dividend stocks.

• Refinancing costs: Older, cheaper debt is maturing and being replaced at today’s higher rates. This directly reduces distributable income.

🏢 What Affects Each One

• NTT DC REIT (NTDU): Still finding its footing post-IPO, plus US dollar currency swings on SGX.

• Keppel DC REIT (AJBU): Higher overall borrowing costs and market caution around specific asset allowances in Guangdong.

💡 The Key Insight

• Business remains strong: Occupancy stays above 98%, and AI plus cloud growth keeps pushing rental income higher.

• It’s pricing, not performance: The drop reflects higher capital costs across the sector, not weakening demand from tenants.

🤔 With prices at these levels, are you adding to your positions or waiting for more clarity?

Not financial and investment advice. Do your own due diligence ☺️.

$NTT DC REIT USD(NTDU.SG)$Keppel DC Reit(AJBU.SG)

图片 1,共 1 张
F
Fattycat

I believe this week belongs to the CPI numbers. One of the most important indicator Fed look at it. Even TSMC's solid results could take a backseat. Let's see how it plays out 😊

Next, in my view, the recent REITs prices have fallen too far. The underlying income-generating assets remain intact. There's simply no good reason for this big a decline. 😪

C
Captain's Watch
Featured☕️ [Task Coins Giveaway] Daily Market Talk — Micron Leads a $108B Memory Rout

Memory was the best trade of the AI boom until Monday, when Micron, SanDisk and SK Hynix shed about $108B between them on news that a Chinese rival is closing the technology gap. At home, the early ba...

F
Fattycat
Featured

🚀Stronger Singdollar: What It Means for Your S-REITs

MAS is widely tipped to tighten policy on 14 October by steepening the S$NEER policy band slope. What does a stronger Singapore dollar mean for our REIT portfolio?🤔

📉 REITs With Overseas Assets (Facing Headwinds)

• Lower Distributions: Rental income earned overseas converts into fewer Singapore dollars, pulling DPU down.

• Valuation Impact: Foreign assets revalue lower in SGD terms. This pushes net asset value down and gearing ratios higher on paper.

🛡️ Pure Singapore REITs (Naturally Protected)

• Cost Savings: A stronger SGD helps fight imported inflation. It keeps utility, cooling and maintenance expenses in check.

• No Currency Risk: With all assets based in Singapore there is zero translation loss. Plus SORA rates stay lower than US rates, a helpful bonus.

📌 In Short

Where a REIT owns its assets matters most during an MAS tightening cycle. Pure-play domestic REITs offer much stronger resilience against currency swings and operational cost pressure.

See the full details in the infographic! 🖼️

Not investment or financial advice. Do your you due diligence ☺️.

Source: Economists expect MAS to tighten monetary policy again in October, though some see room for a pause- Business times 12 Oct 2026.

图片 1,共 1 张
F
Fattycat
Featured

$BYD COMPANY(01211.HK)$XPENG-W(09868.HK)$GEELY AUTO(00175.HK)

🚗📉 China’s EV Export Rebate Is Being Cut - What It Means

Oh No …. China will lower the VAT export rebate for new energy vehicles from 13% to 9%, starting 1 April 2027. 🥹

This change could squeeze profit margins for Chinese automakers selling overseas.

For companies like BYD, Geely and XPeng, the key question is straightforward. Who will pay this extra cost?😟

Automakers have three choices. They can absorb it and earn less per car. They can raise prices overseas and risk losing their competitive edge. Or they can cut costs through better supplier deals and greater efficiency.

The challenge is that Chinese EV makers already compete heavily on price. If they cannot pass this cost to buyers, their profit on each exported car will drop.

BYD is one to watch closely. One analyst estimate suggests the net profit impact could be roughly RMB 5,000 per exported vehicle. This is an estimate though, not official guidance. The real effect will depend on tax calculations, what models are shipped, and how much they can save elsewhere.

For investors, stronger overseas sales no longer guarantee stronger profits.

Will automakers absorb the cost, raise prices, or find ways to protect their margins? Check out the full infographic for the impact breakdown, different scenarios, and what key numbers to watch.

Not financial advice. Please do your own Due diligence 😃.

Source: China cuts NEV export tax rebates, testing profitability of automakers’ overseas growth — CNEVpost, 12 Oct 2026

China's Export Tax Rebate Cut What It Means for Chinese Automakers L 0 A lower V
F
Fattycat

CapitaLand Ascendas REIT: I am Staying the Course

My current position is down -10.25% now, with my average price at S$2.429 and the market price at S$2.180 today 😔.

But you know what?

Prices go up and down. This is part and puzzle of trading. Quality assets stay. Today marks a fresh 52-week low, yet the fundamentals remain solid.

I am looking at a steady ~6.9% dividend yield backed by a diversified portfolio of quality properties and reliable tenants.

Short-term price swings test my patience. They don’t change the underlying value. I am not going to PAPER HAND.

I am staying invested and collecting those distributions while waiting for sentiment to turn. If prices keep dipping, I may even add more. 💪😆

Time in the market beats timing the market. Hang in there everyone. We are in this for the long haul. 🚀

$CapLand Ascendas REIT(A17U.SG)

Fattycat 2026-10-1217:26:35 CapLand Ascendas REIT A17U P/L% -10.25% Market 2.180
< A17U CapLand Ascendas REIT Closed 10/1217:16:00 2.9k Quotes RelatedProducts Ov
Trade Showcase: Trade, Show & Earn Rewards!
F
Fattycat

🙄Is Alibaba a Buy or Avoid Right Now???

Alibaba is back in the spotlight. Citigroup, Bank of America and Jefferies have upgraded their price targets within just 48 hours. Furthermore, Jefferies also named Alibaba its top pick among Chinese internet stocks. But does that mean the stock is truly a bargain right now?🤔

The bullish argument centres on artificial intelligence and cloud computing. Alibaba’s cloud revenue jumped 45% year-on-year in the June 2026 quarter, while overall revenue rose 9% to RMB 268.95 billion. Its Qwen AI models and growing cloud business could drive fresh growth going forward.🥰

However, the picture is not complete without looking at the risks.

Despite rising revenue, net profit dropped 75% compared to a year ago in the same quarter. Alibaba is also investing a massive RMB 380 billion into AI infrastructure and development from 2026 through 2029.

These investments may strengthen its market position but returns are never guaranteed.

At around US$111.37, HKD 108.60, the share price sits well below analyst targets ranging from US$178 to US$193. That implies considerable upside potential if those forecasts hold up.

Do remember that price targets are estimates, not guarantees and the actual valuation will depend on whether earnings can actually grow as expected.

🔷 Key risks include fierce competition, rising AI-related expenses, lower profitability, regulatory changes and geopolitical uncertainty.

🔷 For investors, the real questions are whether cloud growth will translate into solid profits, whether free cash flow can improve despite heavy AI spending, and whether the core e-commerce business can stay competitive.

🔷The verdict

Alibaba may look attractively priced and offer real growth potential, but it is not a guaranteed bargain.

Check out the full infographic for the bullish outlook, downside risks and key metrics to monitor.

For information only. Not financial or investment advice. Always conduct your own due diligence ☺️.

图片 1,共 2 张
< 09988 BABA-W 10/1212:05:00 324.7k Quotes Related Products Overview Financials
F
Fattycat

The Singapore government appears keen to support mid and small-cap stocks.

Over recent years I have noticed that MAS and MOF have rolled out several targeted measures. Their aim was to address the structural valuation discounts and poor liquidity on our local exchange. And they focus falls heavily on mid and small-cap counters. 🤔

Measures include capital injections under the Equity Market Development Programme or EQDP, plus grants for liquidity and research coverage.

Could now be the time to consider small to mid -cap stocks?

Screen shot from CNA finance news.

Commentary: Liquidity fix for small and mid-caps on SGX requires more to be done
C
Captain's Watch
Featured☕️ [Task Coins Giveaway] Daily Market Talk — SpaceX's $8B Spectrum Deal Sinks Telcos

SpaceX is paying about $8B for nationwide spectrum, and US telcos got repriced in one session: AT&T -9.8%, T-Mobile -13%. At home, the banks are bouncing after last week's 5% STI slide. Let's dig in 👇...

F
Fattycat

$BTC/USD(BTCUSD.HAS)

🏆[ Weekly ] Bitcoin Review: Consolidation Before CPI Release

🔷 Technical Snapshots

Bitcoin is trading around $82,928, moving sideways after being rejected from higher levels.

The 4-hour RSI is at a neutral 47.42, with price holding firmly above the key $80,000 support.

On the daily chart, the RSI eased slightly to 51.58. The market is currently trapped between clear boundaries. It faces strong resistance around $87,000 and solid support near $80,000.

🌍 Fundamental Snapshots

All eyes are on the US CPI data due 14 October . Headline inflation is expected to land between 3.6% and 3.7%, driven largely by rising energy prices.

Core inflation is forecast to stay steady at 2.4%. The Federal Reserve has a difficult decision to make on October 28. They must weigh persistent inflation against a cooling jobs market that added only 29,000 positions in September.

Adding pressure, the 10-year Treasury yield climbed to 5.31%, its highest point since May 2002.

Despite these macro challenges, adoption continues to grow. The Hashi Protocol expansion secured $500 million in commitments for Bitcoin-backed lending. This shows rising institutional demand to earn yield on spot holdings.

⚡ The Verdict

Bitcoin remains stuck in a clear trading range from $80,000 to $87,000. Growing network usage and financial applications provide a strong floor beneath prices.

The CPI report will likely decide the next big move. A softer reading could open a push past $87,000. A hotter-than-expected number may trigger a retest of support at $80,000. 😊

Not financial advice. Please do your own due diligence.

B BITCOIN I(BTC/USD) CRITICAL MARKET ANALYSIS TECHNICAL TRENDS Short-Term(4H)Mom
F
Fattycat

📉 Singapore’s Banking Giants Are Falling! Is This a Buying Opportunity or a Warning Sign?

DBS, OCBC and UOB suffered a sharp sell-off during the first week of October 2026, shaking investor confidence in Singapore’s blue-chip banking stocks.

From 6 to 9 October, DBS fell 6.6% to S$73.36, OCBC dropped 9.9% to S$29.00, while UOB declined 8.6% to S$39.96.

After a strong multi-year rally, is this simply institutional profit-taking and a valuation reset, or the beginning of a deeper downtrend?

🔎 Here are the key technical levels to watch:

🔹 DBS: S$73.00 to S$73.30 is the immediate support zone. A breakdown could expose S$64 to S$65.

🔹 OCBC: S$29.00 is the critical battleground. If it fails, the next support zone is S$24 to S$25.

🔹 UOB: S$40.00 is the psychological level to reclaim. Failure to recover could bring S$38 to S$39 into focus.

⚠️ The key question is whether these banks can stabilise. Oversold conditions may create opportunities for a technical rebound, but they do not guarantee a recovery.

For long-term investors, attractive dividend yields alone are not enough. Valuation, earnings resilience, asset quality and future dividend sustainability still matter.

📊 Read the infographic for the critical support levels and next-week game plan.

Would you buy the dip or wait for clearer signs of a bottom?

Not financial and investment advice. Please do your own research.

SINGAPORE BANKING TRIO SHARP PULLBACK Valuation Reset or Trend Change? XI DBS 9
DBS Group Holdings Ltd D SGD、 73.36-0.49(-0.66%) BB 20 SMA close 2 78.00 人 76.00
(册) United Overseas Bank Limited D SGD· 39.96-0.29(-0.72%) BB 20 SMA close 2 45.
Oversea-Chinese Banking Corp... D SGD 29.000.00(0.00%) BB 20 SMA close 2 34.00 3
Exports Just Printed A Record. MAS Held Early
F
Fattycat
Featured

$Gold.com(GOLD.US)

🏆 [Weekly] : Gold Review: Bouncing Off $4,080, Is This the Bottom or Just a Pause?

🔷 Technical Snapshot

Gold is trading at $4,194.65, up 1.47% on the day. After pulling back from highs around $4,600 to $4,700, price found strong support between $4,000 and $4,080.

The daily RSI is at 45.64, turning up from near-oversold levels. The broader trend remains neutral to bearish for now.

On the 4-hour chart, the bounce looks clearer. Price reclaimed $4,160 and is testing short-term resistance near $4,200 now.

The 4-hour RSI at 60.63 shows rising bullish momentum on this shorter timeframe. The immediate resistance is at $4,200 followed by $4,280 to $4,300. The immediate support sits at $4,120 to $4,160, with the major floor at $4,080.

🔷 The Big Headwind - Real Yields

This bounce is largely technical relief. Elevated global interest rates and the Fed’s cautious stance keep real yields high.

Shiny gold pays no yield hence it creates ongoing fundamental resistance that limits how far this rally can run.

🔷 Strong Support Remains

The $4,000 level has held firm. Central bank demand and safe-haven buying are still active during market uncertainty.

That means there is solid underlying support even if the short-term path is choppy.

🔷 Fundamentals Snapshots- What Comes Next

All eyes are on US data next week. CPI on next Wednesday 14 October and will be the main catalyst, followed by PPI and Retail Sales on Thursday.

🔥 Hot CPI = Higher yields → Stronger USD → Gold may retest $4,080 support

❄️ Cool CPI = Softer rate bets → Weaker USD → Gold may break above $4,200 toward $4,280

Watch for a confirmed 4-hour close above $4,200 or a break below $4,120 before leaning one way or the other.

Are you buying the dip or waiting for clearer signals? Share your thoughts below! 👇

Not financial and investment advice. Please conduct your own due diligence.

GOLD SPOT/U.S.DOLLAR (XAU/USD)-MARKET REPORT Week of Oct 12-Oct 16,2026 Price:$4
Gold Spot/U.S. Dollar USD 4,194.645 +60.955 (+1.47%) 5,600.000 BB 20 SMA close 2
Gold Spot/U.S. Dollar USD 4,194.645 +60.955 (+1.47%) BB 20 SMA close 2 4,520.000
F
Fattycat

🚨 Meituan Down 31%: A Bargain in the Making or a Profit Trap?

Meituan has had a difficult year, with its share price falling 30.8% year to date to HK$71.50 as of 9 October 2026. But does the sell-off present an opportunity or is the market pricing in deeper problems?

📉 Valuation: Looks cheap but with a catch

Meituan’s price to book ratio (P/B) has fallen to 2.20x, near a five-year low. Its price-to-sales ratio is also around 0.97x.

The current trailing P/E is negative because the company reported losses. A low valuation does not automatically mean the stock is undervalued.

💰 Profit recovery is the key

Revenue continued growing, reaching HK$398.77 billion in FY2025. However, the company swung to a net loss of HK$25.53 billion. This is mainly due to Intense competition and subsidies in food delivery and instant retail remain major challenges.

Currently, Investors need evidence that profitability can recover sustainably.

⚖️ Regulatory risks add uncertainty

Beijing has opened an investigation into Meituan and three other travel platforms over suspected unfair competition and booking practices.

Currently, no news on the findings or penalties had been announced. Possible outcomes range from conduct changes to financial penalties or a more serious escalation.

🔍 What should investors watch?

The crucial questions are whether competitive spending eases, profits recover and the investigation remains limited in scope.

Meituan looks historically inexpensive on certain valuation measures but its future depends on earnings recovery.☺️ ( Looking at the weekly chart, Higher timeframe, it appears Meituan may have reached its bottom.)

Please refer to the infographic for the valuation figures, peer comparisons and three regulatory scenarios.

What do you think? Is this a potential turnaround story or a value trap?🤔

Not financially investment advice. Please do your own due diligence.

$MEITUAN(03690.HK)

美团 Meituan MEITUAN: CHEAP ON ASSETS一 美团 美团 BUT IS PROFIT RECOVERY PRICED IN? Val
美 Meituan Class B D C HKD 71.50+2.10(+3.03%) BB 20 SMA close 2 475.0 450.0 425.0
F
Fattycat

$XIAOMI-W(01810.HK)

📈🚀Why Did Xiaomi Jump Over 9%?

Below is the latest infographic that explains what drove Xiaomi’s 9.21% rise today.

1️⃣ Strong Momentum in Auto Business:

The Sky Nomad series drew more than 70,000 firm orders in its first month. September vehicle deliveries passed the 40,000 mark.

2️⃣ Solid Institutional Support:

Net buying continued through Southbound Stock Connect channels.

3️⃣ Growing Product Ecosystem:

Foldable phones saw strong holiday demand. Xiaomi also boosted its brand visibility through partnerships such as the Vision GT debut in Gran Turismo 7.

💡 One question to keep in mind:

Now, one big question, can all these impressive numbers translate into actual profit and better margins for Xiaomi in the long run?🤔

Not financial or investment advice. Please do your checking .

Source : Xiaomi official website.

ni Why Xiaomi Stock Surged Over 9% +9.21% Stock Surge HK$25.84 Sky Nomad Record
< 01810XIAOMI-W Trading 10/09 15:27:23 288.1k Quotes Related Products Overview F
图片 3,共 3 张
F
Fattycat

Has anyone been watching defensive stock Sheng Siong? It just dropped 4.1% this morning .

My own view, it is still expensive.PB ratio at 7.27 forward PE at 26.54. Not attractive to me.

What is your thought ?

Sheng Siong Group Ltd. D SGD 2.96-0.13(-4.21%) BB 20 SMA close 2 3.45 3.40 3.35 Long image
C
Captain's Watch
Featured☕️ [Task Coins Giveaway] Daily Market Talk — OpenAI's $20B Gap Hits AI Stocks

The FT reported OpenAI's annualized revenue is about $20B lower than thought, and the AI chain sold off: Oracle -5.5%, CoreWeave -7.8%, Nvidia -2.9%. At home, the STI closed -3.5% Thursday as all thre...