

Morgan Stanley: AI investment enters a 'deceleration phase', but chip value continues to rise
 I'm LongbridgeAI, I can summarize articles.
Capex growth is decelerating, but AI semiconductors are not peaking in tandem
Over the past two years, the most direct way for the market to gauge AI momentum has been watching whether Meta, Google, Microsoft, and Amazon are willing to continue raising capital expenditures.
In 2026, this indicator remains robust. Morgan Stanley data shows that capex from the top four cloud providers—Amazon, Google, Microsoft, and Meta—grew 87% YoY in Q2, while the Capex/EBITDA ratio has climbed above 70%.
Such high growth rates, however, cannot be sustained indefinitely.
To address this, the report shifts its focus to 2028. Morgan Stanley projects that by then, capex from the top 14 listed global cloud service providers will approach $1.6 trillion, though overall YoY growth may have slowed to around 12%.
On the surface, this figure might suggest that "the AI investment cycle is cooling." However, the report immediately presents another set of data: global 2.5D advanced packaging capacity is still expected to grow ~50% YoY in 2028.
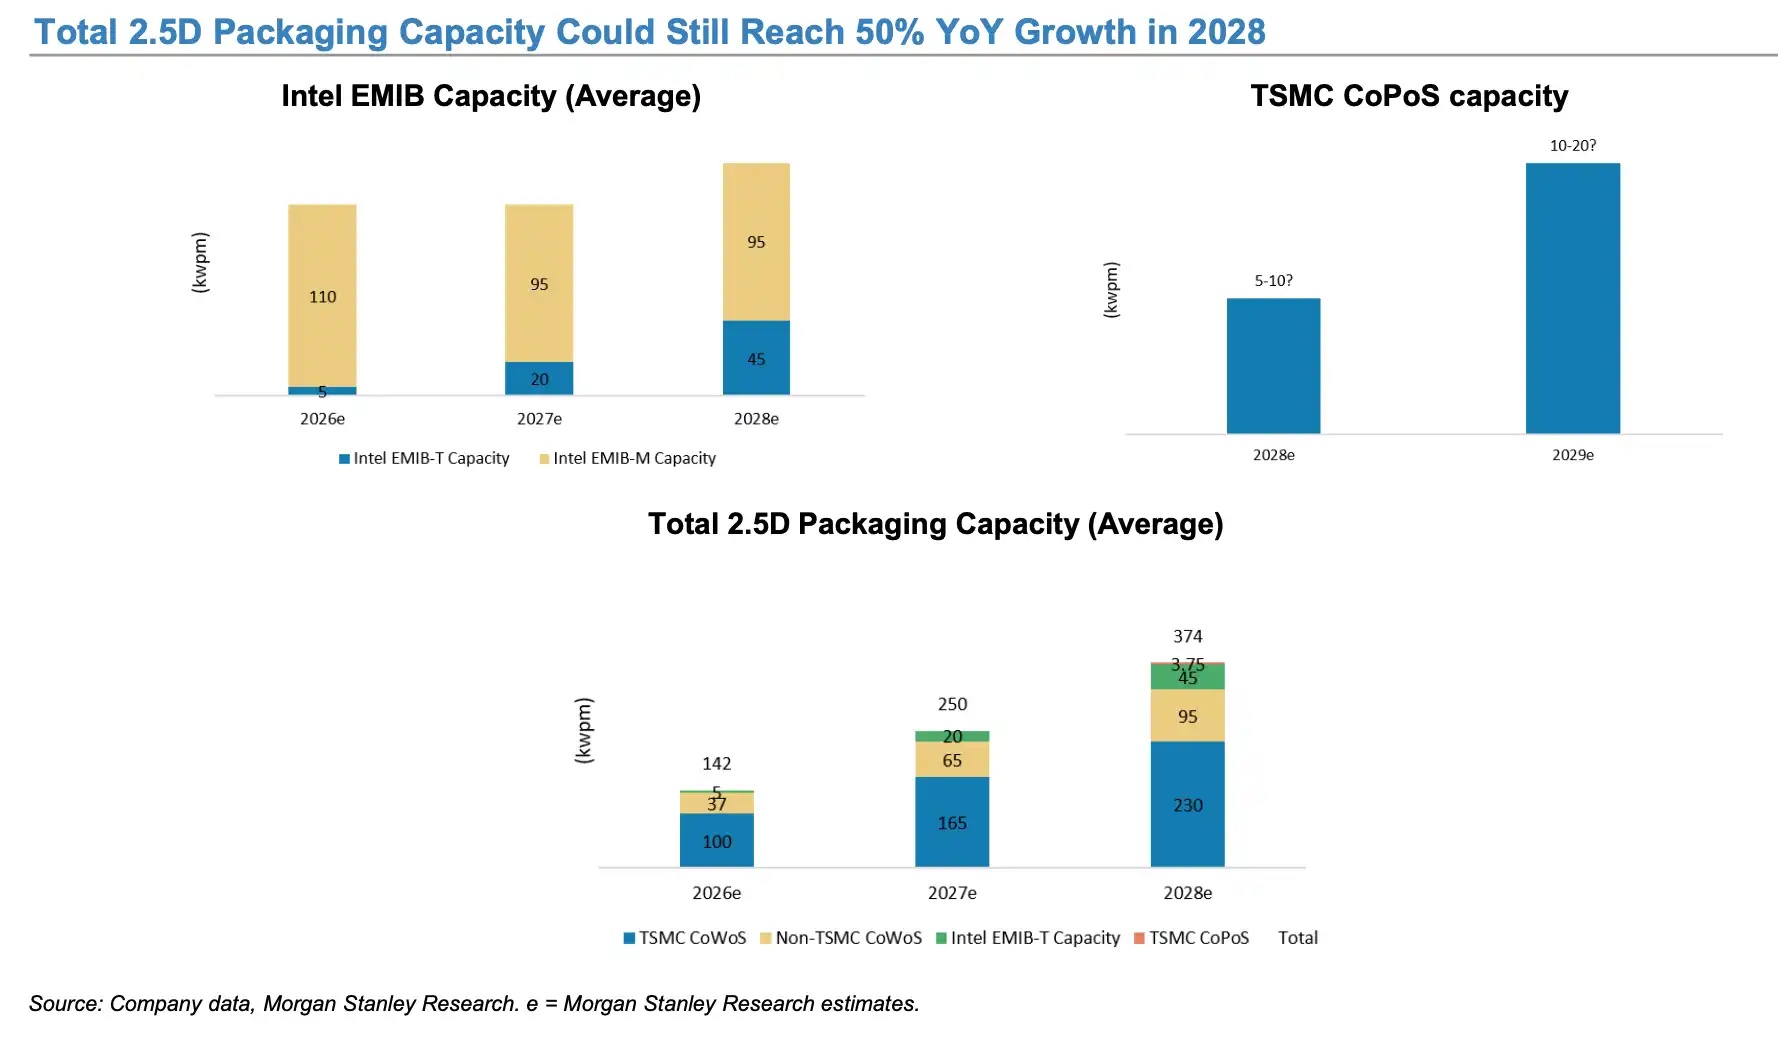
Morgan Stanley expects global 2.5D advanced packaging capacity to potentially grow ~50% YoY in 2028.
This is precisely the most notable aspect of the entire report.
A slowdown in overall cloud provider capex does not equate to a peak in AI semiconductors.
In recent years, AI chip growth was primarily driven by the expansion of total capex: the more data centers built, the more GPUs purchased.
But as we enter the next phase, even if CSP capex growth moderates from 50-80% down to 10-20%, as long as the share of AI within total capex continues to rise, GPUs, ASICs, HBM, advanced nodes, and advanced packaging can still outperform total capex growth.
In other words, the market is transitioning from a "total volume story" to a "structural story."
Morgan Stanley's long-term market size forecasts reflect this shift. The report estimates that by 2030, the global semiconductor industry could reach ~$1.5 trillion, with the AI semiconductor TAM at ~$753 billion, accounting for nearly half of the total market. In an optimistic supply-chain-driven scenario, the cloud AI semiconductor market could hit $485 billion in 2026. Notably, the $485 billion figure represents a bull case explicitly noted in the report, rather than the base case.
Meanwhile, divergence between AI and non-AI semiconductors is widening.
The report predicts that excluding memory and NVIDIA AI GPU revenue, non-AI semiconductor growth could actually decline in 2026. This implies that this cycle can no longer be simply mapped onto the traditional framework of "overall semiconductor industry recovery."
The true high-growth segment is the independent supply chain formed by AI continuously absorbing wafer, memory, advanced packaging, and testing resources.
Growth logic is shifting from "buying more GPUs" to higher AI value per unit
If the core of Phase 1 AI investment was "buying more GPUs," the more critical question for Phase 2 is: exactly how many more expensive, complex semiconductors does each AI server require?
TSMC is the most direct example.
Morgan Stanley estimates that AI semiconductors may account for over 30% of TSMC's 2026 revenue. Meanwhile, TSMC's N2 family capacity is expected to achieve a ~70% CAGR between 2026 and 2028; N3 capacity will continue to increase, while N5 may begin to decline starting in 2027.
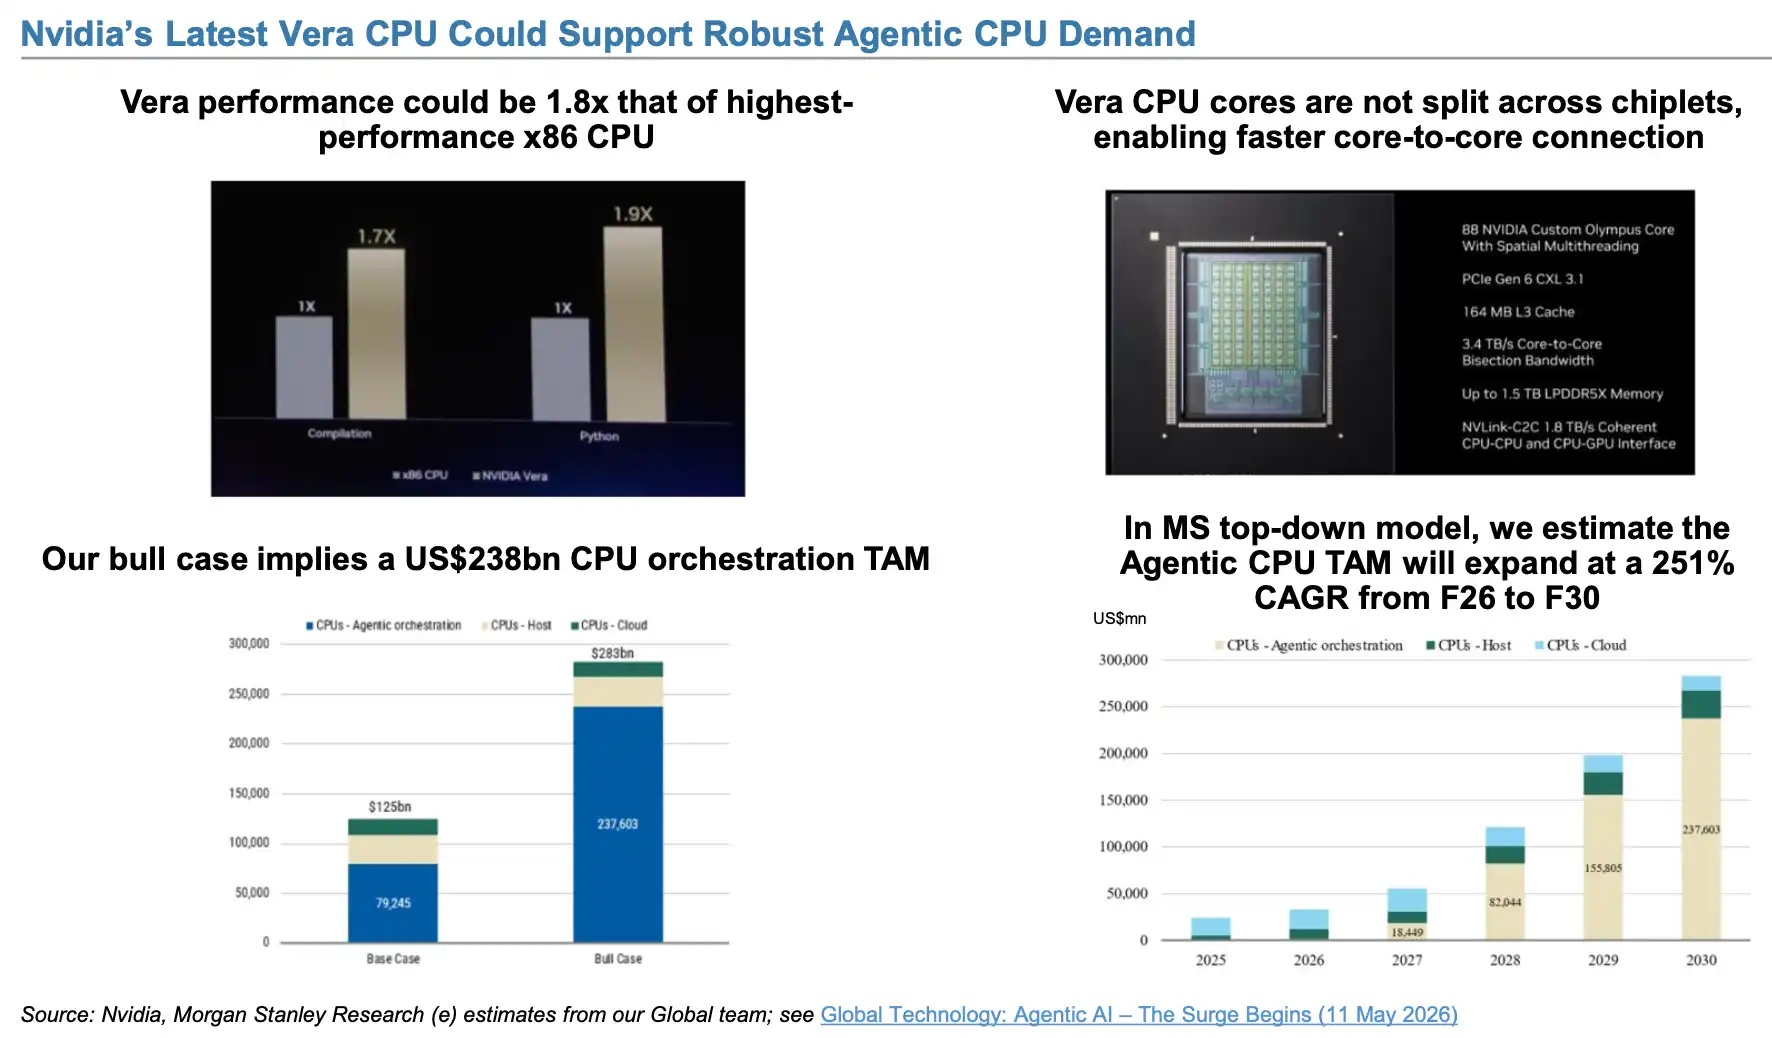
The share of AI semiconductors in TSMC's revenue is rising steadily, potentially exceeding 30% in 2026.
The underlying logic is straightforward.
AI chips are not only increasing in quantity but also becoming individually "more expensive." Moving from 5nm to 3nm and 2nm, from standard packaging to CoWoS and SoIC, and adding more HBM, each generation of AI accelerators increases the wafer, packaging, and memory value per chip.
Therefore, even if server volume growth gradually slows, the semiconductor value per machine could continue to rise. This explains why advanced packaging growth can significantly outpace overall capex.
At the same time, the sources of AI chip growth are diversifying from NVIDIA to custom ASICs.
Morgan Stanley argues that even as NVIDIA continues to release more powerful GPUs, large CSPs still need their own custom chips. Google has TPUs, Amazon has Trainium, and companies like Meta are advancing their own ASIC projects.
When a cloud provider has sufficiently large compute demands, self-developed ASICs can optimize cost, performance, and energy efficiency around specific workloads, while reducing reliance on a single GPU supplier.
Thus, the future AI chip market is less about "who takes over after NVIDIA's growth ends" and more likely about GPUs continuing to grow while ASICs become a second growth curve.
Morgan Stanley estimates that Alchip's revenue from AWS Trainium could rise from ~$1.8 billion in 2026 to $2.8 billion in 2027, reaching $8 billion in 2028, at which point Trainium revenue would account for ~82% of Alchip's total revenue.
Forecasts for Google TPUs are even more aggressive.
Under the report's model, MediaTek's TPU-related revenue could surge from $13.5 billion in 2027 to $43.5 billion in 2028, further reaching $70 billion in 2029; TPU revenue may already represent ~65% of MediaTek's total revenue in 2028.
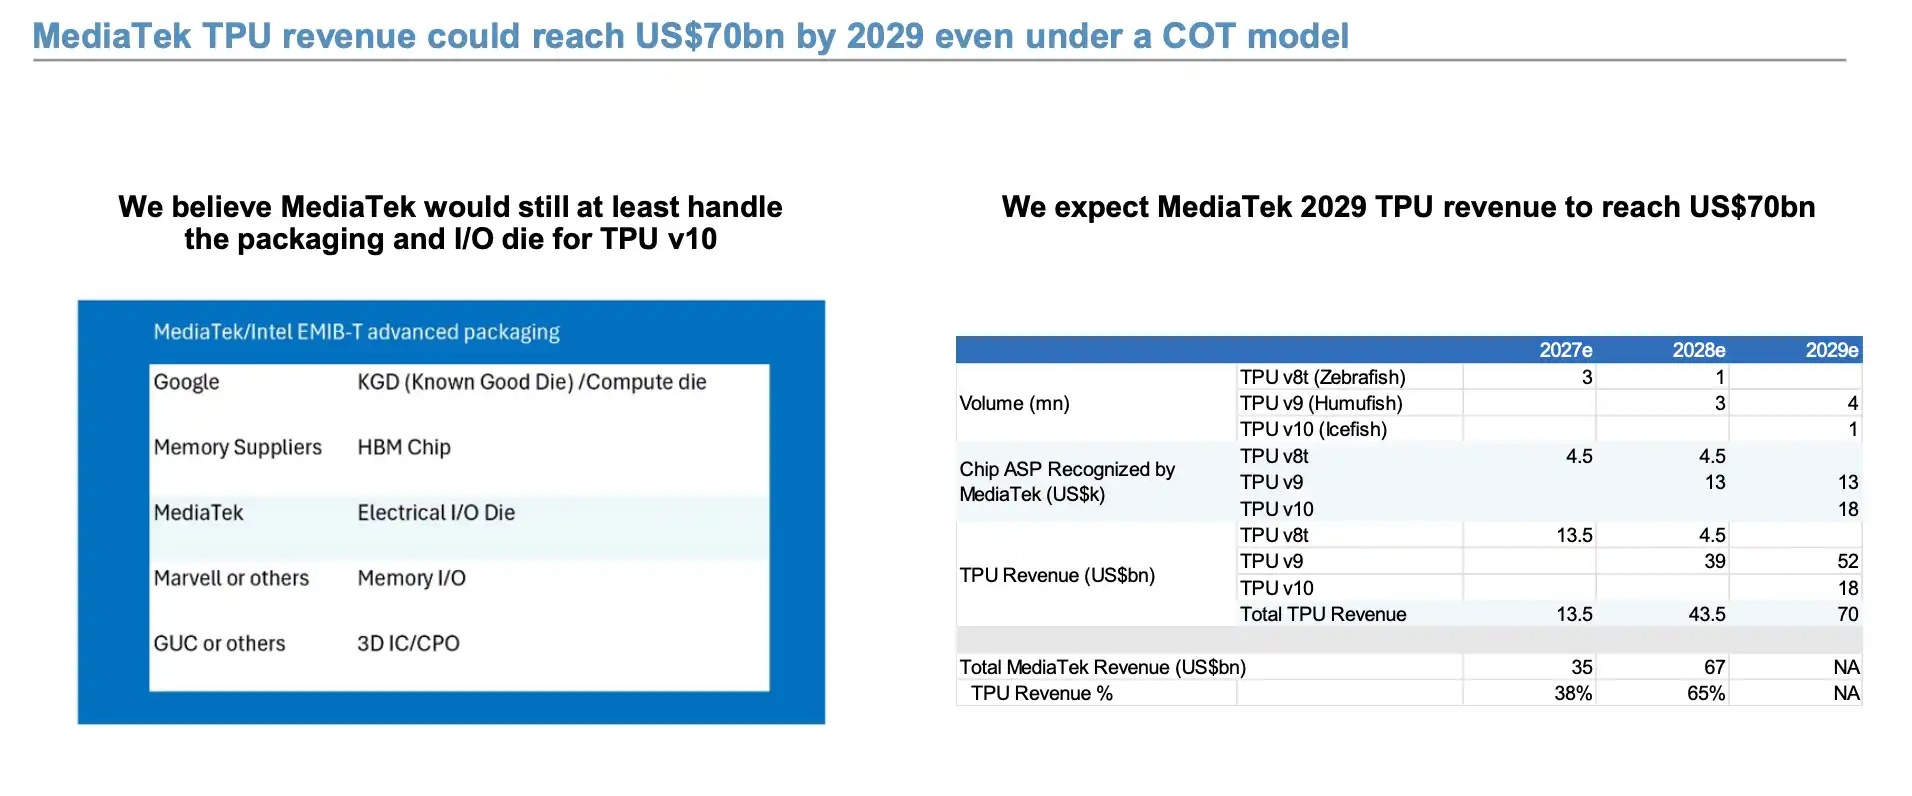
Morgan Stanley expects continued expansion of CSP self-developed ASIC projects, with custom chips like Google TPUs entering rapid volume ramp-up phases.
These figures are all forward-looking models; the extent of realization ultimately depends on chip mass production, yield rates, customer procurement, and the CSPs' own capex. But the direction is clear: AI supply chain growth is expanding beyond mere GPU shipments to include ASICs, advanced nodes, advanced packaging, ABF substrates, and chip testing.
The report specifically notes that Google TPU's potential for further volume ramp-up could be constrained by ABF substrate supply. Therefore, when assessing the AI cycle, "how many GPUs are sold" remains important, but it is increasingly not the whole picture.
China's AI demand is picking up, but the real bottleneck remains capacity
The Chinese market presents a different dynamic.
Past discussions on domestic AI chips focused mainly on "import substitution." However, Morgan Stanley now places greater emphasis on demand creation.
The report suggests that DeepSeek demonstrates lower-cost AI inference capabilities, which could further stimulate inference demand; meanwhile, China's local wafer manufacturing supply chain is improving its capabilities in AI GPU production.
This means the logic for Chinese AI chips is evolving from simple "import substitution" to: lower inference costs → increased applications → expanded compute demand → rising demand for local chips.
Consequently, Morgan Stanley highlights Iluvatar, Cambricon, Hygon, NAURA, and AMEC in its China AI and semiconductor equipment outlook, while also including SMIC in its AI overweight basket.
However, demand is not the current primary constraint. In summarizing key bottlenecks for global AI development, the report characterizes the US issue as Energy, while China's is Chip Capacity. That is, the volume of Chinese AI chips ultimately released depends more on how much effective capacity can be unlocked through advanced nodes, advanced packaging, and memory.
Memory is the most typical example.
Morgan Stanley projects that global DRAM capacity could reach ~3374 kwpm by 2028, with CXMT contributing ~500 kwpm (~15% of global total); CXMT's bit shipment is expected to achieve a ~40% CAGR from 2025 to 2028.
Meanwhile, CXMT is also entering the HBM market.
The report estimates its HBM TSV capacity could rise from 20 kwpm in 2026 to 40 kwpm in 2027 and 70 kwpm in 2028. Based on bit shipment calculations, CXMT could hold ~3.8% of the global HBM market in 2026 and ~4.4% in 2027.
Yet this does not immediately alter the global memory tightness landscape.
Even factoring in CXMT's new capacity, Morgan Stanley's model shows a global DRAM supply-demand gap of ~17% in 2026 and ~15% in 2027; the HBM market remains in a state of shortage.
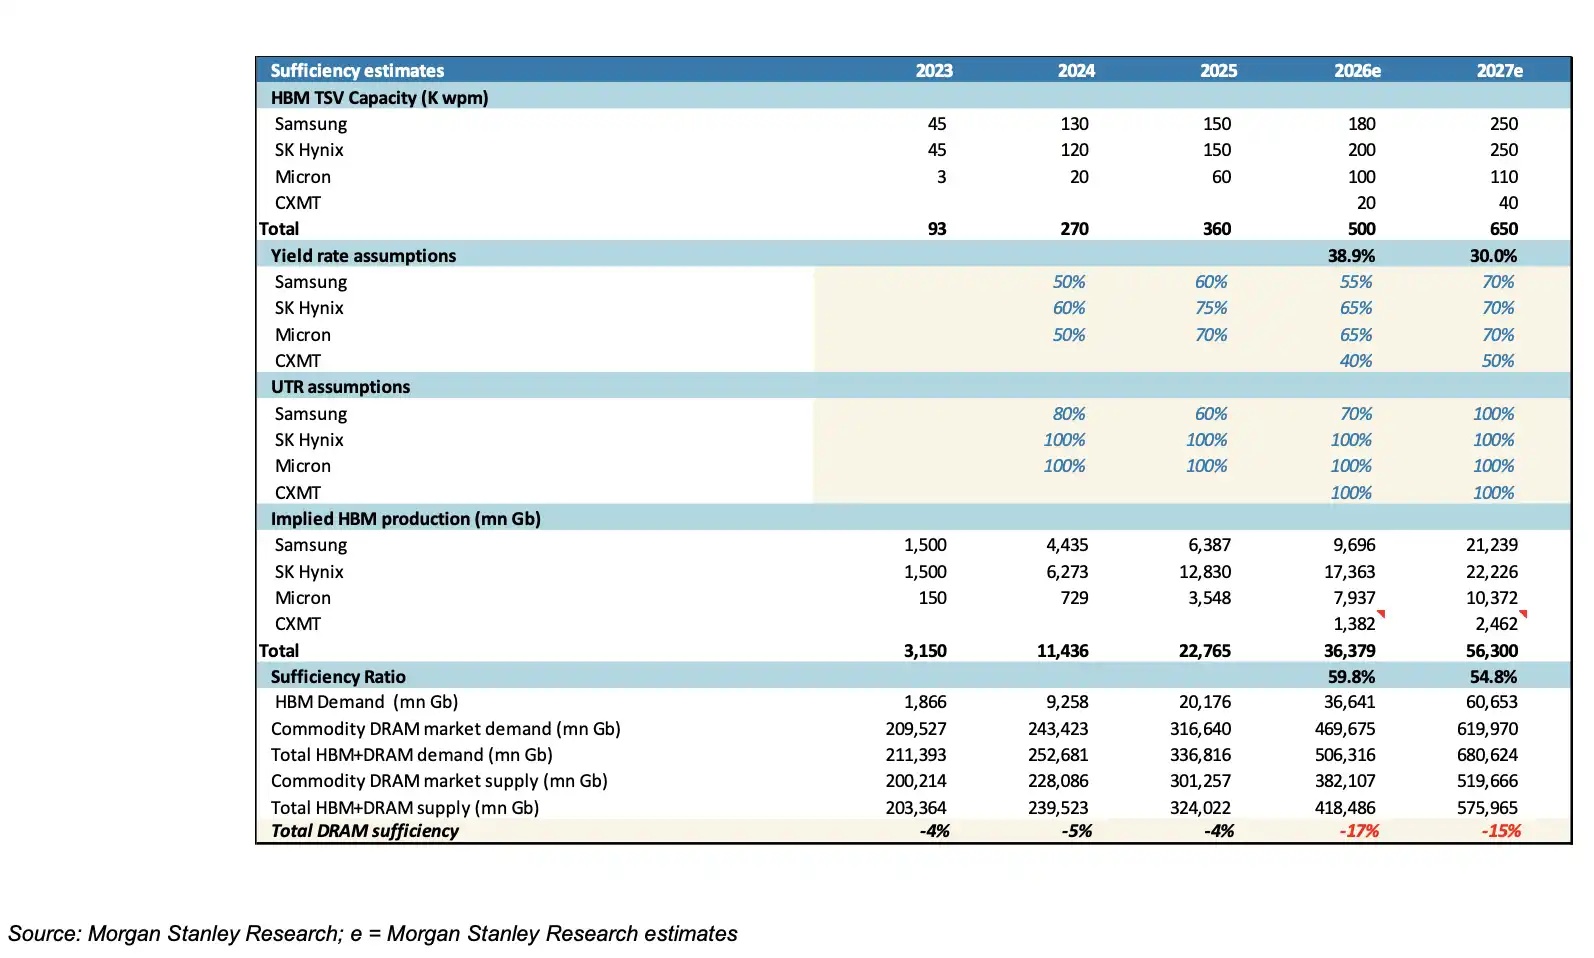
CXMT's DRAM and HBM capacity is expanding rapidly, but Morgan Stanley expects global memory supply to struggle keeping pace with AI demand growth.
This is one of the biggest differences between this memory cycle and previous ones.
Previously, DRAM and NAND behaved like typical PC/mobile phone cycle goods: demand rises, prices increase, manufacturers expand capacity, followed by oversupply. But in AI servers, HBM, server DRAM, and high-performance storage are increasingly acting as infrastructure bottleneck assets. They are no longer just ancillary components next to GPUs; they directly determine whether an AI server can be produced and whether an entire compute cluster can expand as planned.
Ultimately, what this 61-page report aims to convey is not simply "AI will keep rising." A more accurate statement is: AI semiconductors are moving from Phase 1, dependent on high-growth CSP capex, to Phase 2, driven by rising AI share and increasing value per unit.
Therefore, judging whether the AI hardware cycle is truly nearing an inflection point based solely on the capex growth rates of Meta, Google, Microsoft, and Amazon is insufficient.
More worthy of observation are the AI capex share, CoWoS/EMIB capacity, HBM supply/demand, 2nm utilization rates, and the actual shipment pace of ASICs like Google TPUs and AWS Trainium.
If overall CSP capex growth declines in the future, but these indicators remain strong, AI semiconductor prosperity may not peak alongside total capex. Conversely, only when these core metrics simultaneously weaken does it signal a true inflection point for the AI semiconductor cycle.


The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.