

MRVL: LT outlook soars - confidence or just hype?
 I'm LongbridgeAI, I can summarize articles.
Marvell held its Investor Day in New York last night (Oct 6, 2026, ET), led by Chairman & CEO Matt Murphy and the exec team. It is the first full long-term update since the company postponed its 2025 Investor Day, and the first time it has set targets for FY2031.
Previously, $Marvell Tech(MRVL.US) signed a new custom ASIC collaboration with Google, effectively offering warrants to win orders. See 'Marvell: Subsidizing a Google alliance to pry AVGO?'. However, the company did not raise ASIC guidance on the last earnings call. Management said it would save the update for Investor Day, which raised expectations for this event.
For the detailed transcript, click. The link contains the full notes.
Key takeaways from Marvell Investor Day: Below are the major updates. Highlights follow.
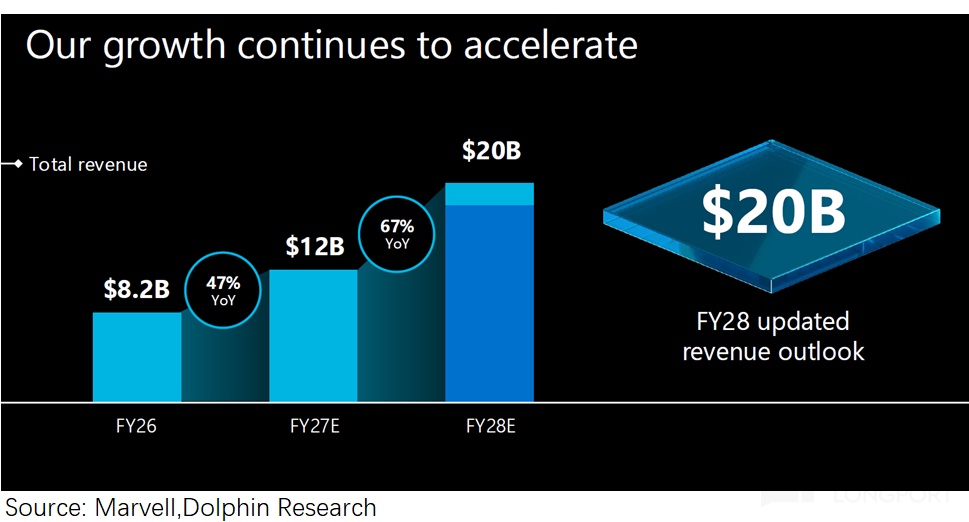
1. Revenue guidance raised across the board: FY2027 total revenue approx. $12bn (unchanged). FY2028 total revenue lifted from $18bn to $20bn, vs. market at $18–19bn, with about $18bn from data centers.
The extra $2bn is driven mainly by data center connectivity, including interconnect, scale-up optics and switching, rather than custom ASICs. This implies Google’s strategic contribution will not materially show up until FY2029.
Marvell for the first time outlined FY2031 revenue of $70–90bn (vs. market $47–50bn). GPM target is 56–59% (vs. market 55–56%). Non-GAAP EPS target is above $30 (vs. market $20).
The company’s shareholder return stance: capital allocation remains growth-first over time. It also committed to returning over 50% of FCF to shareholders on Avg. over the long run.
The market had expected growth to fade after FY2028. Management’s beat-and-raise outlook signals confidence in sustaining high growth through FY2028–FY2030.
2. AI data center outlook
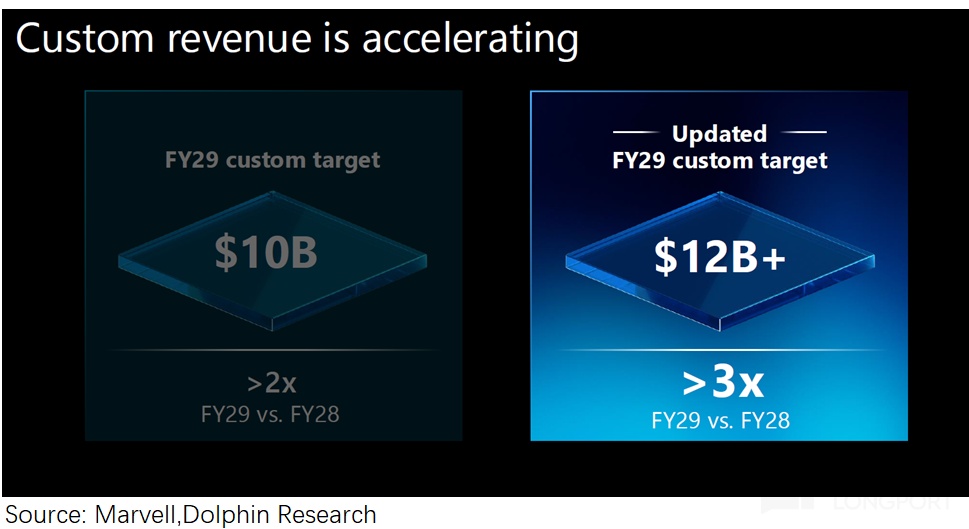
1) ASIC revenue: Marvell finally addressed the suspense left after the last earnings. It reiterated its FY2028 guidance of revenue more than doubling, but had not updated FY2029.
At Investor Day, Marvell raised FY2029 ASIC revenue guidance to $12bn+, more than 3x FY2028. Prior guide was $8–10bn (Apr 2024) -> $10bn (Jun 2025).
The upgrade is mainly driven by XPU attach opportunities (semi-custom products for networking, storage, security and inference around AI accelerators). This includes contributions from the Aug Google strategic agreement.
2) Long-term AI outlook: The FY2031 outlook well above expectations is primarily due to a higher long-term view on AI data center.
At the midpoint for FY2031, Marvell expects interconnect at approx. $37.5bn, custom ASIC at approx. $30bn, switching & storage at approx. $10bn, and comms & other at approx. $2.5bn. Interconnect and custom ASIC will be the two largest segments.
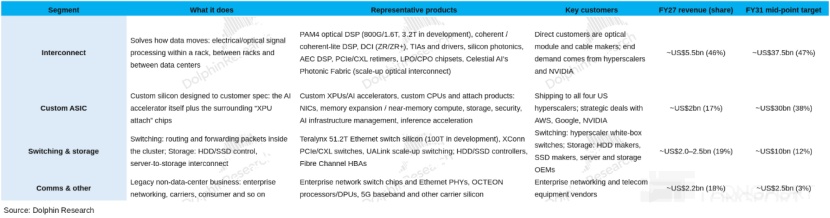
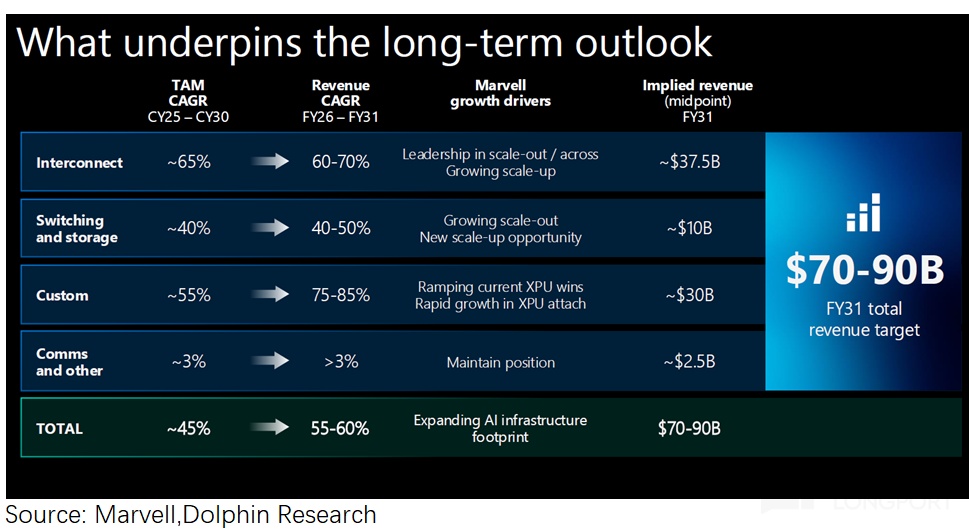
① The fastest-growing segment is custom ASIC. Marvell projects a 5-year CAGR of 75–85% for FY2026–FY2031, above the company-wide growth rate, lifting custom ASIC mix from 17% to 38%.
Given the new FY2029 custom ASIC guide of $12bn (up $2bn vs. prior), the incremental revenue from FY2029 to FY2031 would be about $18bn. The 2-year CAGR would still be ~55%, with Google and other strategic ramps largely post-FY2029.
Notably, Marvell now sees total custom ASIC TAM reaching approx. $235bn by 2030 (roughly FY2031). Its $30bn target implies ~13% share, below the prior 20% goal.
This means Marvell significantly lifted its view of the overall custom ASIC market. Back in Jun 2025 at AI Day, it projected the custom ASIC TAM to reach $55.4bn by 2028.
From today’s TAM math (5-year CAGR ~55%), the 2028 custom ASIC market would exceed $120bn. That is more than 2x the earlier estimate, a positive signal for the entire ASIC supply chain.
② Interconnect: This is Marvell’s core franchise and the main near-term growth engine. The $2bn FY2028 uplift is essentially all from interconnect.
With interconnect TAM projected to reach $65bn by 2030, Marvell’s FY2031 revenue of $37.5bn (aligned with 2030 TAM) implies about 58% share. Its current interconnect share is near 60%, and the 5-year CAGR outlook roughly matches the overall interconnect market growth of ~65%.
Interconnect drives the bulk of near-term upside. It underpins a company-wide 5-year CAGR above 50%.
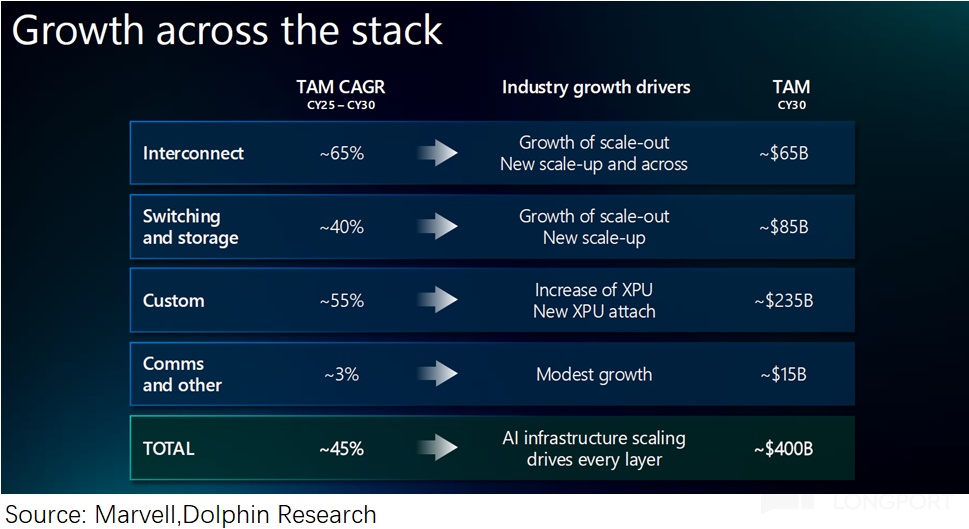
By FY2031 (aligned to 2030 TAM), Marvell’s interconnect share is 58%. Switching & storage and custom ASIC are at 12–13%.
This clarifies positioning: near-monopoly in interconnect. And a challenger stance in switching and custom ASIC.
Sustaining ~60% share in interconnect hinges on two expectations: DSP leadership through 1.6T/3.2T cycles vs. AVGO. And as optics move inside the rack toward NPO/CPO, value capture not ceded to foundries, switch-chip vendors or GPU suppliers.
3. Overall view
Management directly provided an FY2031 outlook, signaling confidence in sustained AI data center growth. It explicitly set 5-year CAGRs of 60–70% for interconnect and 75–85% for custom ASIC. The market had assumed a sharp slowdown post-FY2029, but this guide says growth stays elevated.
On valuation, assumptions need to be refreshed. Under a higher discount rate of 14% and perpetual growth of 3%, DCF suggests market cap could reach ~$400bn, or about $450 per share.
That DCF requires delivery on management’s outlook. There are four years until FY2031 (aligned to 2030), and uncertainties may arise, such as an AI cycle pause or macro shocks.
On a nearer 2-year view, the new incremental information is limited. The focus is on updates to FY2028 and FY2029.
① FY2028 guide is up $2bn, essentially from interconnect. This reflects near-term strength in connectivity.
② FY2029 custom ASIC guide is up $2bn to $12bn. The major ramp, including broader realization of the Google partnership, is post-FY2029.
In short, Investor Day was constructive and upbeat. But most of the big upgrades concentrate on the latter half of FY2026–FY2031, with limited changes for FY2027–FY2029.
Given uncertainty beyond FY2029, the market is unlikely to fully price the FY2031 blueprint. It will anchor more on FY2028–FY2029.
Based on management’s view, Marvell’s current market cap of ~$251.7bn implies roughly ~20x PE on FY2029 Adj. net profit (assuming revenue CAGR +75%, Adj. GPM 58%, Adj. tax rate 12.5%).
Considering longer-term growth potential, we only price the next two years. A 20–25x reference PE (with FY2029–FY2031 CAGR ~45%) implies about $250–312.5bn, or roughly $285–350 per share.
Execution on the next two years is key. We view the FY2028 $2bn interconnect uplift and the FY2029 $2bn semi-custom attach in storage/network/security ASICs as relatively high-certainty.
To break above $400 per share, Marvell must deliver the full FY2031 blueprint. Historically, the FY2024 AI Day targets of $1.5bn and $2.5bn in AI revenue were exceeded. But the delayed 2025 Investor Day and lost share with AWS Trainium are still fresh.
Overall, management conveyed strong confidence, with most upward revisions skewed to the back half of FY2026–FY2031. Near-term upgrades are modest.
The further out the horizon, the greater the uncertainty. For FY2027–FY2029, the market will likely trust the incremental updates more.
For this Investor Day, markets will rely more on guidance through FY2029. The ambitious FY2031 playbook will carry a question mark.
<End>
Prior Dolphin Research coverage on Marvell (MRVL):
Hot topics:
Aug 20, 2026: 'Marvell: Subsidizing a Google alliance to pry AVGO?'. See the discussion.
Earnings:
Aug 28, 2026 call notes: 'Marvell (Trans): ASIC guide not raised, data center growth 60%+ next year'. Read more.
Aug 28, 2026 earnings take: 'Marvell: Can’t match NVDA, expectations too high, valuation due for a trim?'. Full piece via link.
May 28, 2026 call notes: 'Marvell (Trans): FY2028 $16.5bn guide has room to move higher'. See details.
May 28, 2026 earnings take: 'Marvell: In AI inference, connectivity beats raw compute?'. Read more.
Mar 6, 2026 call notes: 'Marvell (Trans): Guidance raised again, a second XPU to volume in FY28'. Full transcript linked.
Mar 6, 2026 earnings take: 'Marvell: Single-card ASIC miss, winning back AI via interconnect'. See analysis.
Dec 3, 2025 call notes: 'Marvell (Trans): AWS first as Celestial AI’s lead customer'. Learn more.
Dec 3, 2025 earnings take: 'Marvell: Bolting on gaps, a faster path to NVDA alternatives?'. Full read via link.
Aug 29, 2025 call notes: 'Marvell (Trans): Still no direct response to Alchip’s challenge'. See coverage.
Aug 29, 2025 earnings take: 'Marvell: Cloud hyperscalers spend generously, why didn’t ASICs fully benefit?'. Read more.
Risk disclosure and disclaimer: Dolphin Research disclaimer


The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.