D
 +12
PLTR: Guidance keeps ramping, yet new contracts become a target for 'nitpicking'?
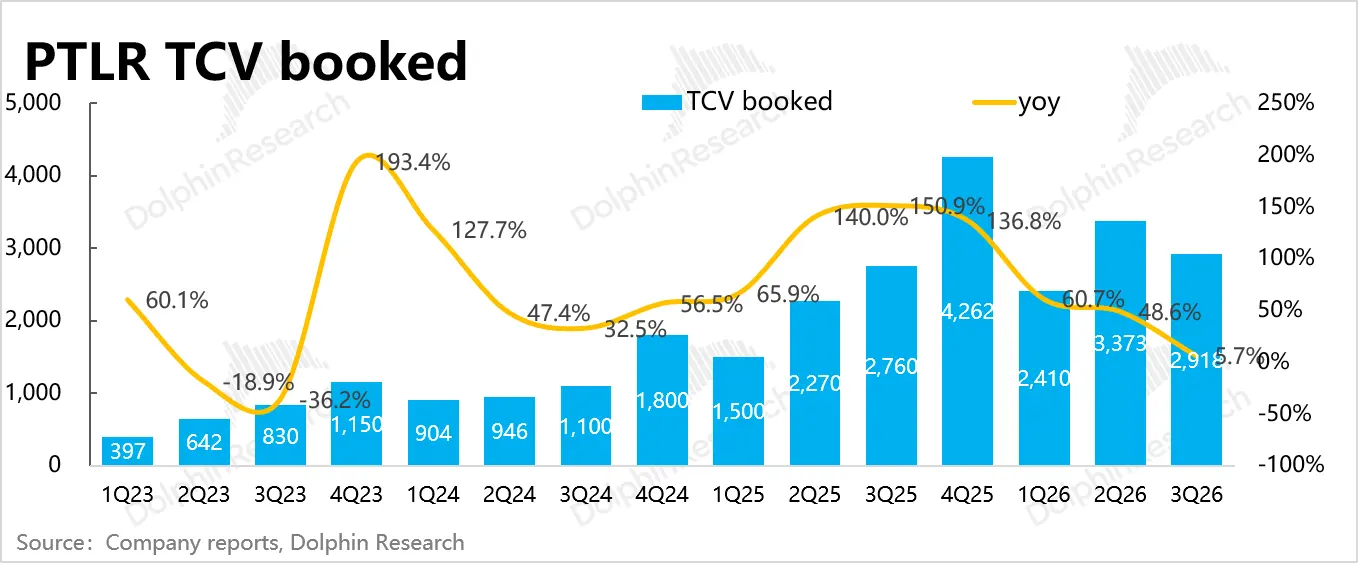
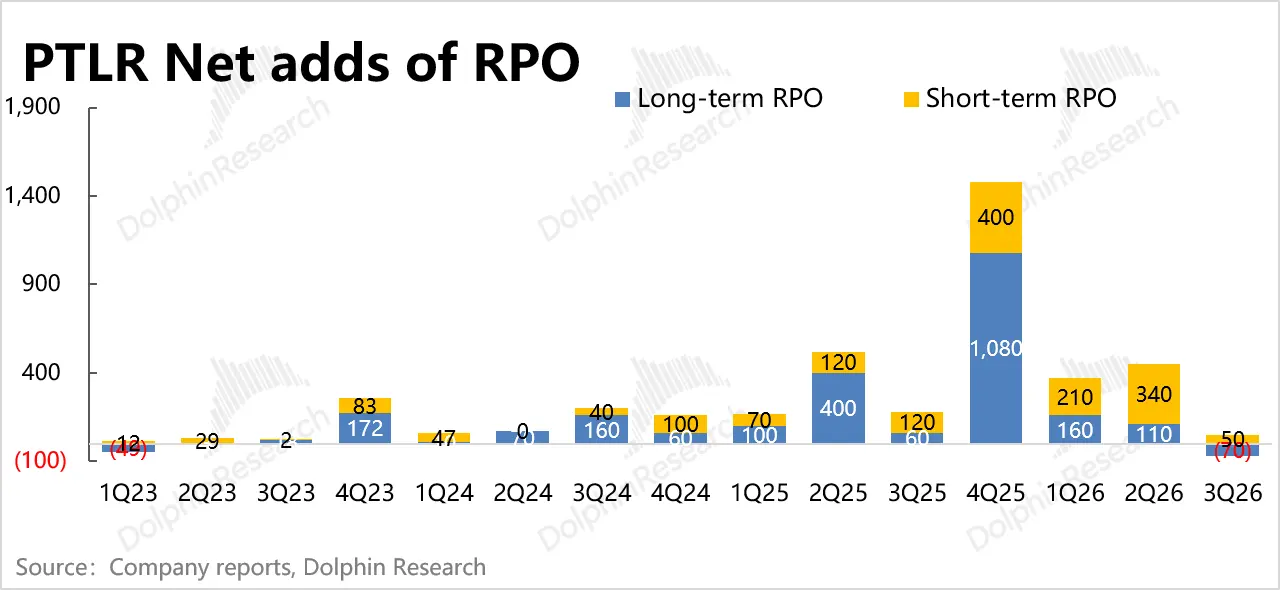
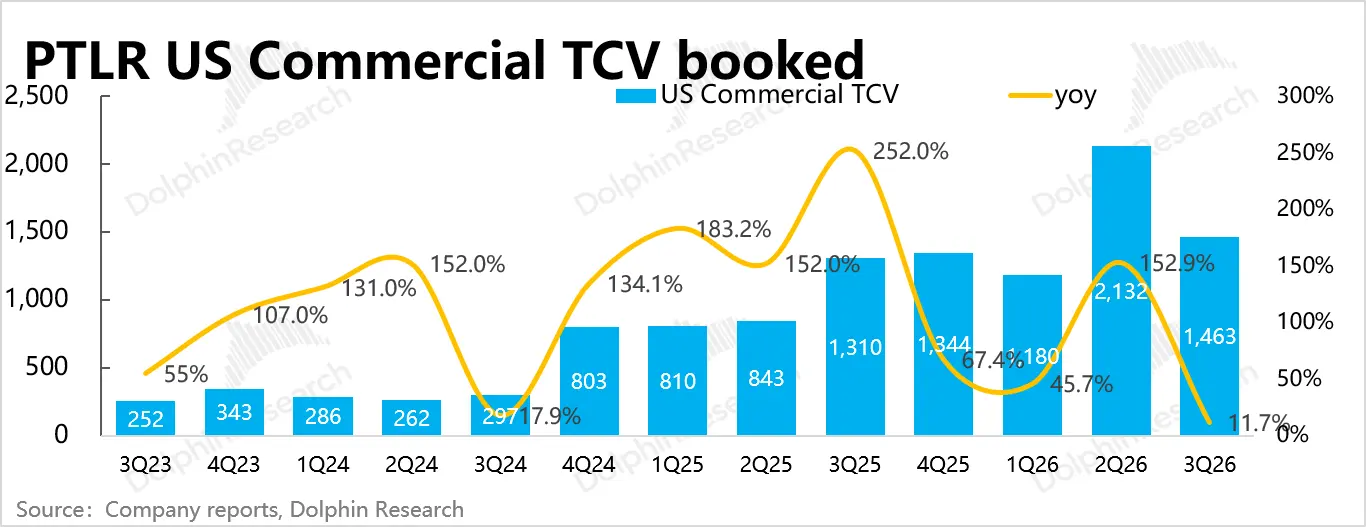
Guidance looks strong, but orders are soft. With results only in line, the print is unlikely to trigger a positive stock reaction.
+12
Guidance looks strong, but orders are soft. With results only in line, the print is unlikely to trigger a positive stock reaction.
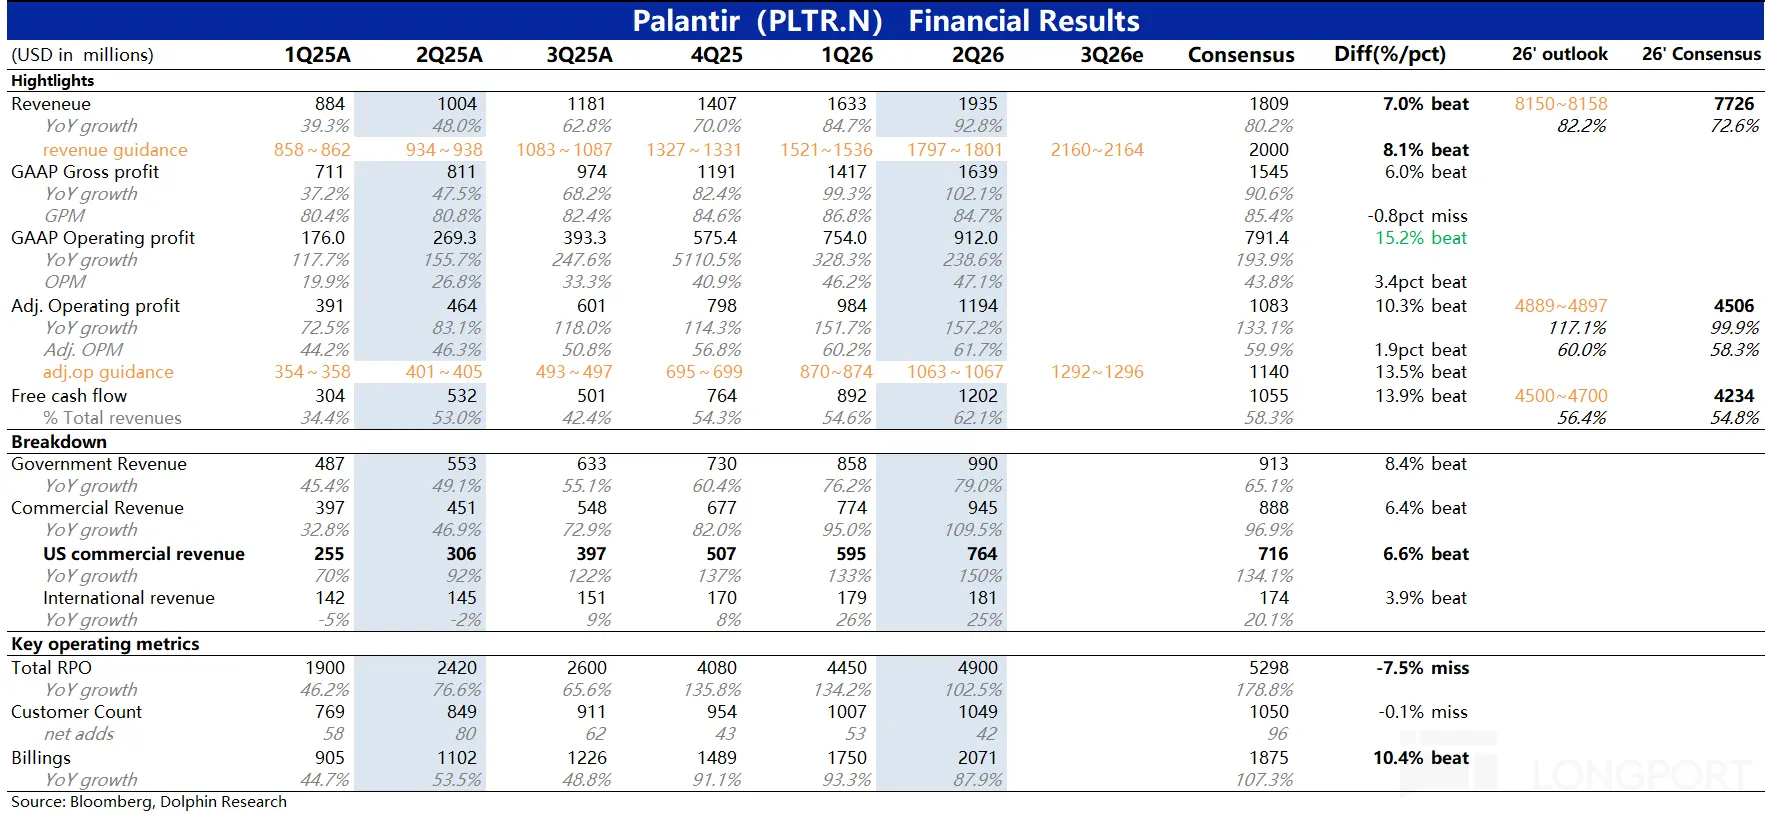
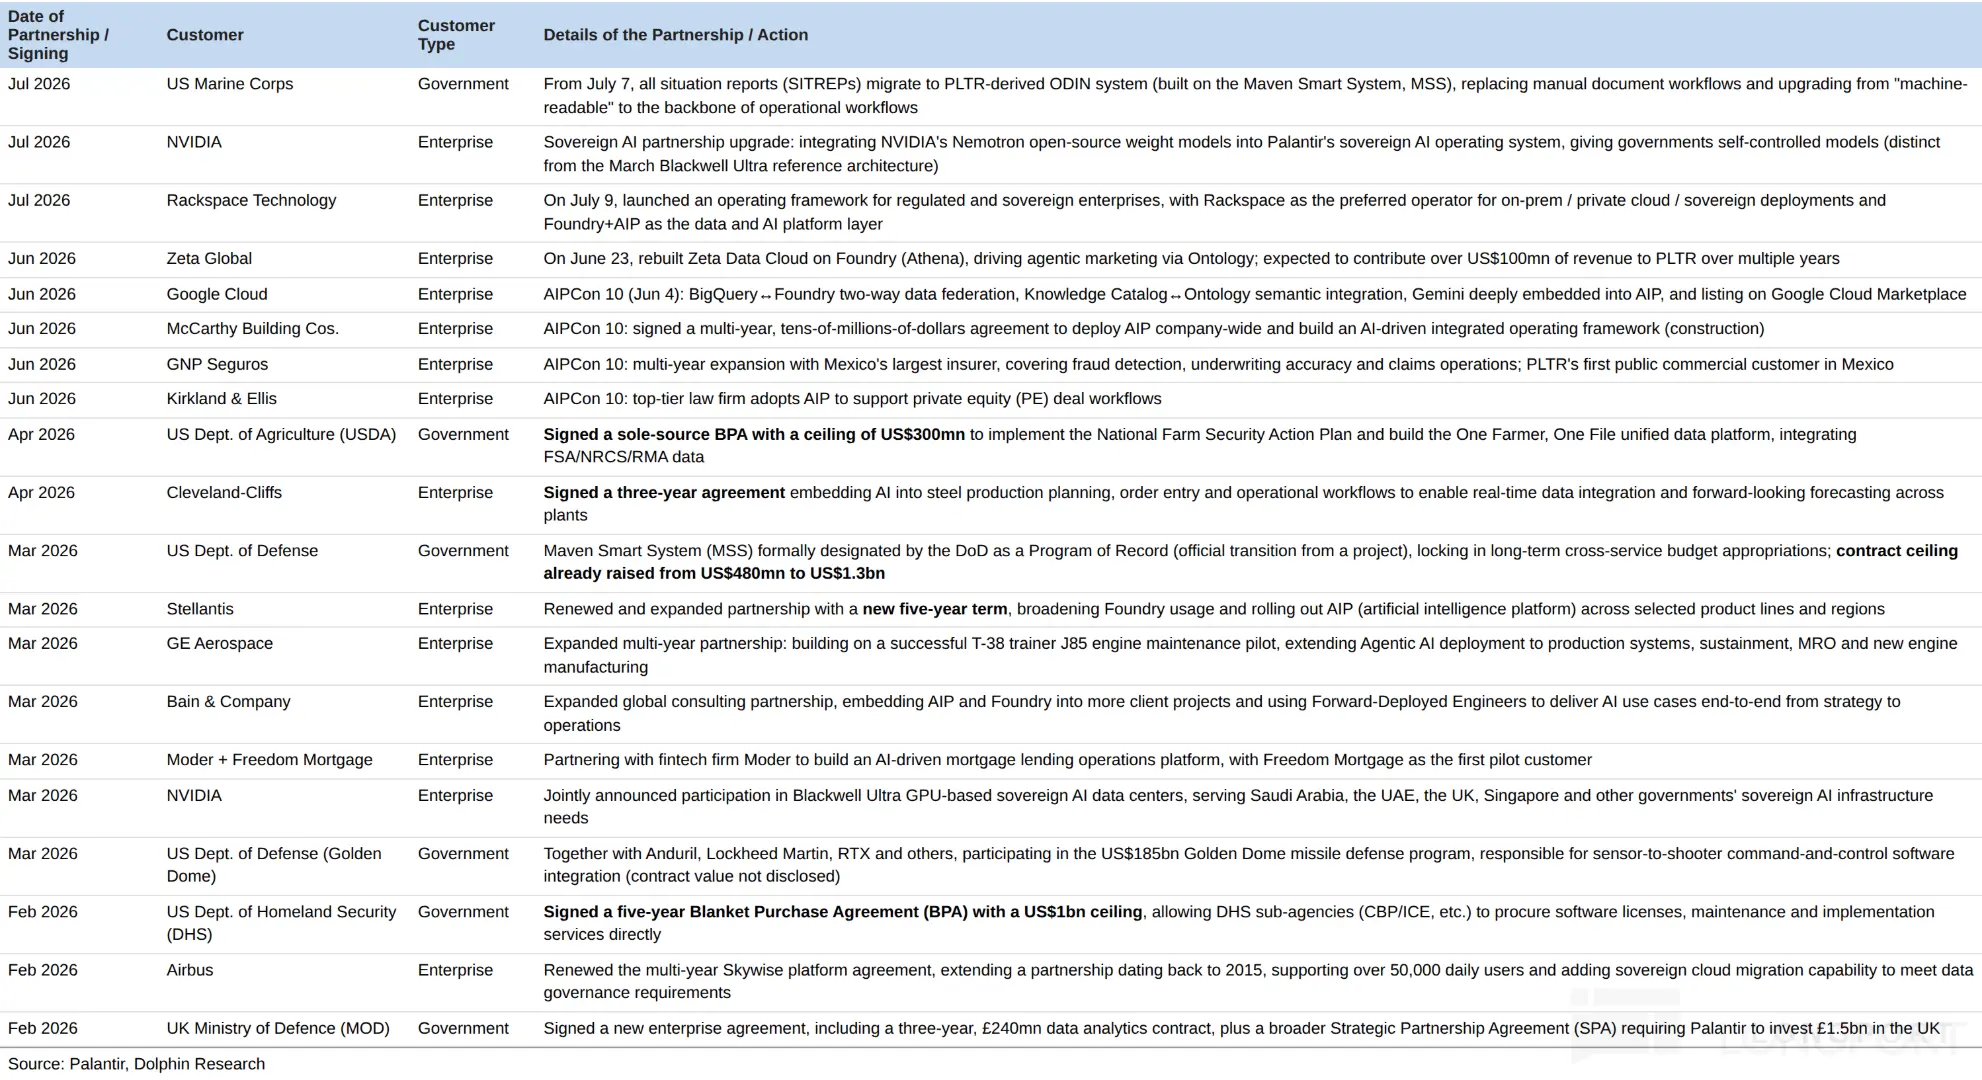
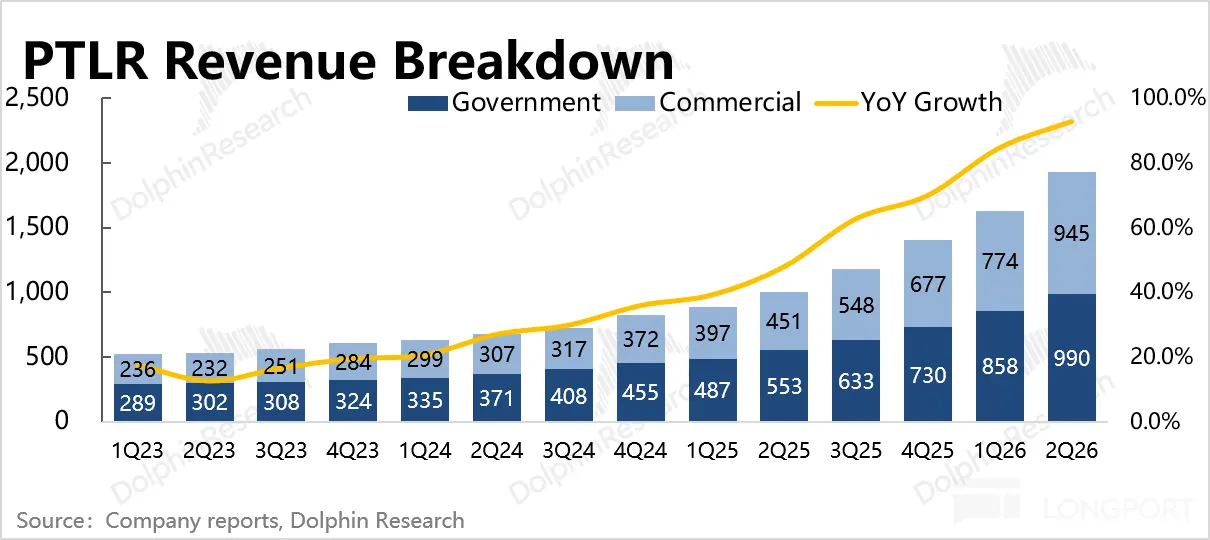
+12$Palantir Tech(PLTR.US) Q2 results offset the Q1 soft patch in US commercial revenue growth and kept momentum accelerating. With both recognized revenue and backlog inflecting higher, the print squarely counters the narrative that foundation models such as Anthropic would displace the company.
Guidance was raised again. Q2 revenue growth accelerated to 93%, and management guides Q3 to ~83%. The FY revenue outlook is now over 8.1bn, implying +82% YoY, with adj. OP and FCF also lifted...
 +10
However, taking over cloud hosting for a government client pushed adj. GPM down to 86%, and Q3 will see a ramp in hiring and marketing spend. The company is betting its strategy on 'sovereign AI', partnering with NVIDIA to build in-house model fine-tuning and post-training capabilities.
Below is Dolphin Research's Trans of PLTR FY2026 Q1 earnings call. For the earnings analysis, cf. 'Palantir:软件末日论汹涌,最牛信仰股也松动了?'.
Section I: Core highlights recap.1) Guidance materially raised: FY2026 revenue midpoint lifted to $7.656bn (+71% YoY), up 10ppt vs. last quarter's guide, marking the largest full-year revenue guide raise in company history. Q2 revenue guide at $1.797–1.801bn...$Palantir Tech(PLTR.US) Q1 results were solid overall. While a run of strong prints has digested some of the valuation premium, two blemishes — softer-than-expected US commercial revenue and order volatility alongside a slower growth trajectory in the guide — together with the AI narrative, dampened near-term risk appetite and left the post-earnings reaction muted.
Specifically: 1) Guide raised, but growth set to slow? Q1 revenue continued to accelerate, up 85%.Mgmt. guides Q2 revenue growth of ~79%, and lifted FY revenue to over 7.6 bn (+71% YoY)...Below is Dolphin Research's compilation of Palantir's FY25 Q4 earnings call Trans.
For our detailed read, see 'Palantir: Another strong print — can the AI apps leader return to its peak?'I. Key metrics recap.
1) Overall performance: Q4 revenue surged 70% YoY, the fastest since listing. FY2025 revenue rose 56% YoY to $4.475bn.2) Profitability: Q4 Adj. OP was $798mn with OPM at 57%.
Full-year Adj. OP was $2.3bn...The following are the minutes of the FY25Q3 earnings call for $Palantir Tech(PLTR.US) organized by Dolphin Research. For earnings interpretation, please refer to "Palantir: Valuation Too Advanced, Backlash is Coming." 1. Review of Core Financial Data Total Revenue: $1.181 billion, up 63% year-over-year, up 18% quarter-over-quarter, reaching a historical high, far exceeding expectations. U.S. Market: Revenue of $883 million, up 77% year-over-year, up 20% quarter-over-quarter, accounting for three-quarters of total revenue. 40 Rule Score: Reached 114 points, up 20 points quarter-over-quarter, setting a historical record...
$Palantir Tech(PLTR.US) released its Q3 2025 earnings after the market closed on November 3rd, Eastern Time. Overall, the Q2 performance remains impressive. Although the guidance and operational indicators imply signs of slowing down, considering the management's consistently conservative guidance style and the short-term changes in the U.S. Department of Defense procurement process, the short-term disturbances are not a major issue. However, with a full valuation, the market will be more critical of Palantir. Reviewing past performance versus market reactions, it is not difficult to find that from the three quarters starting this year, as the valuation rises...
The following are the minutes of the FY25Q2 earnings call for $Palantir Tech(PLTR.US) organized by Dolphin Research. For an interpretation of the earnings report, please refer to "Palantir: Worthy of the AI Application Leader, Guidance Flaws Are Not an Issue." 1. Review of Core Financial Information a. 3Q25 Guidance: a. Revenue: $1.083-$1.087 billion (QoQ +8%+, YoY +50%), marking the highest historical QoQ growth guidance. b. Adjusted Operating Profit: $493-$497 million...
Palantir released its Q2 2025 earnings after the market closed on August 5th, Eastern Time. Overall, the Q2 performance remains impressive. Although the guidance suggests that the peak is near and a slowdown is imminent, the overall operational status is healthy, especially as some issues that appeared in Q1 have been largely resolved. Considering the current government's positive attitude towards AI and defense investments, as well as the still significant TAM in the ToB space, it is not impossible for future results to continue to beat guidance. Specifically, the core information from the financial report: 1. Strong demand from U.S. enterprises: The performance of ToB is the most critical...