Pop Mart

D
Dolphin Research

POP MART (Trans): Overseas stabilizing, returning to 'slow biz'

Overseas traffic stabilized across most markets in Q3. In China, Q4 is expected to trend modestly higher, with full-year growth staying positive.

However, total revenue declined 45%–50% YoY in Q3. In H2, GPM compressed by up to 200bps vs. H1 and the opex ratio increased.

The company is shifting focus toward the long term, emphasizing selective store openings. It is also building a multi-IP portfolio and strengthening membership operations.
图片 1,共 1 张
D
Dolphin Research

Pop Mart (Trans): FY growth of 20% is only a 'maybe'; buybacks to provide a floor.

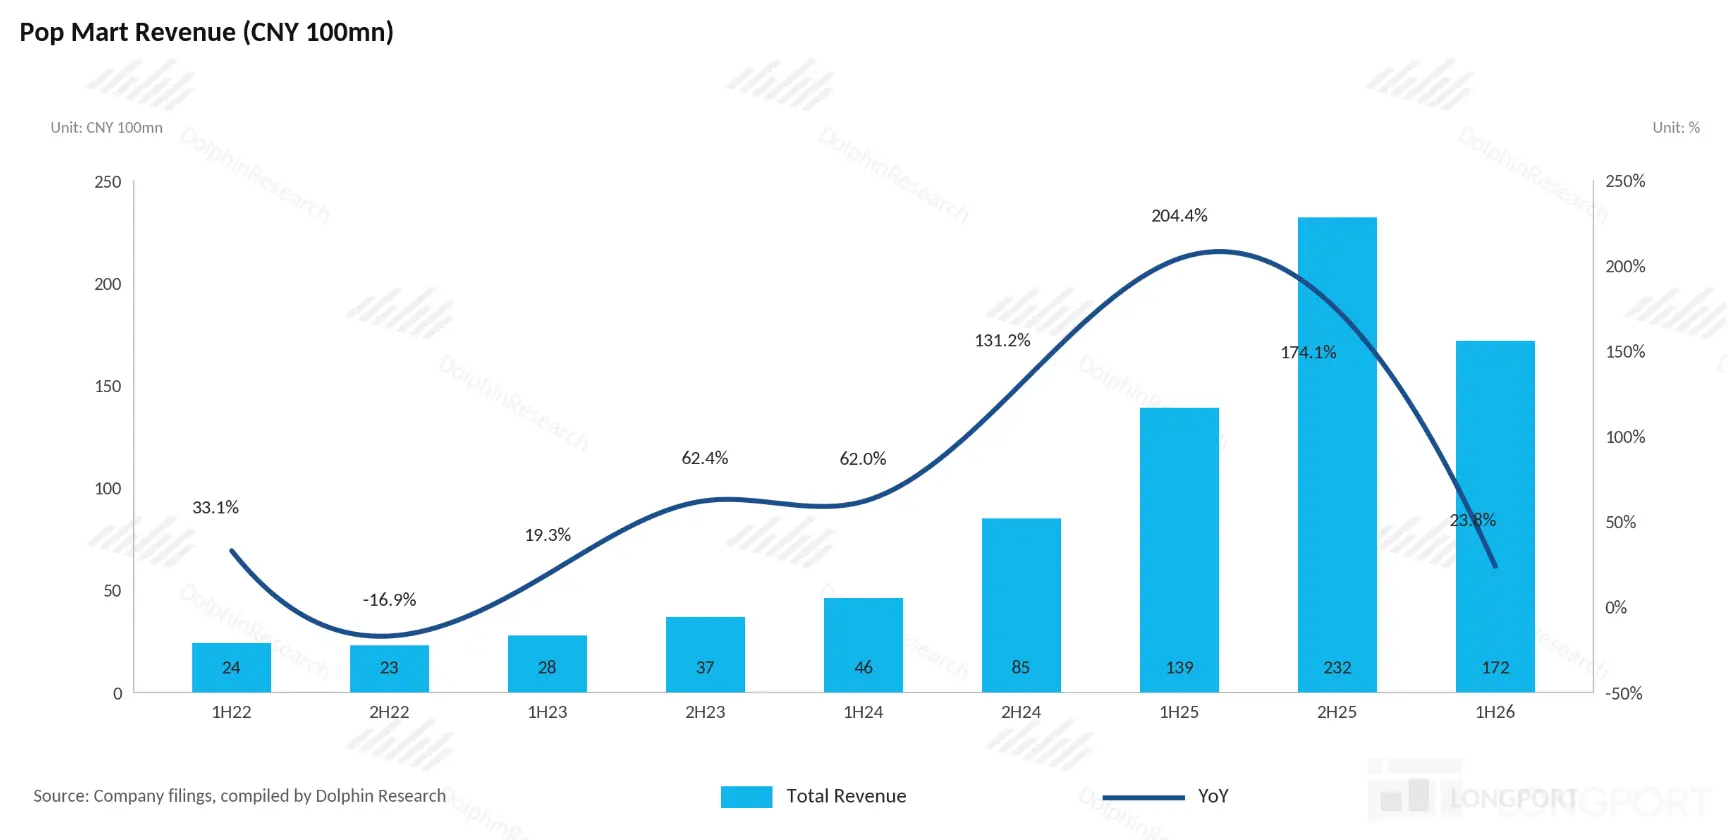
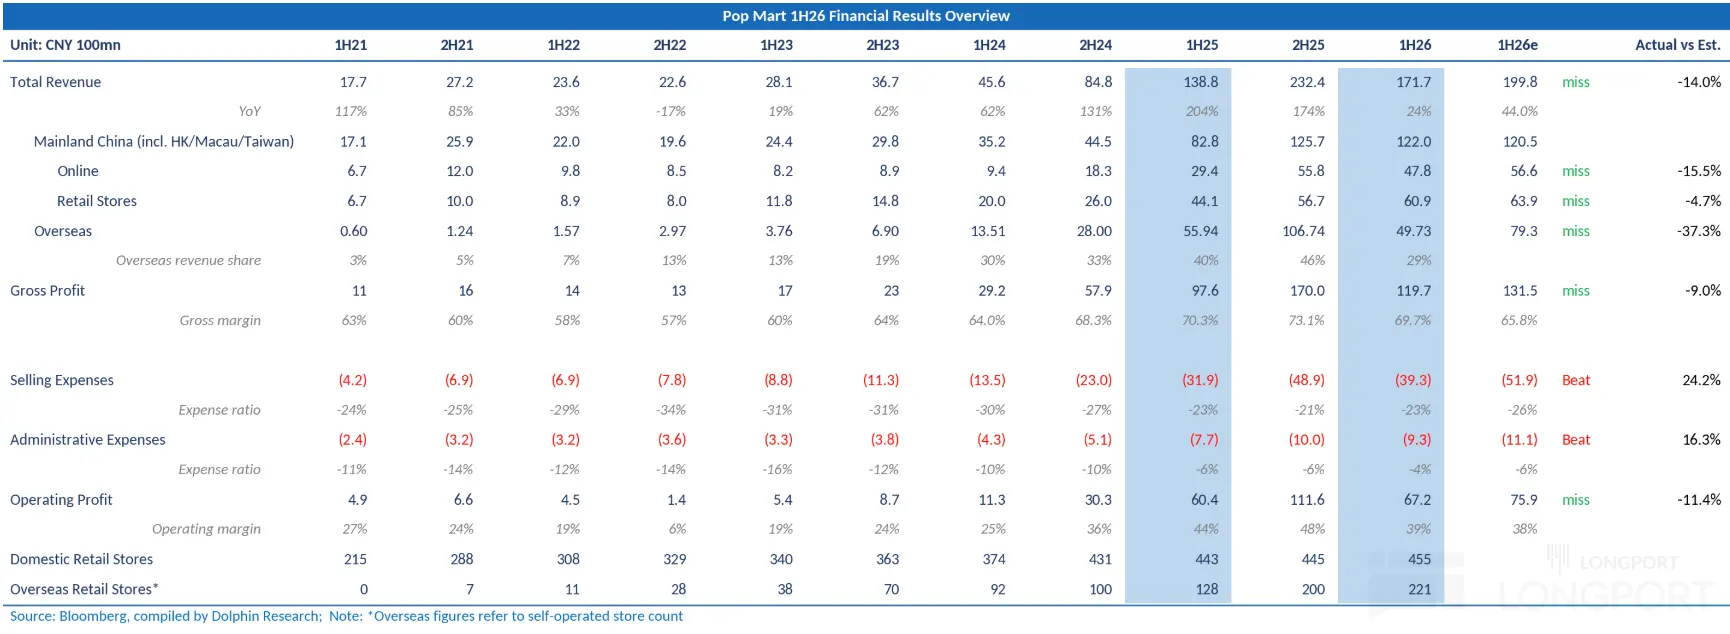
1H revenue was RMB 17.17bn (+23.8% YoY). The company also announced a RMB 2–5bn buyback over the next six months.

Overseas revenue fell 11% YoY. Margin contracted to 29.7% from 33.7%.

Management flagged greater pressure in 2H than 1H, noting the full-year 20% growth target is only 'maybe achievable'. It also designated 2026 as a reset year, shifting focus to org., inventory and infrastructure.

图片 1,共 1 张
D
Dolphin Research

POP MART (Trans): 2026 'pit stop to refuel and change tires'

Below is Dolphin Research's Trans of the FY25 earnings call for $POP MART(09992.HK). This section provides a recap of the core takeaways.

1) Shareholder returns: the company plans to distribute 25% of net income attributable to shareholders as dividends. This implies a total payout of RMB 3.194bn and DPS of RMB 2.38.

2) Guidance: for 2026, management targets revenue growth of at least 20%, prioritizing healthy, sustainable growth over aggressive expansion. It aims to avoid revenue growth without profit. The company will add quarterly business updates in May and Nov to increase disclosure frequency...

图片 1,共 2 张
Pop Mart 2H25 Financial Data Overview Unit: CNY 100M 1H21 2H21 1H22 2H22 1H23 2H
D
Dolphin Research

Pop Mart: The sewing machine is "smoking", can the bubble continue to soar?

On the evening of August 19th, Beijing time, Pop Mart (9992.HK) released its H1 2025 performance report. Both revenue and profit exceeded the levels of the entire previous year, making it a commendable report. Compared to the recently announced earnings forecast, the revenue remained stable, with a key highlight being the nearly 400% year-on-year increase in profit (the forecast indicated no less than 350%), surpassing market expectations.

III to ligit inp on n  ving
泡泡玛特财务数据概览 单位:亿/CNY 1H21 2H21 1H22 2H22 1H23 2H23 1H24 2H24 1H25 1H25e 实际v vs预期
泡泡玛特收入 (亿元) 单位:亿元 单位:% 160 250% 140 海豚投研 DolphinResearch DolphinResearch Dolphin
60 单位:亿元 50 海豚投研 40 DolphinResearch 泡泡玛特海外营收&占比变化 30 20 10 0 3% 海豚投研 DolphinRese+14
D
Dolphin Research

Pop Mart: Great Success on Global Business! Is Pop Mart on a "crazy ride"?

On the afternoon of March 26th, Beijing time, Pop Mart (9992.HK) released its performance for H2 2024. Overall, the performance is quite good, with overseas operations continuing the high growth momentum from Q3 and maintaining a strong surge. Domestic offline stores have also accelerated compared to Q3. The gross profit margin has reached a historical high due to the improvement in product structure and the increased proportion of high-margin overseas business. The expenditure on expenses has been relatively restrained, and ultimately, the profit has exceeded market expectations

图片 1,共 23 张
图片 2,共 23 张
图片 3,共 23 张
图片 4,共 23 张+19
D
Dolphin Research

Pop Mart: Overseas explosive growth, this "bubble" cannot be burst

Papet Mart (2): Overseas "Surge", this "Bubble" cannot be broken. In the previous article, Dolphin focused on the comeback of the soul weapon - the diversification of IP monetization, and this section is still a continuing story. This article will focus on another lever it has propped up - the overseas market, discussing the following questions: 1. How did Papet Mart achieve reckless growth overseas? 2. How many more Papet Marts will be recreated overseas? 3. After five times in half a year...

图片 1,共 24 张
图片 2,共 24 张
图片 3,共 24 张
图片 4,共 24 张+20