D
 +4
Q1 Turnaround! Is APP's Core Gaming Biz. Still Solid?
Gaming is recovering. E-commerce is still early.
+4
Gaming is recovering. E-commerce is still early.
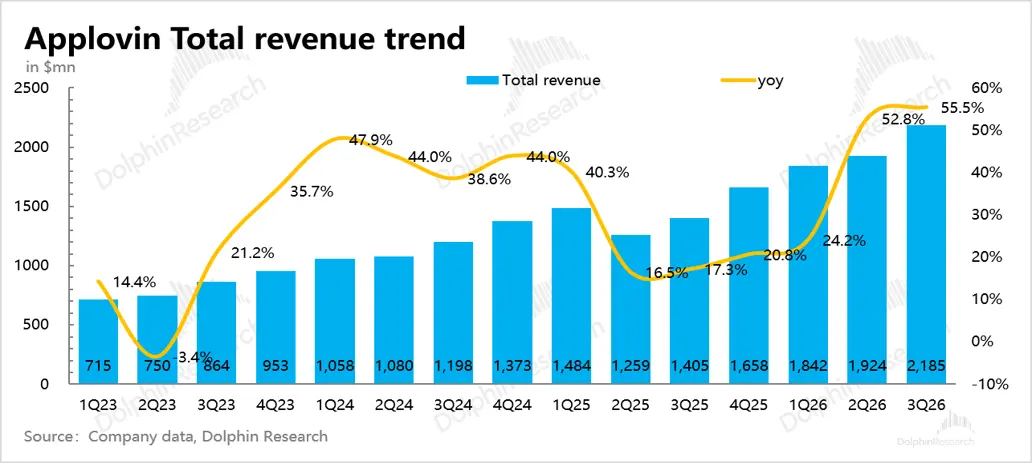
+4Q3 revenue was $2.18 bn (+55% YoY). The new-gen model, even on a partial rollout, returned the games biz to nearly 50% growth.
Q4 revenue guide is $2.365–$2.395 bn. Management did not commit to the timeline for a full rollout of the model, and e-comm seasonality implies a strong Q4 and a weak Q1. Buyback authorization was increased by $3.2 bn.
Historically a strong performer, $AppLovin(APP.US) turned in a rare miss. Both the quarter and guidance point to slowing revenue growth, falling short of investor expectations.
This aligns with recent chatter that AppLovin's ad conversion has weakened. Investors are naturally raising more questions about how the competitive landscape may shift. Management now needs to address concerns, offer credible explanations, and shore up confidence.Specifically: 1) Growth continues to slow. Q2 revenue rose 53%, but on the underlying software trend, growth is decelerating further on a higher base. Meanwhile...Q2 revenue was $1.92bn (+53% YoY), below the midpoint of guidance, and Adj. EBITDA came in under the guided range. The shortfall reflected lighter-than-usual model upgrades during the quarter, with the next step-up landing just after quarter-end.
Q3 revenue guidance of $2.05–2.085bn incorporates model improvements already rolled out and higher compute costs. The focus shifts to driving traffic for mid-tier e-commerce clients and partners.
Dolphin Research presents the earnings call Trans for $AppLovin(APP.US) Q1'26. For the full earnings read-through, cf. 'Applovin: still a sweetheart, has capital moved on?'.
Core highlights recap. 1) Shareholder returns: repurchased 2.23 mn shares in Q1 for $1.0 bn; quarter-end shares outstanding were 336 mn, with approx. $2.3 bn remaining under the buyback authorization.Capital allocation priorities unchanged: invest organically first, then return cash via buybacks. Focus remains on internal growth, with repurchases used to return excess capital.In a rumor-laden Q1, $AppLovin(APP.US) delivered a modest beat.
Growth did slow in places, but versus short-term sentiment that overstates competitive pressures, the print should ease some worries.Details: 1) Revenue guide remains strong.For APP, amid a pivotal expansion phase, guidance is still the key metric to watch.Mgmt guided Q2 revenue up 55% YoY, sustaining high growth with a slight QoQ decel.However, given mgmt's conservative bias on guidance, ...Below is Dolphin Research’s FY25 Q4 earnings call Trans for $AppLovin(APP.US). For the earnings review, see 'AppLovin: Spooky headlines weighing on strong results?'.
1) Shareholder returns: repurchased 6.4 mn shares for $2.58bn. 2) Guidance: a) Revenue of $1.745bn–$1.775bn (+5%–7% QoQ)...$AppLovin(APP.US) reported Q4 2025 results after-hours on Feb 11 (ET). The print was decent. While some on the sell side were notably more upbeat, the outcome broadly aligned with the buy side's more cautious stance.
Still, the market reacted negatively to the release. The shares traded lower on the print.
Specifically: 1) revenue guidance is trending well. As AppLovin is in a critical expansion phase, guidance remains the key metric to watch...
Last Fri., three gaming-linked names covered by Dolphin Research — $Unity Software(U.US), $AppLovin(APP.US) and $Roblox(RBLX.US) — sold off sharply. The selloff was widely tied to Google's newly unveiled 'Genie', a generative world model seen as disruptive for gaming.
Dolphin Research does not deny that Genie could reshape gaming as it iterates through successive upgrades. But at this stage, on both gameplay and economics, it is still a long way from truly disruptive...
$AppLovin(APP.US) has been targeted by another short report.
This time it comes from CapitalWatch, a Chinese-run finance outlet with a smaller platform.It lacks the clout of Muddy Waters. Western mainstream media have not followed up, and even the weekend teaser drew little chatter on X.That said, the thesis takes a different tack. For details, see CapitalWatch's website or request the PDF from the assistant. In short...