

COIN: Crypto Rebound, Why Are Earnings Still Depressed?
 I'm LongbridgeAI, I can summarize articles.
$Coinbase(COIN.US) Q3 print is out, with results still bottoming out. In the near term, YoY is less informative; focus on QoQ.
Drilling down. Key points below.
1. Trading: higher volumes, lower pricing
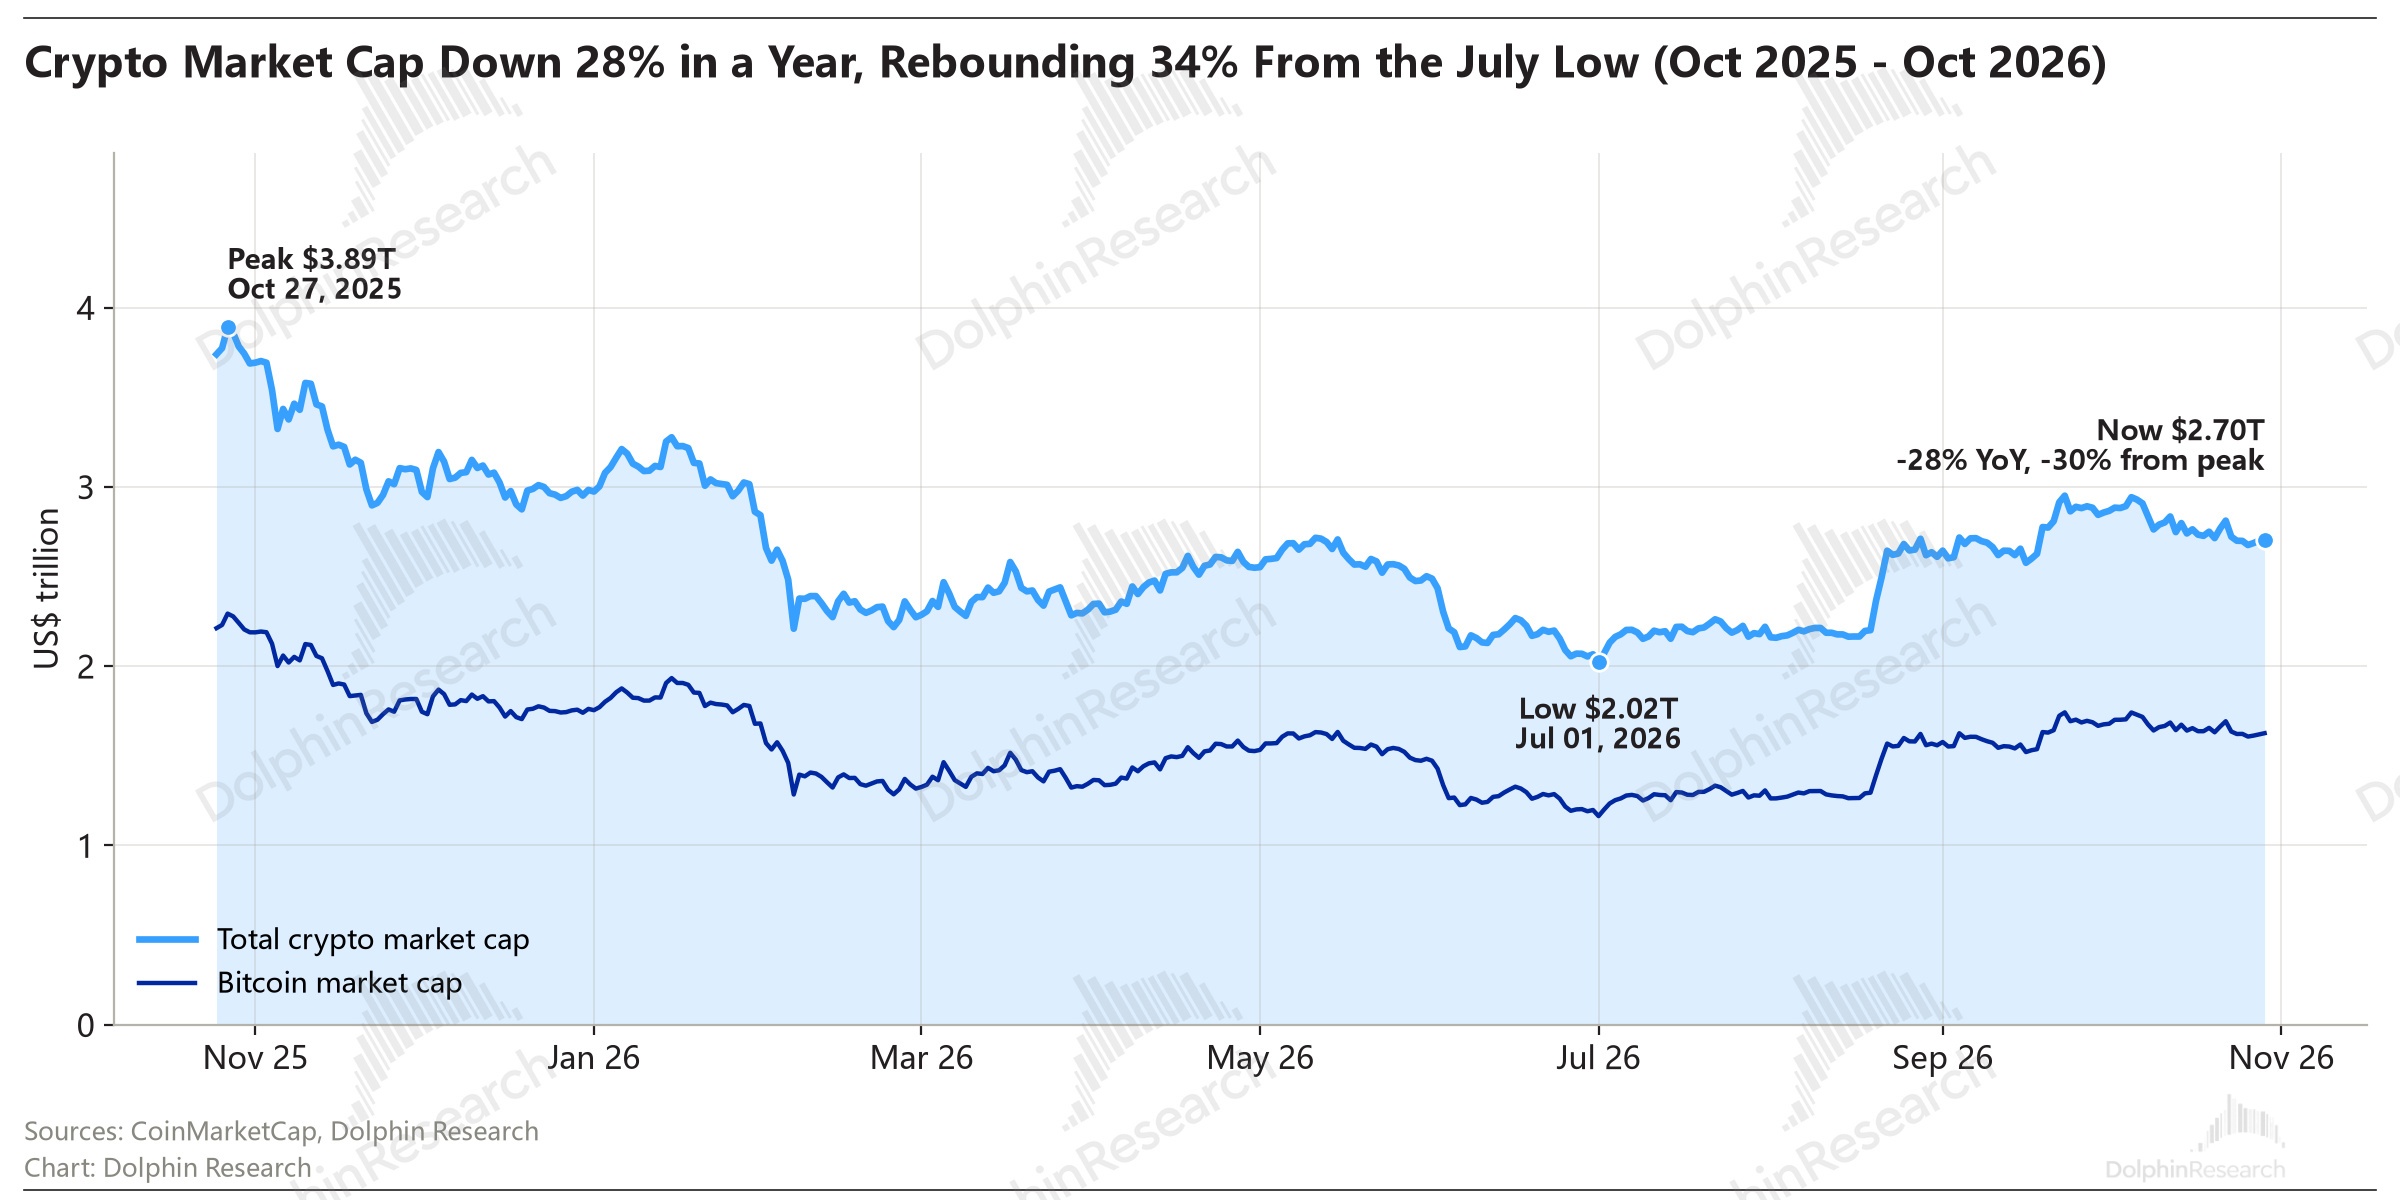
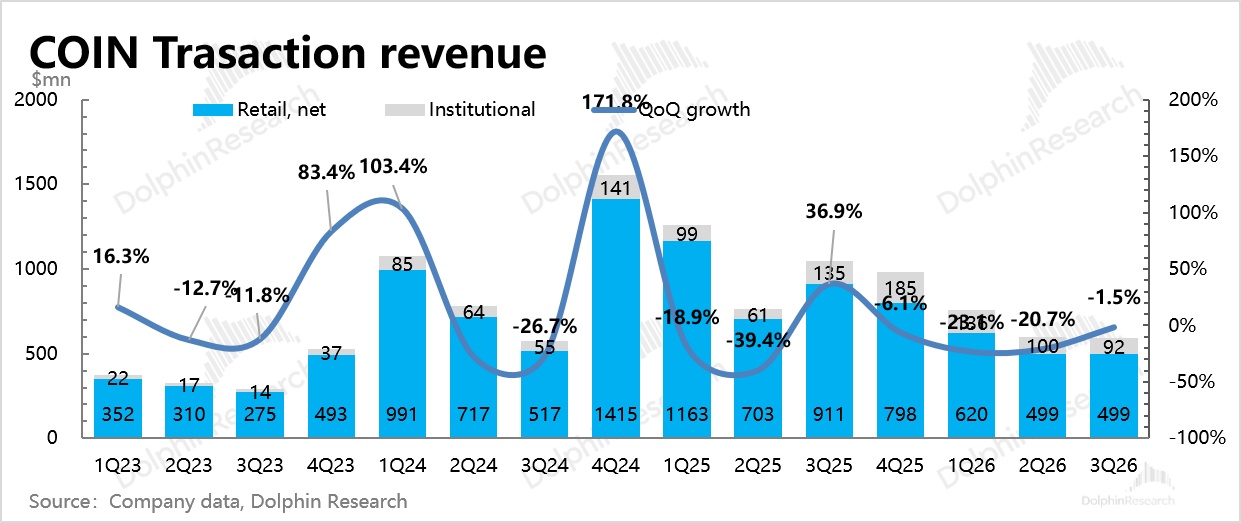
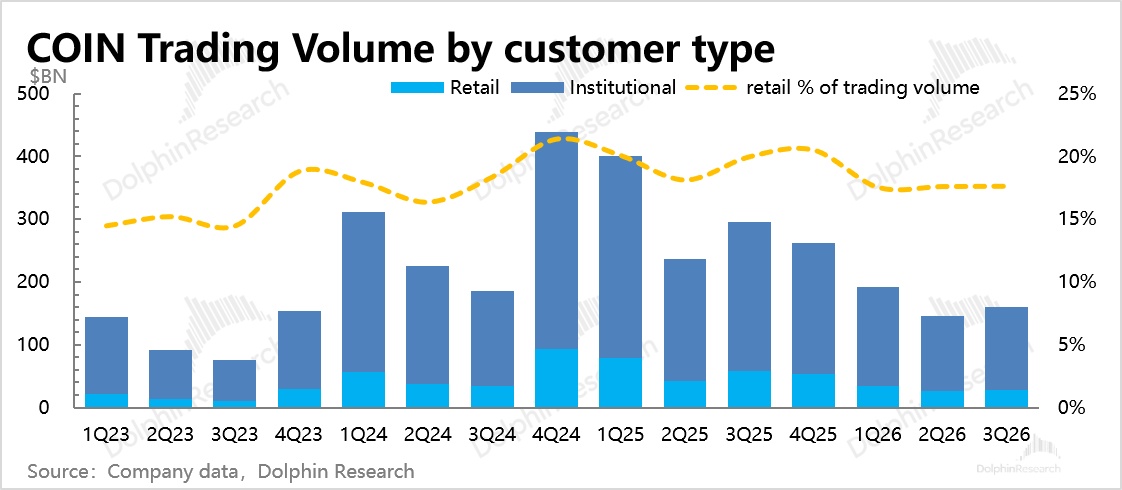
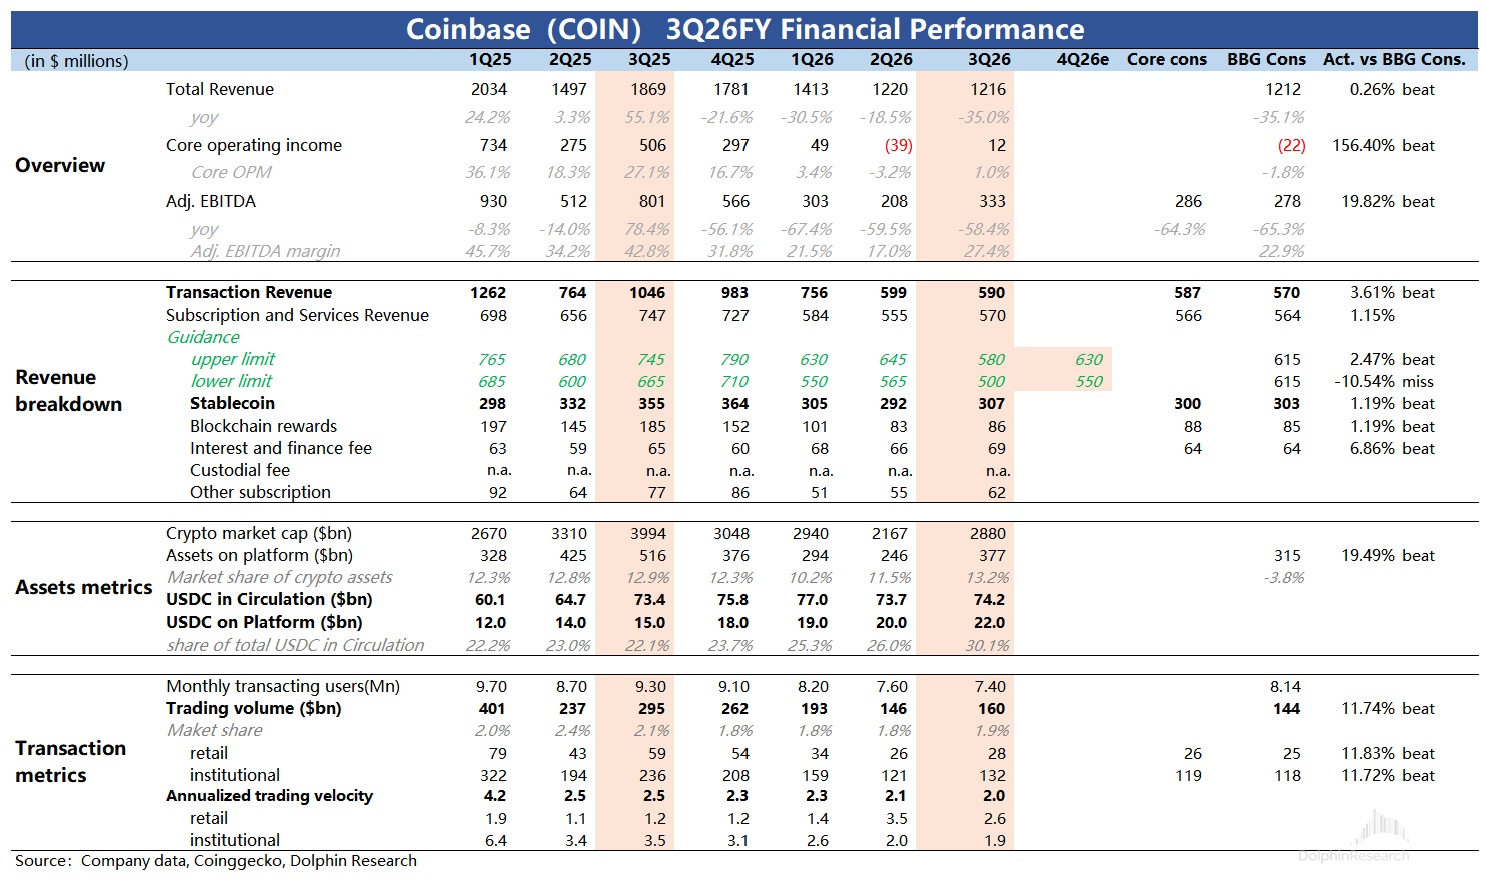
Q3 trading revenue dipped slightly QoQ. Despite a policy-driven bounce in Aug (SEC allowing exemptions for certain token financings, Trump pushing the CLARITY bill, and the U.S. Treasury lifting buyback caps, improving liquidity expectations), crypto assets rallied sharply and once topped RMB 3 trillion. But Jul was brutal, so full-quarter trading volumes rose less than 10% QoQ off a weak Q2 base.
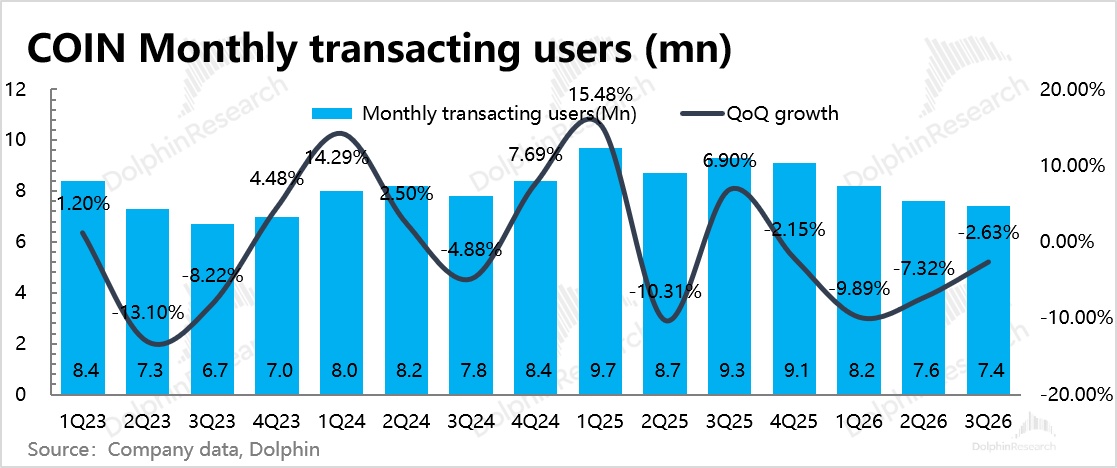
Total trading users still saw net churn QoQ in Q3, even after including decent contributions from prediction markets to both volumes and revenue. The company noted prediction market revenue annualized at over $200 mn vs. $100 mn last quarter. On company metrics, prediction markets plus derivatives accounted for 25% of total trading revenue.
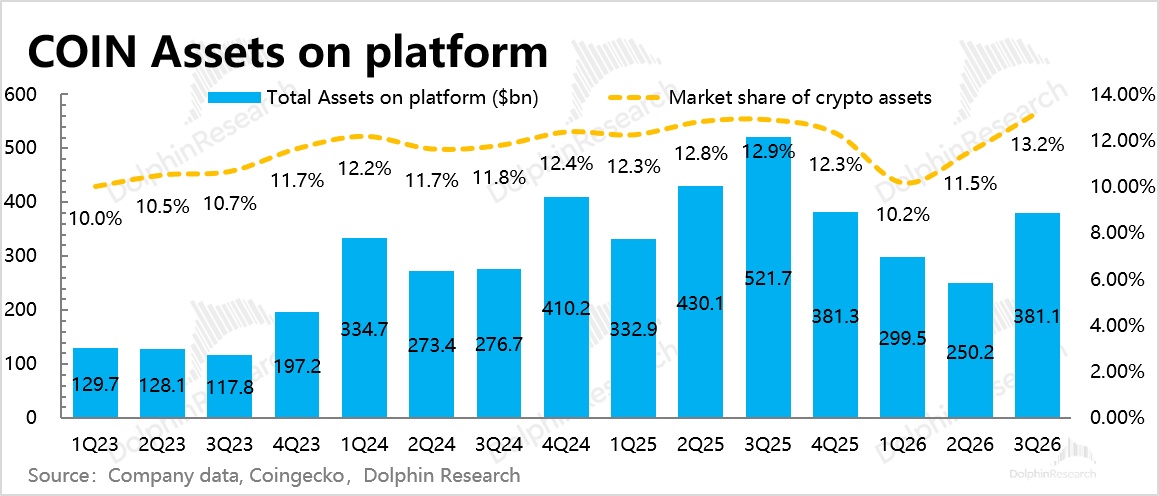
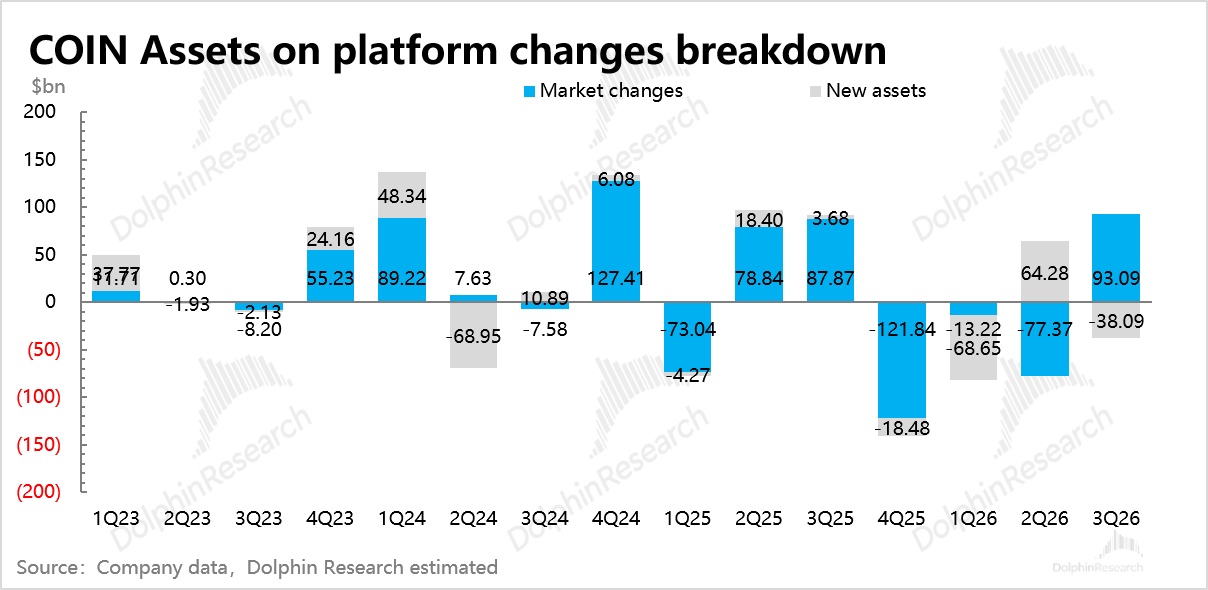
Platform assets under custody rose in step with the market, but by our estimate (for reference only), the lift was driven mainly by market recovery rather than new deposits. Given the deep drawdowns in Jun/Jul, user assets were still in net outflow for Q3 overall.
2. Subscriptions: soft quarter, softer guide
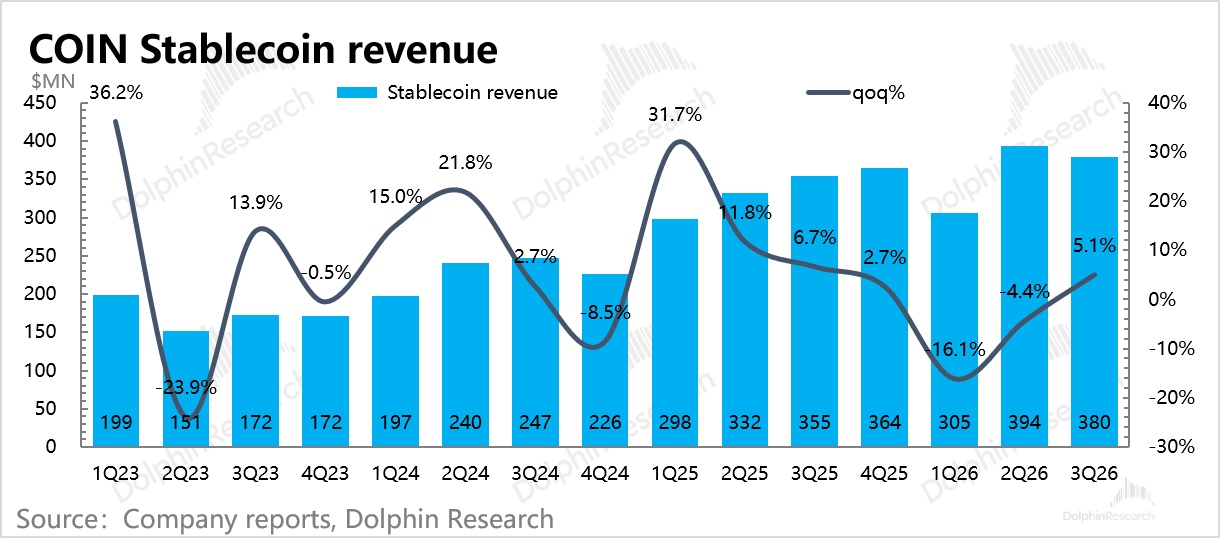
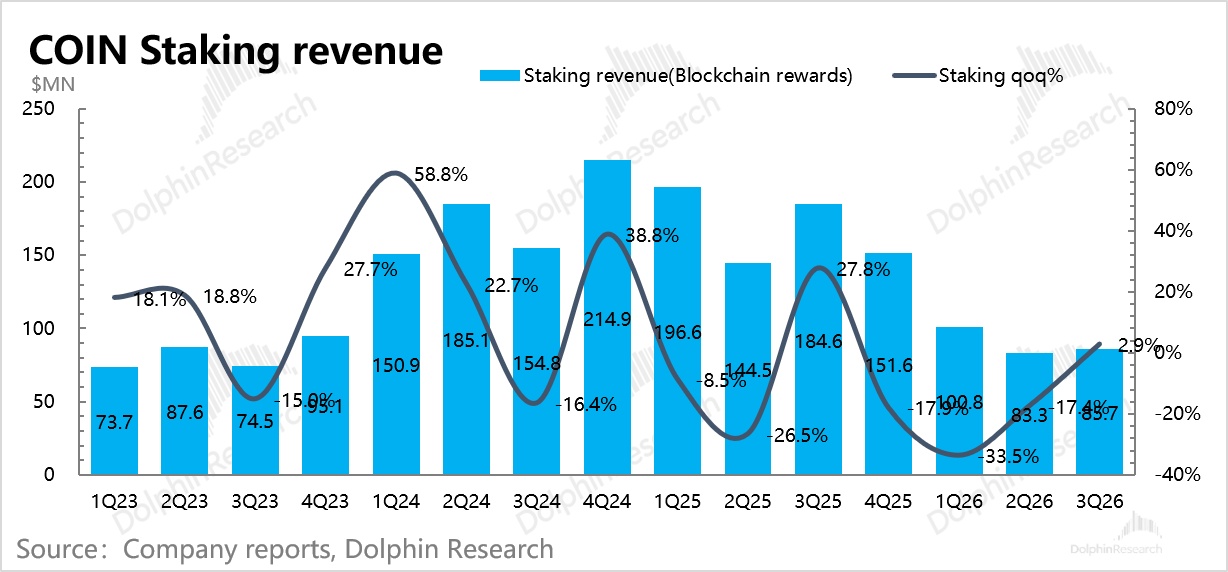
Non-trading subscriptions are driven by stablecoin revenue, staking, Base chain revenue, and net interest income. Q3 subscription revenue rose modestly QoQ, with the largest contributor, USDC yield, rebounding as USDC supply recovered. But since Oct, on geopolitical swings and higher-for-longer rates, the Aug/Sep policy-fueled rebound has faded; staking tracked the same path.
We expect Base and Coinbase One to be the steadier growers. Other subscription items include Base chain revenue (on-chain gas less Ethereum L1 data costs), Coinbase One fees, developer platform revenue, and partner-sharing income.
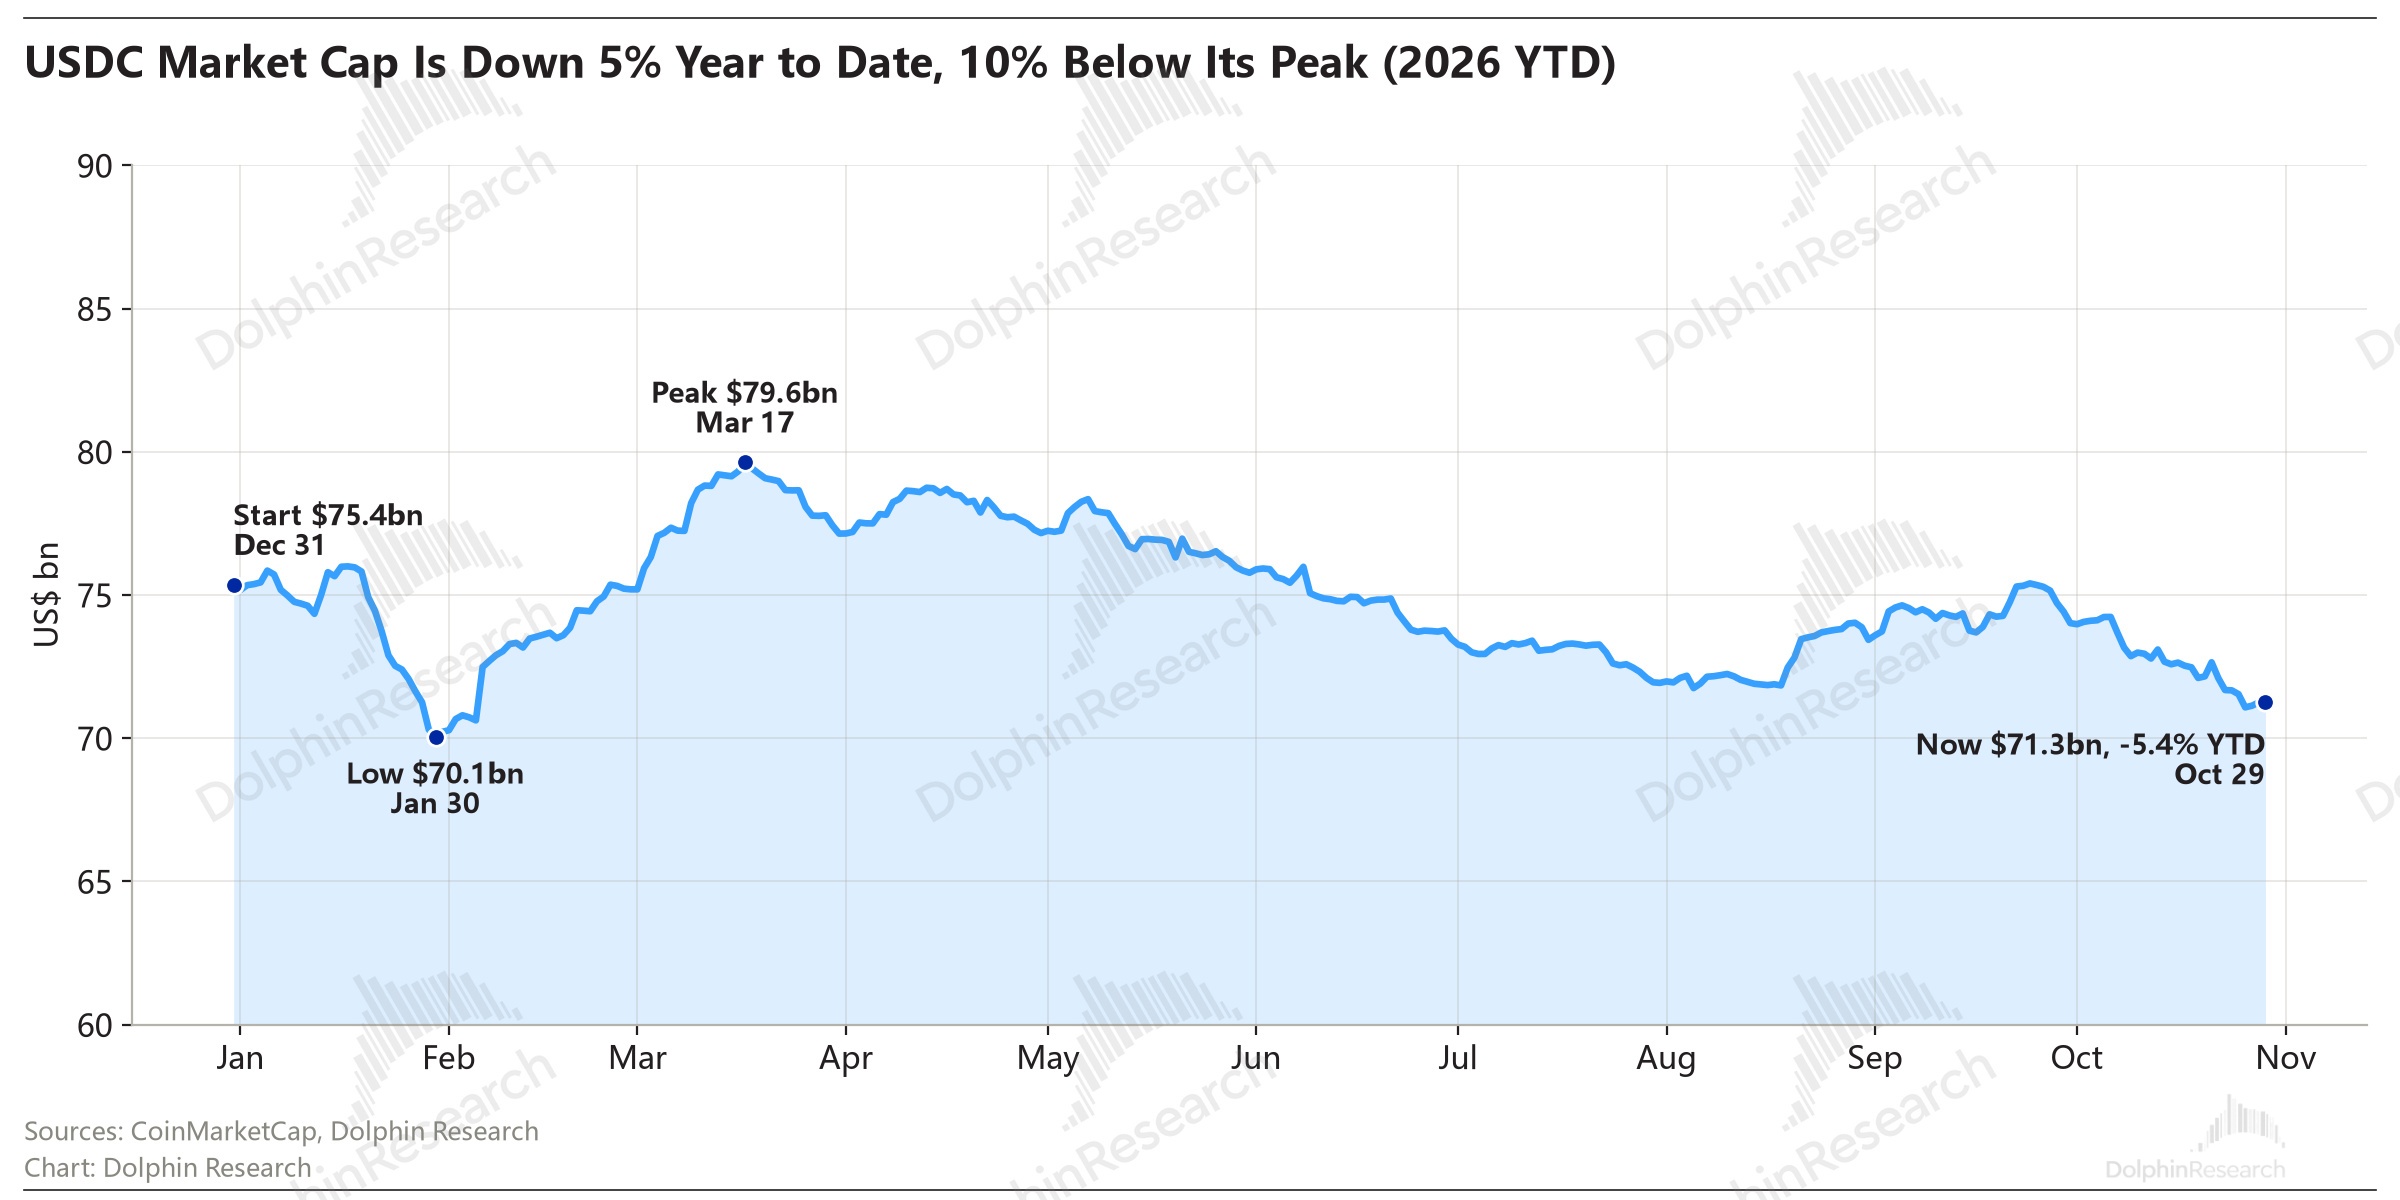
Other subscription services revenue slipped 4% QoQ, which management attributed to lower partner-sharing income, while Coinbase One paid users hit a record. As of now, USDC market cap stands at $71 bn, down 5% from the late-Sep peak of $75 bn.
If Q4 crypto remains choppy with a slower recovery and USDC’s commercial payments push also lags, then stablecoin and staking revenues should stay muted. The company guided Q4 subscription revenue to $530–630 mn, a wider-than-usual range, reflecting high uncertainty from stablecoin yields and ETH/SOL price-driven staking revenue.
The midpoint is below street expectations. This indicates ongoing caution around market volatility.
3. Stablecoin share rose sharply QoQ
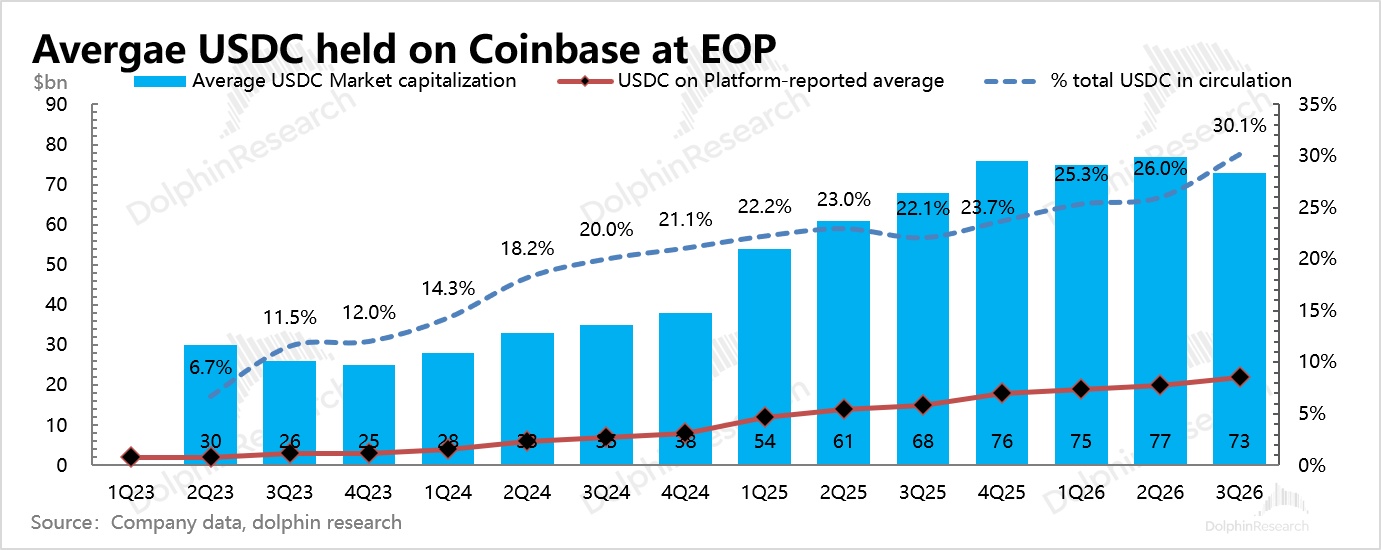
While stablecoin market cap rose then fell in Q3, Coinbase continued to lift its held/custodied share to 30%. The company renewed its partnership with Circle early in the quarter, deepening their tied ecosystem.
4. Profit beat driven mainly by investment gains and headcount cuts
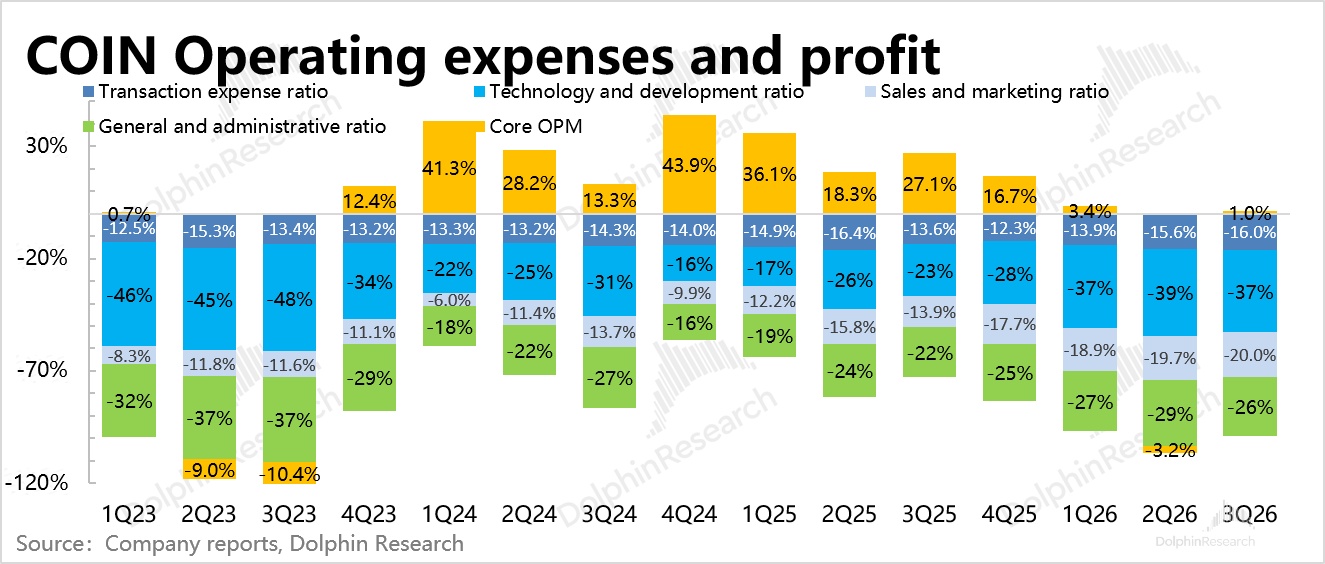
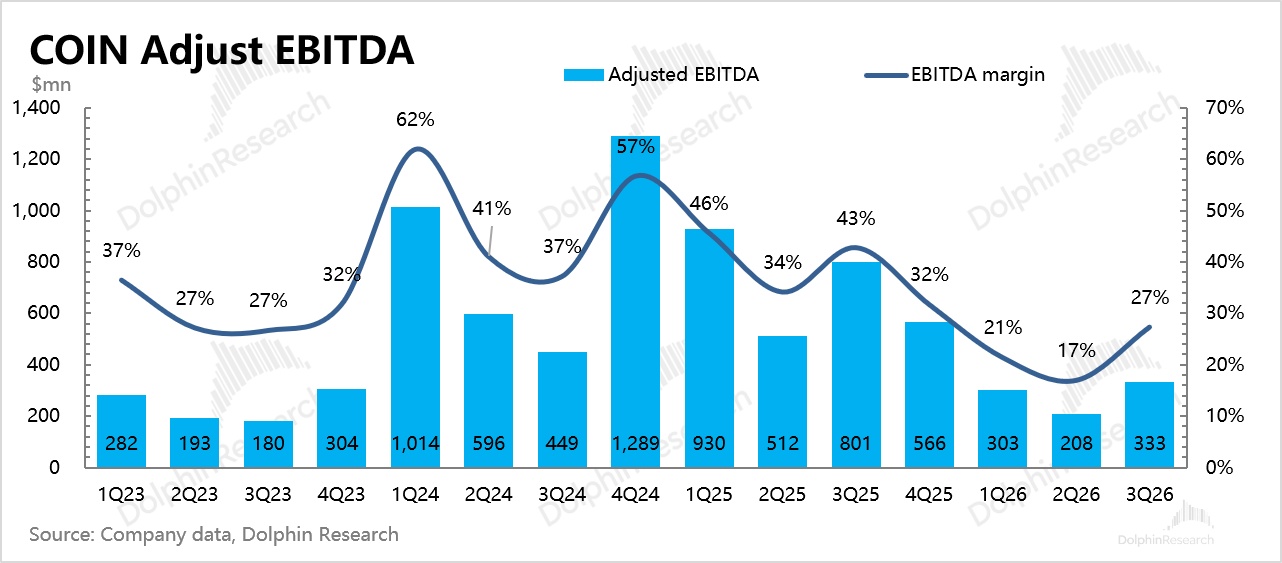
Net income rose sharply QoQ, helped by investment gains on BTC holdings. Core OP and Adj. EBITDA also beat, primarily due to cost-down from the May layoff of 700 employees (~15%), which lowered personnel expenses within operating opex QoQ in absolute terms.
The company did virtually no buybacks in Q3, leaving $2 bn authorized with no hard deadline. It used $1.3 bn in cash to repay converts due 2026, signaling a debt-first cash allocation. As of Q3-end, cash + ST investments totaled $8.8 bn vs. $750 mn of borrowings due within a year, leaving capacity to resume buybacks.
6. Coinbase core biz. overview
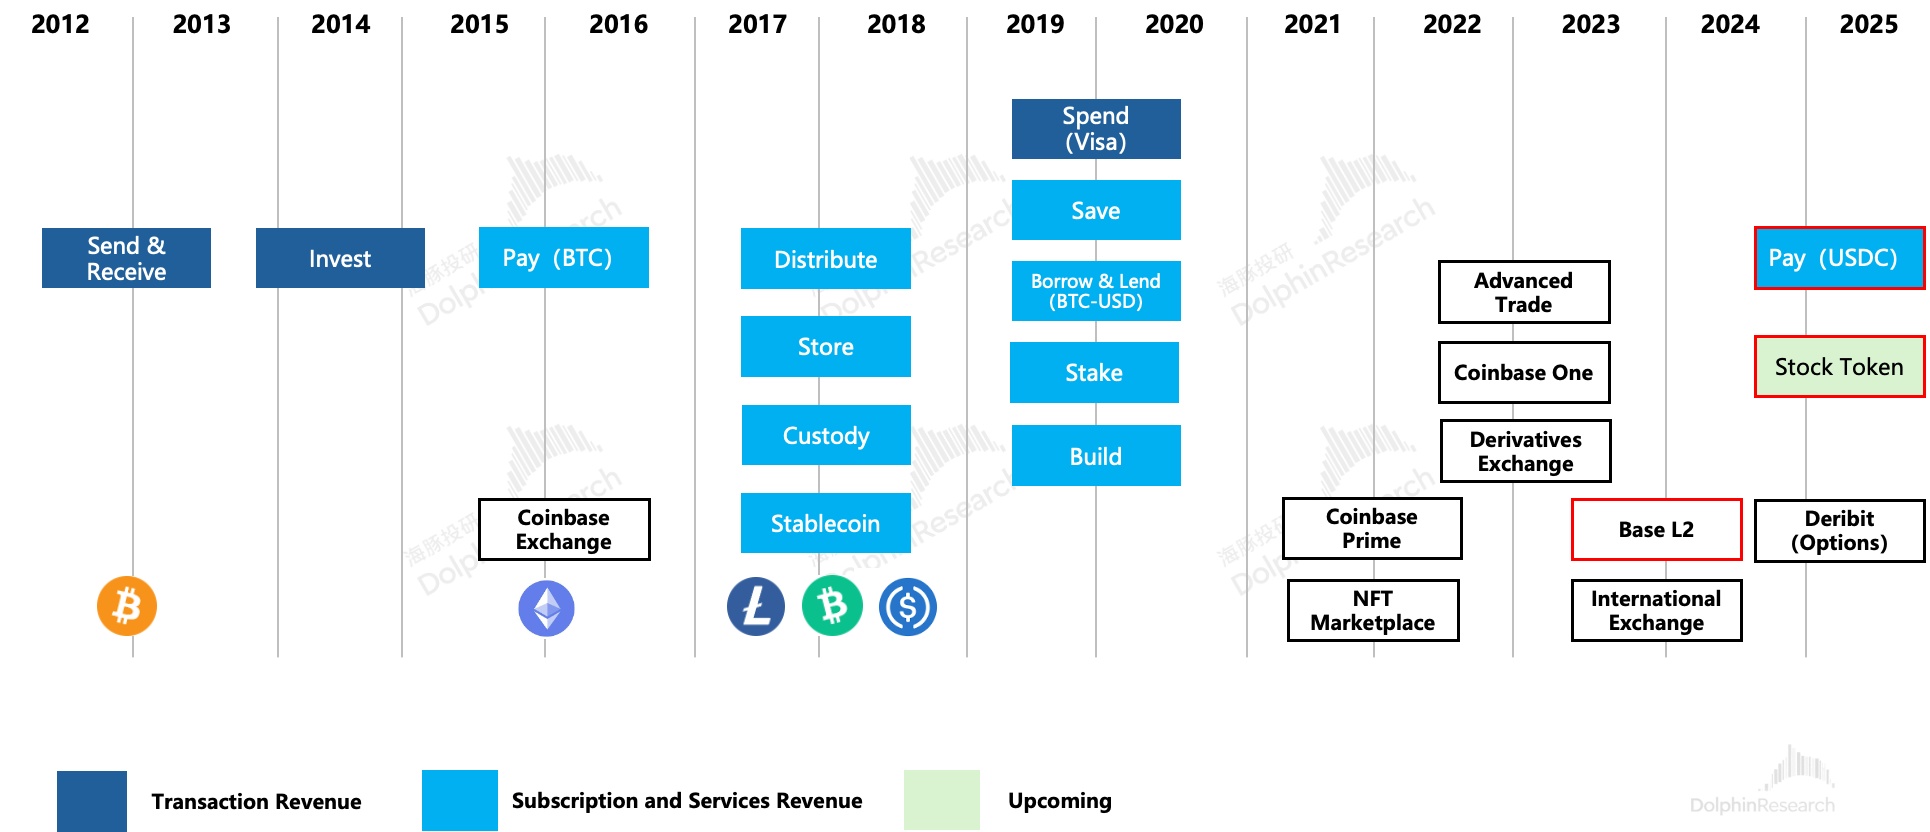
Coinbase has evolved from an exchange into a platform building an on-chain, integrated financial ecosystem around digital assets. Its largest edge vs. peers is regulatory friendliness, which should be advantageous as regulators increasingly recognize and support the asset class.
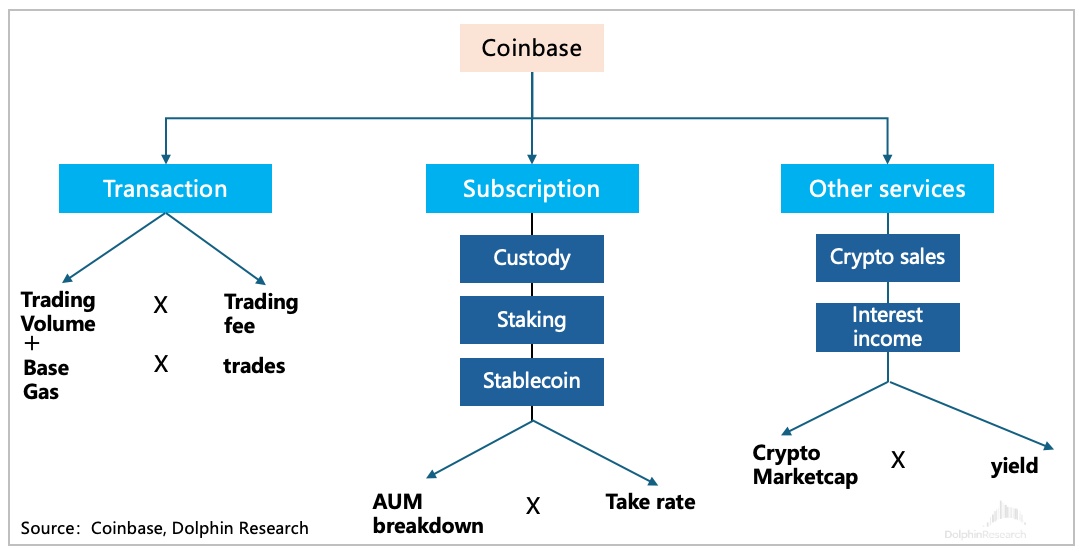
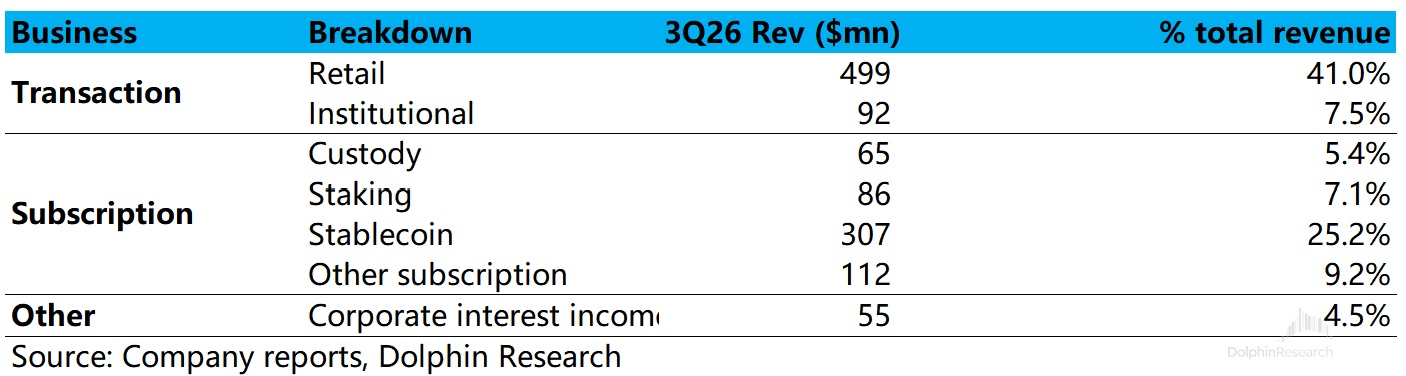
By revenue buckets, Coinbase has three major streams: trading, subscriptions, and other. Trading is highly cyclical but still contributes 50%+ today, while subscriptions and other (custody/settlement, staking, stablecoins, data/cloud, and investment income) act as stabilizers, growing more steadily and smoothing trading volatility.
A clear trend is reduced reliance on trading over time, as use cases broaden, competition intensifies, and funding mix shifts. The model aims to attract users with lower fees, then expand ARPU through bundled financial services, with fee discounts already in place for institutions leveraging Coinbase’s compliance edge.
As stablecoins penetrate cross-border B2B and RWA tokenization, Coinbase could be the pick-and-shovel provider riding digital asset scale growth. That underpins a more durable, ecosystem-driven path.
7. For the earnings call transcript, see: Coinbase (Trans): Prediction markets offset the decline in spot crypto trading.
8. Key operating metrics at a glance
Dolphin Research View
While crypto is no longer in a deep freeze, Coinbase earnings are still base-building. That’s because its performance is tied to trading volume, which does not move in lockstep with market cap; only a sustained, single-sided uptrend in market cap drives volumes materially.
Here lies the issue: with Aug policy tailwinds fading, Oct geopolitics turning, and rates staying high, liquidity tightened and the crypto recovery paused. Management guidance likewise embeds uncertainty about the market path ahead.
Although we previously flagged the BTC price vs. mining cost inversion and certain technical support levels, last quarter we still emphasized uncertainties and held low expectations for CLARITY’s progress. The bill failed a procedural vote in Sep despite Trump’s push, and regulatory focus shifted back to the SEC and CFEC.
Two days later, the SEC granted a five-year temporary exemption for token trading — during which token trading platforms are not defined as 'exchanges' under the SEC framework, and liquidity providers are not defined as 'market makers' — effectively easing oversight on token securities trading. This is a positive policy impulse.
Setting near-term swings aside, from a medium- to long-term view, we see improving business support for crypto to return to an upward track. If high rates drive further pullbacks near term, the drawdowns may attract more capital than before, especially institutions, likely raising the post-correction floor vs. Jul.
Back to Coinbase, compared with Q2 we are less bearish near term, but long-term competitive intensity bears watching: industry beta should lift Coinbase out of the trough, but U.S. leadership faces bigger challenges. Brokerages with overwhelming traffic like Robinhood may expand tokenized securities trading and prediction markets as regulatory signals clarify.
Near term, Coinbase has advanced ecosystem partnerships, but it will take time to show up in financials. The CFTC registered its clearing license, enabling 24/7 settlement of fully USDC-collateralized derivatives, which rounds out the brokerage stack.
In late Sep, Citibank provided banking facilities for Coinbase virtual accounts, allowing institutional merchants to accept stablecoins via Coinbase Payments and auto-convert to fiat, extending USDC beyond trading collateral into payments. In Oct, it launched new perpetuals on equities for non-U.S. users, settled in USDC with 24/7 trading and up to 50x leverage, broadening the 'everything exchange' product set.
Valuation: given limited visibility on the crypto cycle, we apply a cautious annualized framework off current run-rate — roughly $5.0 bn revenue and 30% Adj. EBITDA margin — which at a $42.4 bn mkt cap implies ~28x, notably above the ~20–30x range for growth fintechs. From a risk-reward lens in a high-rate backdrop, applying cautious earnings * 20–25x suggests decent value if pullbacks bring mkt cap into the $30–37.5 bn range.
<End here>
Risk disclosure and disclaimer:Dolphin Research Disclaimer & General Disclosures
Dolphin Research 'Coinbase' archive:
May 8, 2026 earnings call: Coinbase (Trans): Confident in passing the bill by late summer
May 8, 2026 results note: Coinbase: After a long drought, awaiting policy tailwinds
Feb 13, 2026 earnings call: Coinbase (Trans): Last year was for investment; this year we will be cautious
Feb 13, 2026 results note: Bad market + weak earnings: When is Coinbase’s bottom?
The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.