

Airbnb 3Q26 First Take: Results beat by a wide margin, with both growth and profitability strong, sending the stock up a…
Airbnb 3Q26 First Take: Results beat by a wide margin, with both growth and profitability strong, sending the stock up about 10% after hours.
On growth, GBV and nights both accelerated, with every region picking up pace and no weak links, while on profit, margins rose YoY despite prior guidance calling for a slight decline. Next-quarter guidance also topped expectations, though growth is set to moderate vs this quarter.1) GBV and Nights: Broad beat with clear acceleration
Nights & Seats rose 16% YoY, accelerating by 6pts vs last quarter.
GBV grew 21% YoY, also a clear acceleration, with both metrics ~4–5% above expectations. ADR increased 4% YoY, slightly ahead of estimates.The largest markets, North America and Europe, were strong: North America saw its fastest growth in four years, with nights back to double-digit growth.
Europe accelerated from high single digits to mid-teens (~15%).2) Revenue: Beat and accelerated, but monetization dipped
Revenue was $4.87bn, up 19% YoY (ex-FX +16%).
Growth accelerated vs last quarter and beat expectations.The monetization rate was 17.6%, down YoY and below expectations, causing revenue growth to trail GBV.
RNPL (Reserve Now, Pay Later) created a timing mismatch, as guests book earlier but revenue is recognized upon stay.3) Profit: Lower expense ratio, margins up YoY
Adj. EBITDA was $2.51bn, about 6% above expectations.
Margin reached 52%, up ~140bps YoY, against prior guidance for a slight YoY decline.The expense ratio narrowed YoY and came in below expectations, though opex growth itself was not low (opex +14% YoY, with marketing +24%).
The lower ratio mainly reflects operating leverage from faster revenue growth.4) 4Q guide: Above expectations, but slower than this quarter
Revenue guidance is $3.22–3.28bn, +16%–18% YoY, with the midpoint ~3% above expectations.
Full-year revenue growth and margin guidance were raised again.However, GBV is guided to mid-teens and nights to 'at least low double digits', a clear slowdown vs this quarter, likely partly due to RNPL pulling demand into Q3.
Margin guidance implies a slight YoY decline, which the company attributes partly to marketing cadence.5) Shareholder returns: New $12bn buyback authorization
Buybacks totaled $2.8bn over the first three quarters, which annualizes to ~3.5% of market cap.
A new $12bn authorization was added; including remaining prior authorization, total capacity is near $15bn, or about 13%–14% of market cap.$Airbnb(ABNB.US)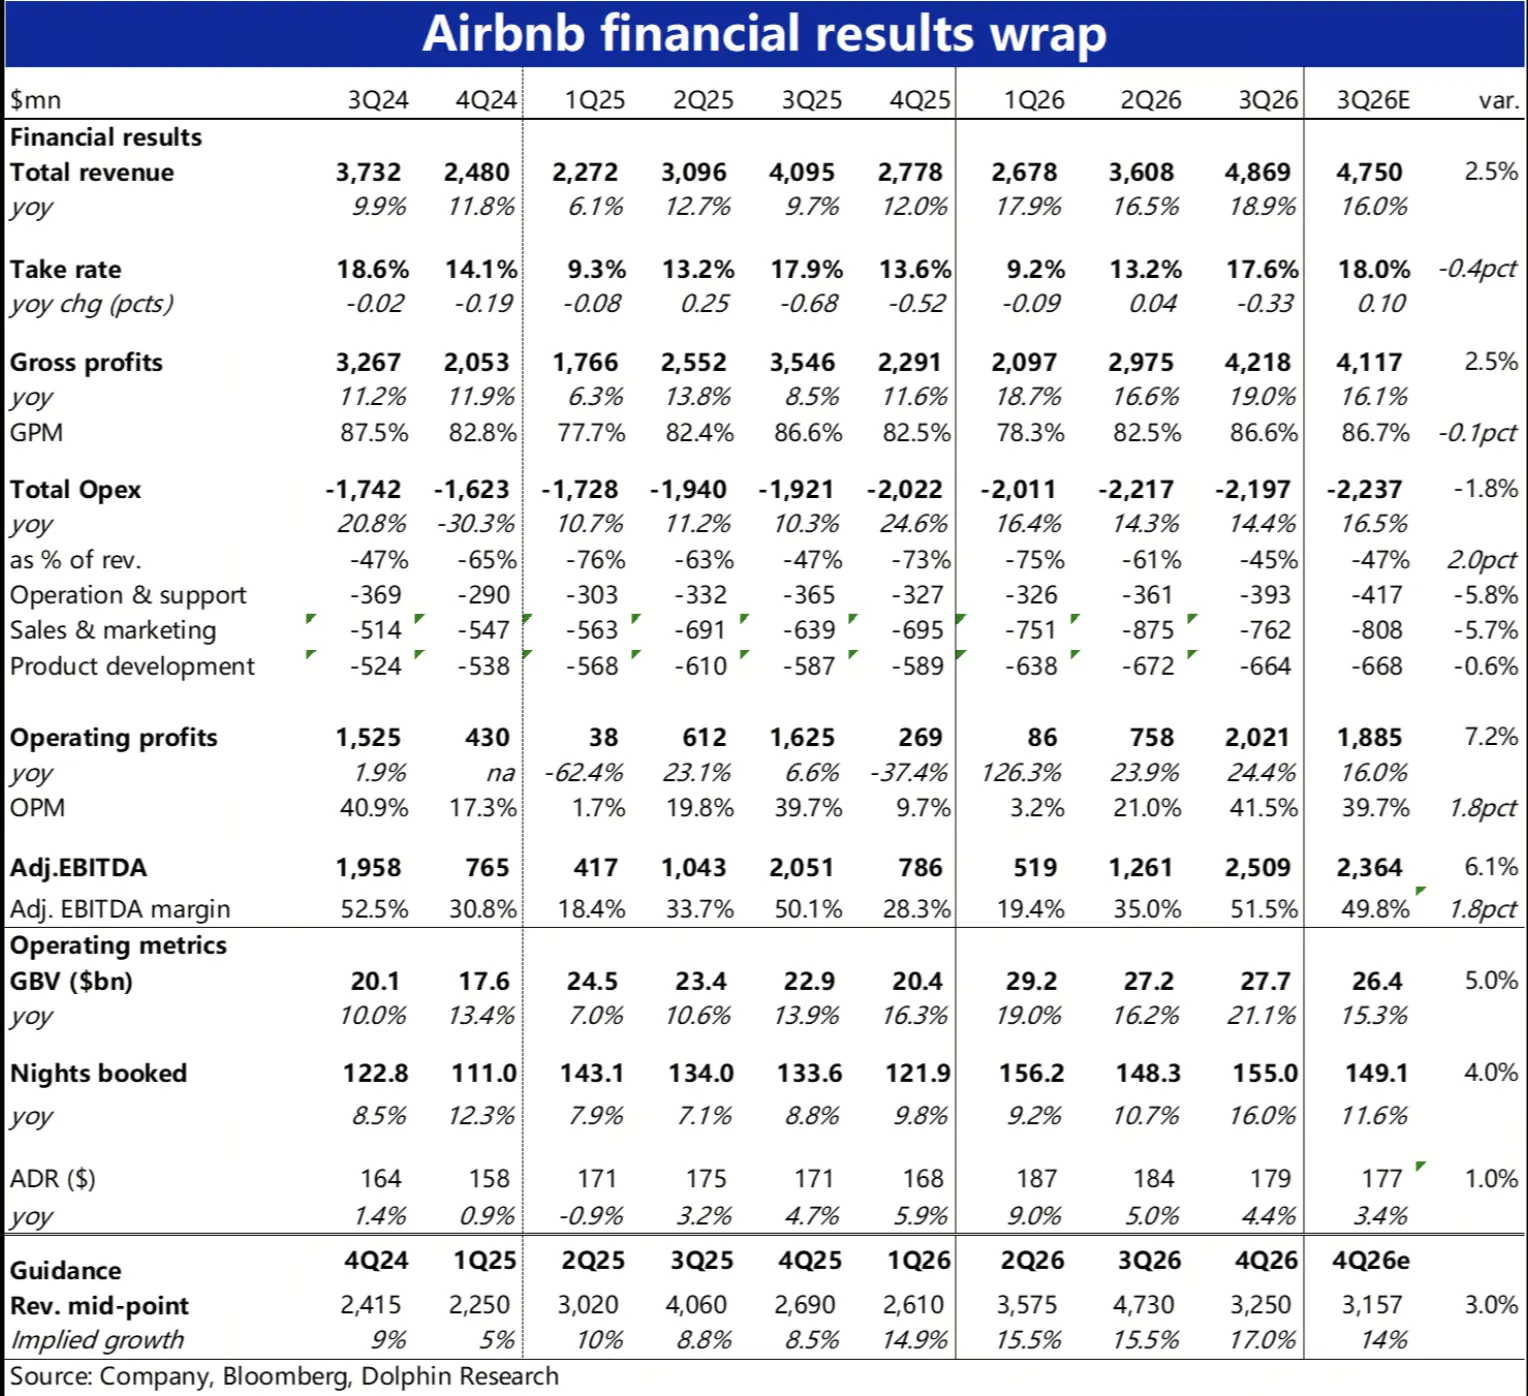
The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.