

MNST 3Q26 First Take: Overall, revenue remained solid in Q3, powered by Intl markets. However, a higher overseas mix and…
MNST 3Q26 First Take: Overall, revenue remained solid in Q3, powered by Intl markets. However, a higher overseas mix and rising freight and marketing spend weighed on margins; both GPM and OPM declined YoY, and profit growth lagged revenue.
Revenue grew about 17%, beating expectations, with volume still the primary driver. Intl rose nearly 30%, with LatAm and EMEA still posting strong growth; the U.S. held high single-digit growth despite a tough comp.
Profits clearly lagged. With a higher overseas mix and higher aluminum can and inbound freight costs, GPM fell 100bps YoY to 54.7%.
On opex, fuel surcharges lifted the distribution cost ratio by 70bps, and marketing spend stepped up. Including approx. $34.6 mn of asset impairments and digital transformation costs, the opex ratio rose 160bps YoY to 26.6%, leaving OP up just 6.4% and OPM down 270bps YoY to 28.0%.$Monster Beverage(MNST.US)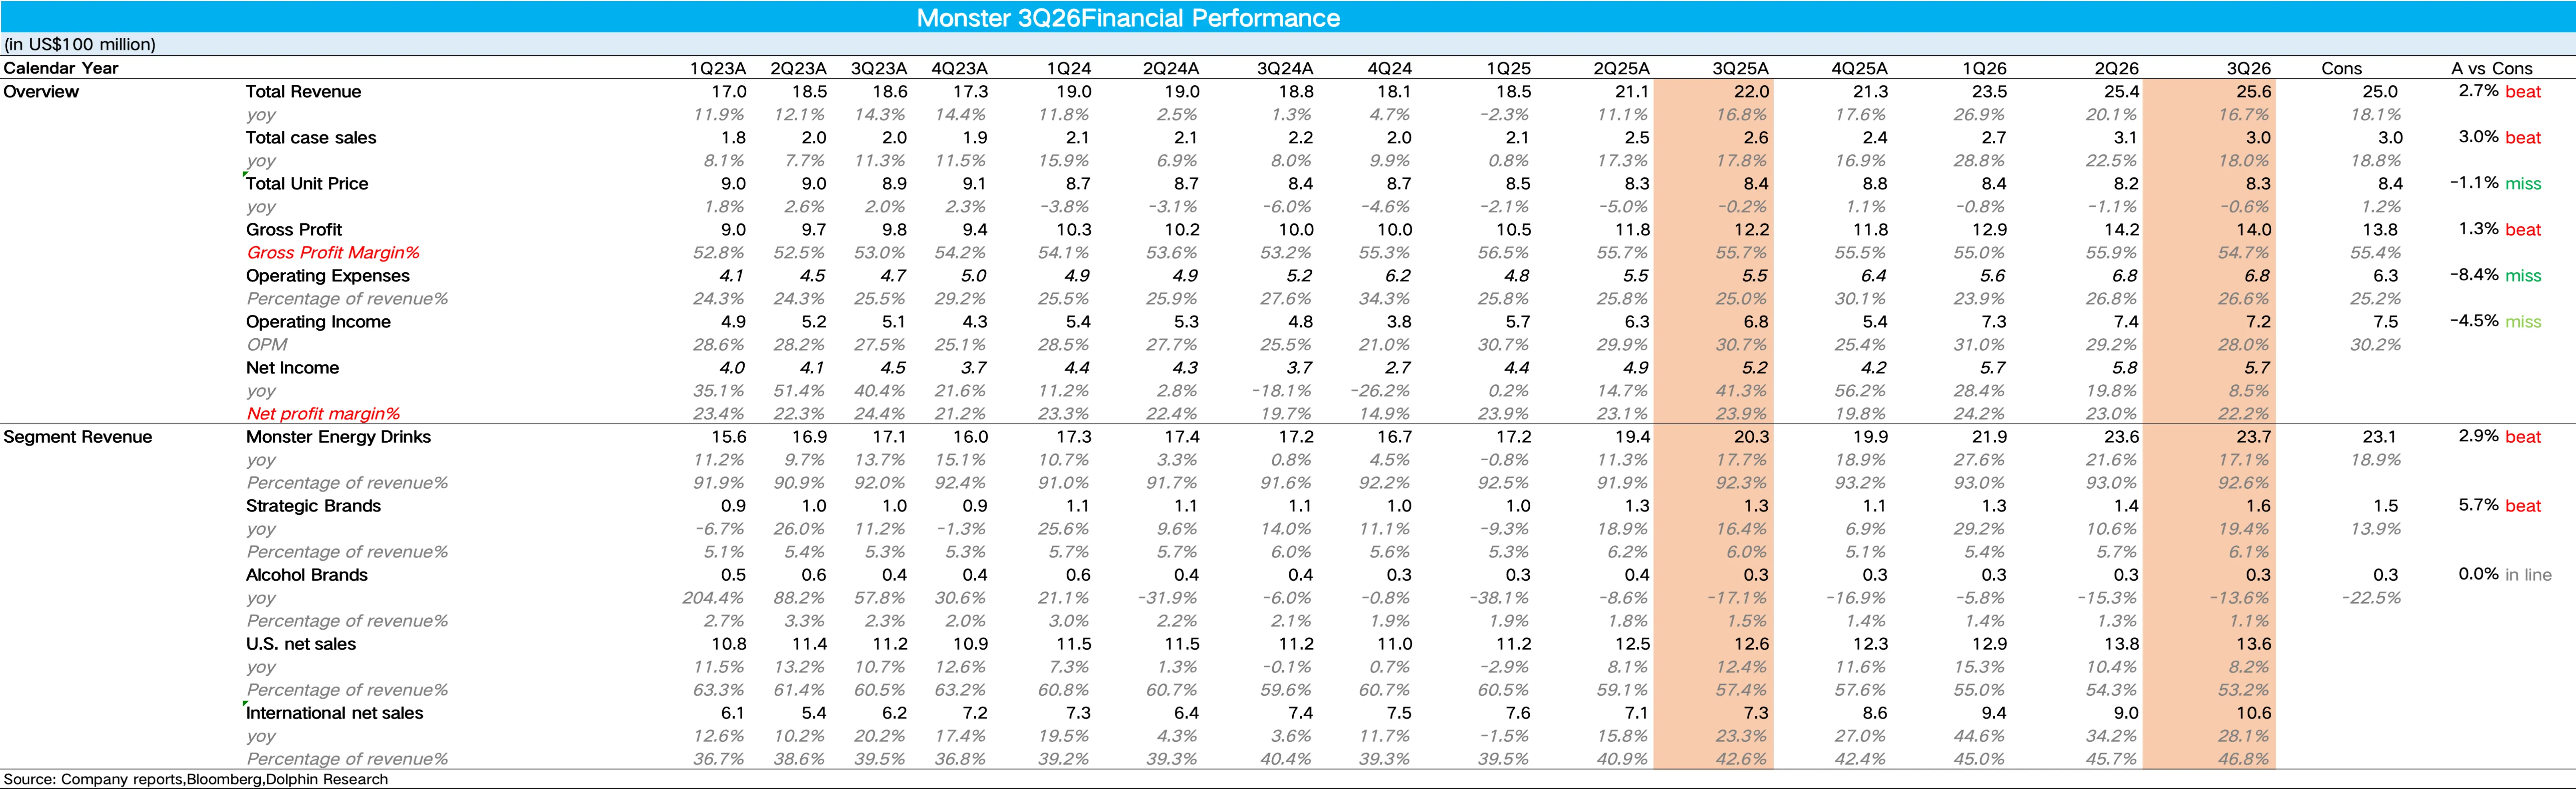
The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.