

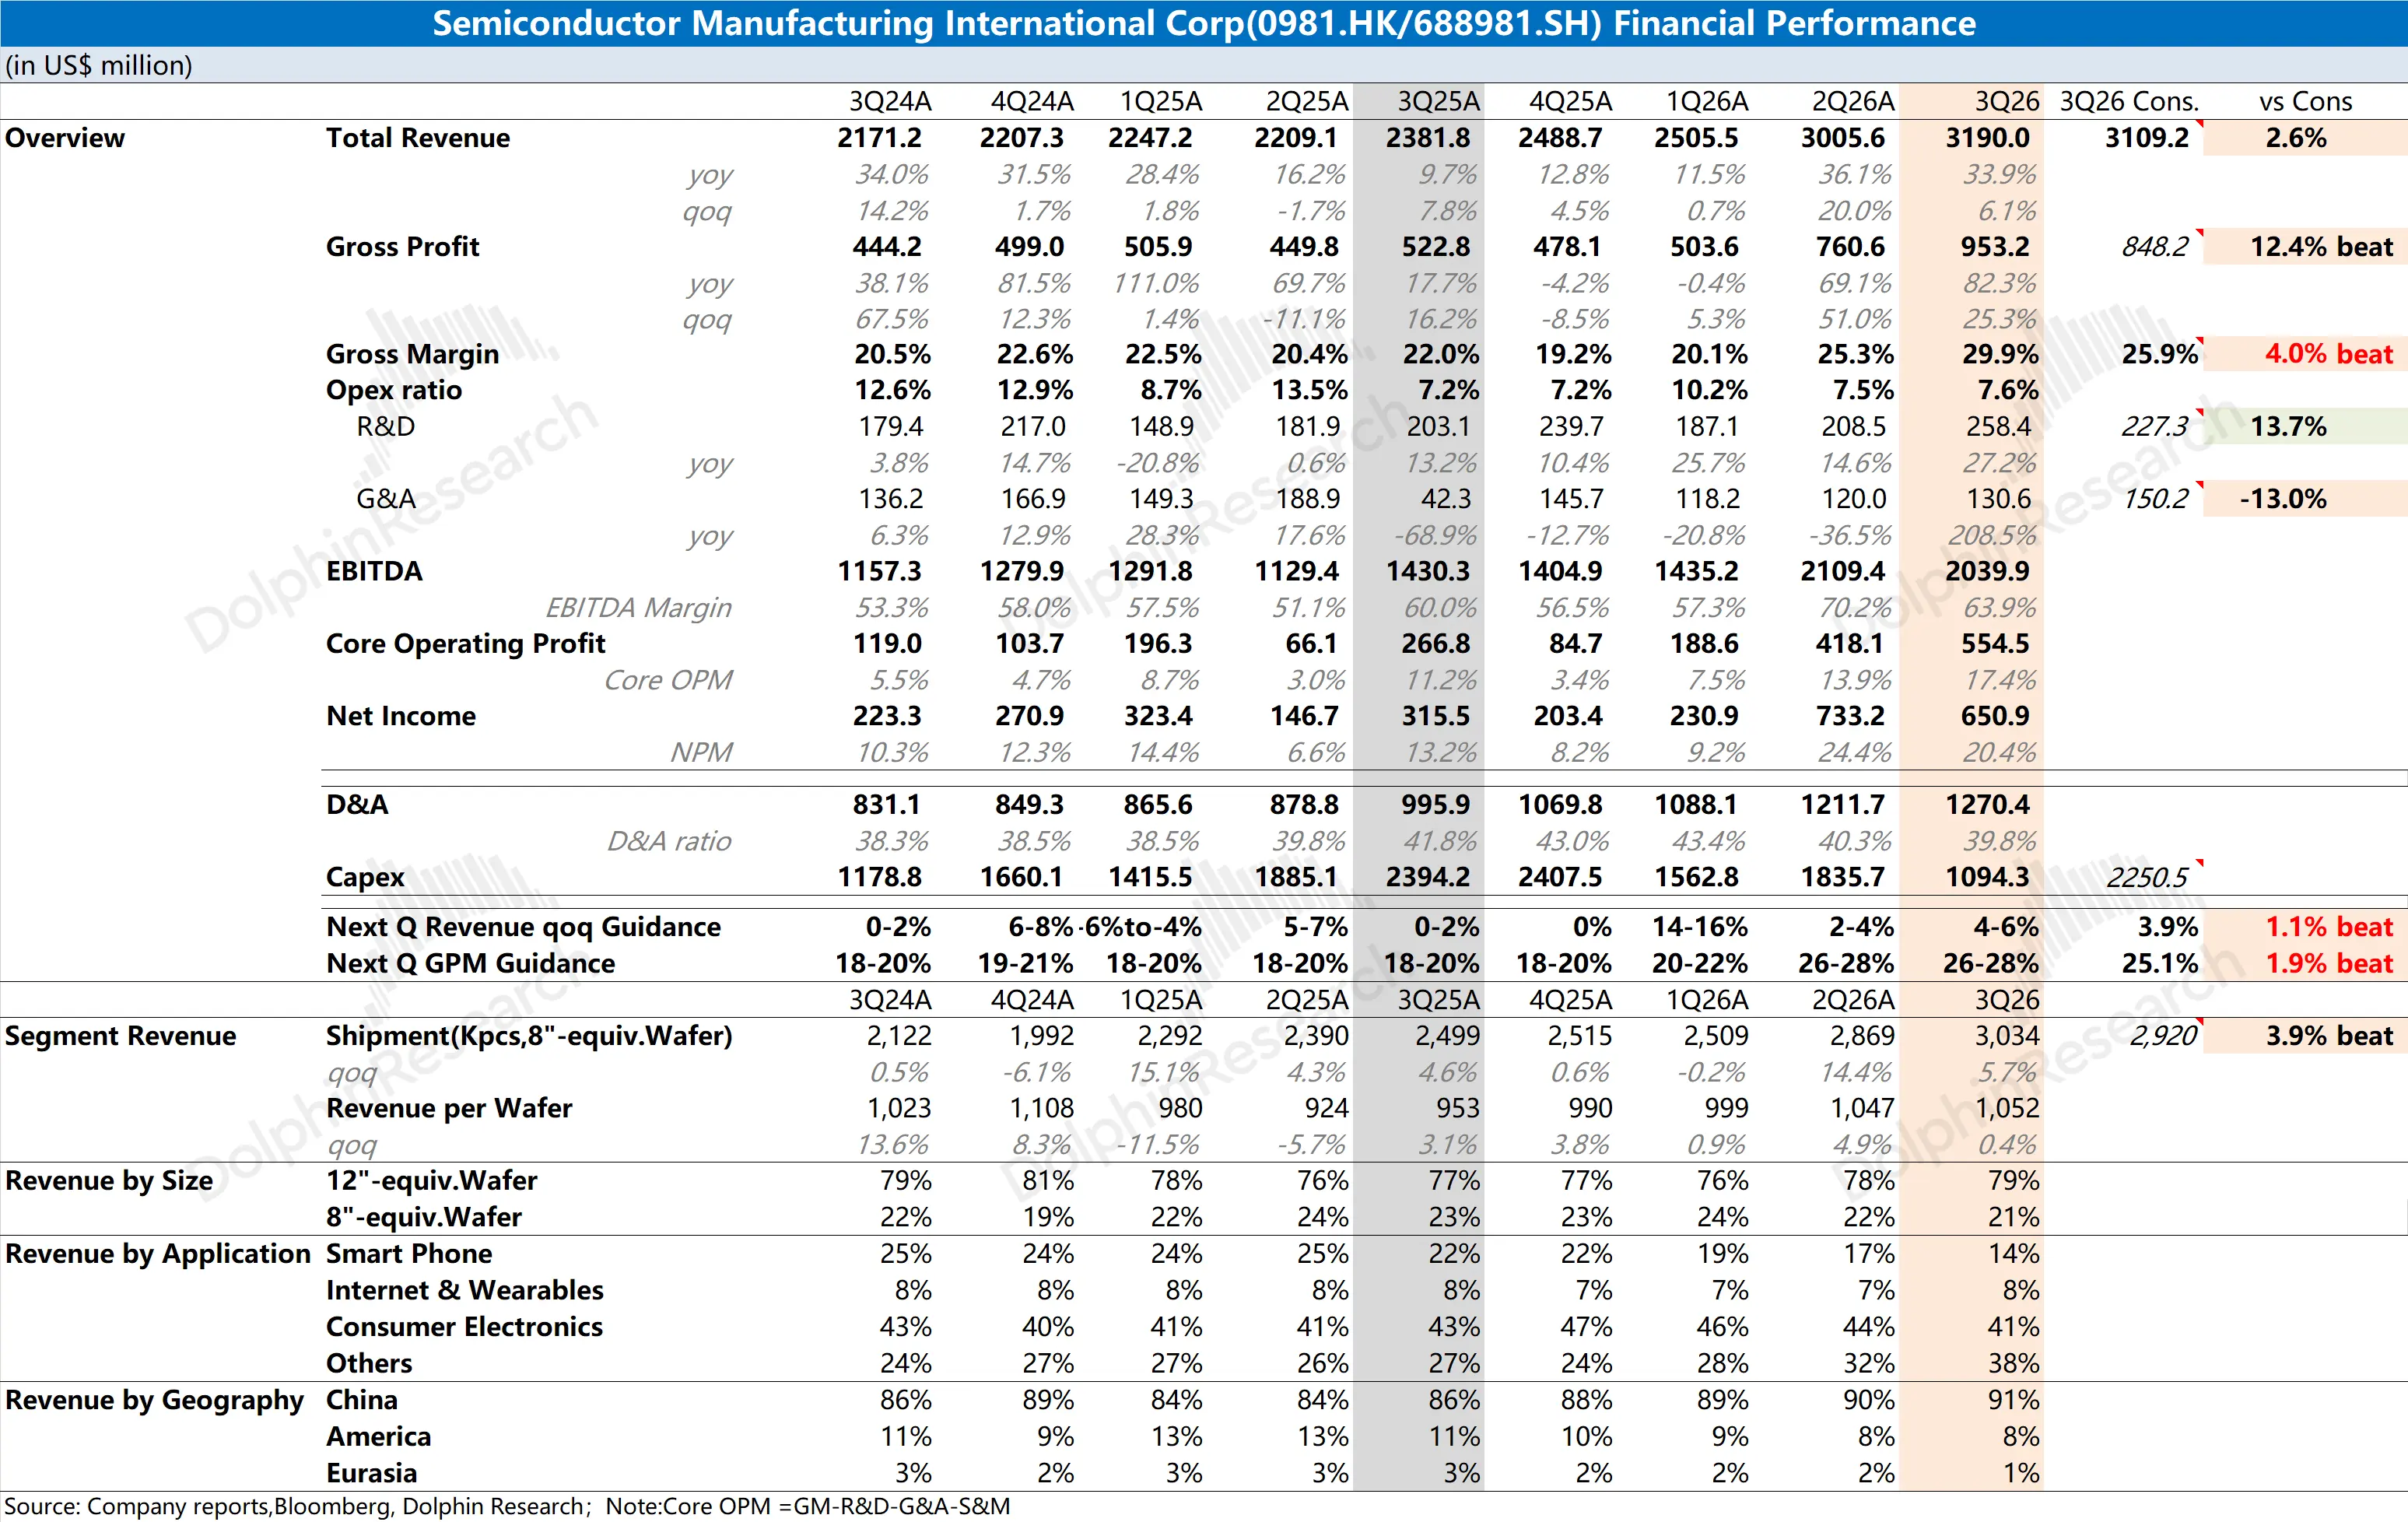
SMIC 3Q26 First Take: headline numbers were a broad beat, with GPM jumping to 30%. However, the margin guide for next qu…
SMIC 3Q26 First Take: headline numbers were a broad beat, with GPM jumping to 30%. However, the margin guide for next quarter points to a sequential decline.
1) Revenue: up 6.1% QoQ, with nearly all of the uplift from shipments. Wafers shipped rose 5.7% QoQ, while ASP per wafer was up just 0.4% vs. +4.9% in Q2.
Management said growth was driven by higher wafer volumes, with utilization rising to 97.3%. This reads as reasonable to Dolphin Research. With lines running near full and capex slowing, further growth will need more pricing, yet price increases are still not flowing through to handset and consumer clients.
2) GPM: up 460bps QoQ to 29.9% (vs. cons 25.9%). By Dolphin Research’s math, ASP per wafer increased by only about $4, while unit cost fell by roughly $45. Drivers were fixed-cost dilution at high utilization, with costed D&A up just 2.3%, and a better product mix, with other manufacturing cost per wafer down about 7.5%.
This implies the margin driver shifted from pricing to utilization plus mix. But with utilization already at 97%, dilution-driven gains are increasingly limited.
3) Guide: Q4 revenue +4%–6% QoQ, above cons (3.9%). GPM of 26%–28%, also above cons (25%) but down about 3ppt QoQ.
By Dolphin Research’s estimate, if shipments track capacity and grow ~2%, the guide implies ASP per wafer up ~2%–4% QoQ, with pricing contributing again. Assuming full-year D&A rises ~30%, Q4 D&A could increase by another ~$110mn, likely weighing on GPM by ~250bps.
No update on the full-year plan, but Q3 capex was only $1.09bn. To match last year’s roughly $8.1bn, Q4 would need about $3.6bn. Watch for details on the earnings call.
Dolphin Research’s take: this print does not change the mid-cycle case for mature nodes seeing both volume and price up, supported by AI-adjacent demand spillover and ongoing localization. The company’s GPM has reached the 25%–30% range, and with near-full utilization, the focus should shift to what will drive the next leg of growth. For more, follow Dolphin Research’s subsequent commentary and Trans. $SMIC(00981.HK) , $SMIC(688981.SH)
The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.