

Tencent 3Q26 First Take: Q3 piled pressure on shareholders — spent more, earned less. vs. expectations, the delta sits o…
Tencent 3Q26 First Take: Q3 piled pressure on shareholders — spent more, earned less.
vs. expectations, the delta sits on costs.
Beyond the print, investors will focus on how prepayments are handled amid limits on remote compute, the roadmap for deploying compute, and any changes to Capex targets.
Worth tuning into the call.
1) Two standout numbers: core operating profit fell 6% YoY.
Free cash flow was -RMB 70bn, likely the two figures that will jar investors most.
Given unprecedented AI capex, a profit air-pocket at traditionally asset-light Tencent is not a surprise.
But the shareholder base skews toward value investors and lower-risk insurers who track cash profits. Until the unit economics of AI and cloud leasing show up in the P&L and cash flows, the story will be a hard sell.
Q3 recognized Capex came in at RMB 81.4bn, well above Street’s RMB 55–60bn.
Full-year now looks >RMB 220bn. It includes ~RMB 86bn of compute prepayments; ex-prepayments, FCF was RMB 16.9bn, still below prior years.
2) Revenue miss mainly in Intl games; cloud and ads were solid.
Q3 revenue was RMB 207.3bn (+7.5% YoY), ~RMB 3bn below consensus, driven by softer Intl games and social network.
Ads rose 18%, aided by short-form drama (IAA often ~70%).
After the 'Green Bubble' mini-dramas launched via WeChat Mini Programs, traction has been strong. Creator incentives were raised in Oct, drawing studios from Hongguo to Green Bubble; MAU has reached 150mn.
Cloud is reported within FinTech & Biz Services; standalone growth accelerated to 35%, at the top end of sell-side estimates.
Workbuddy DAU exceeded 10mn, up from 6.13mn in Sep with faster MoM momentum.
3) Margin pressure from IT and content costs.
Opex ratios were stable, so the variance comes from compute-related costs. Drivers include higher server colocation and D&A, plus content costs (likely from consolidating Ximalaya long-audio rights and mini-drama distribution).
4) Buybacks constrained: Q3 repurchases totaled HKD 7bn at an Avg. price of HKD 443/share, taking 9M to HKD 30bn; full-year likely under HKD 50bn.
If compute spend cannot be deployed, shareholder returns could re-accelerate. $TENCENT(00700.HK) , $Tencent(TCEHY.US)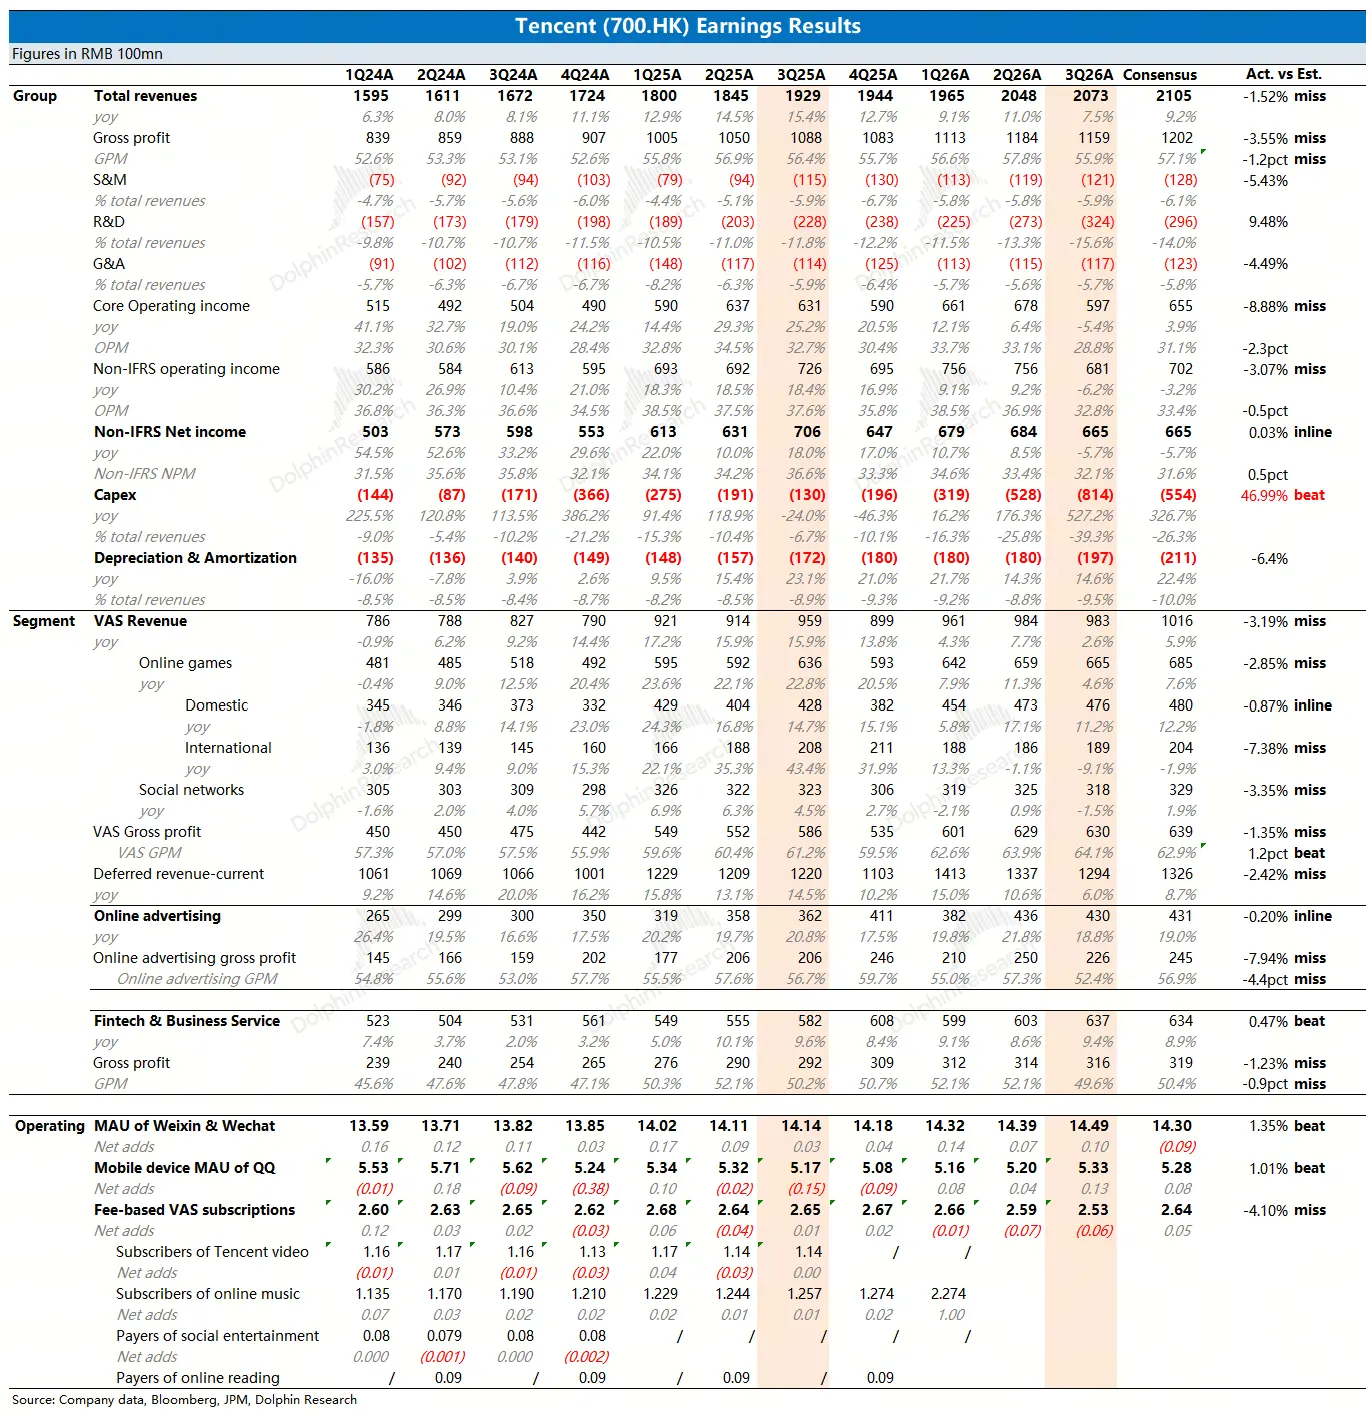
The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.