

The second driver of high GPM for optical module leaders sits downstream: customers like Nvidia, Google, and Amazon diff…
The second driver of high GPM for optical module leaders sits downstream: customers like Nvidia, Google, and Amazon differ in speed grades, form factors, and architecture choices, resulting in a massive SKU count. Who can accommodate that breadth?
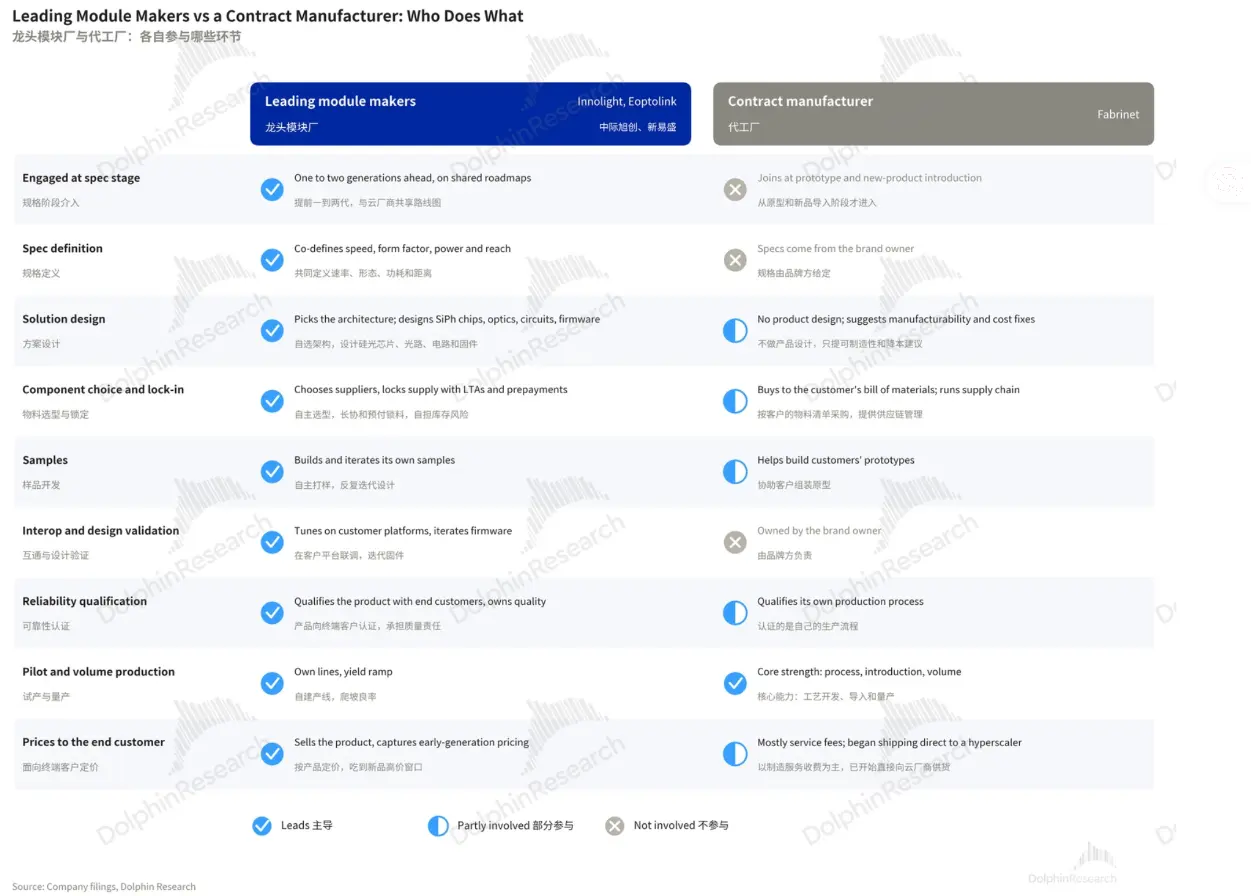
Customers are not just choosing a supplier; they want partners that co-define specs and deliver volume on schedule. Dolphin Research sees this as the second reason why leaders such as InnoLight and Eoptolink earn higher margins than pure assembly OEMs.
• Early engagement: Leaders typically co-develop the next, even the next-next generation during product introduction. Cost-down levers (e.g., replacing EML with silicon photonics) are kept in-house; when the new generation ramps and pricing is higher, they sell directly to end customers. Contract manufacturers only collect a manufacturing service fee and do not take design, inventory, or pricing risk.
• Scale capacity: With numerous SKUs layered on large-volume demand, vendors with scalable capacity are best placed to take the orders. This gives leaders a distinct scale advantage.
Vendors that co-define next-gen specs with customers and win qualification early can command a premium. That widens the gap vs. pure contract manufacturing.
The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.